2026.09.22 | Substack | Markets | TMTB Morning Wrap
原标题:TMTB Morning Wrap
Good morning. QQQs flattish after the big day yesterday as Oil -5%. Yields down 2-3bps across the curve.
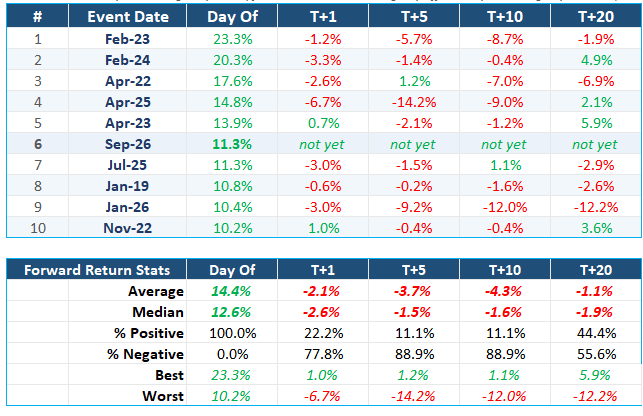
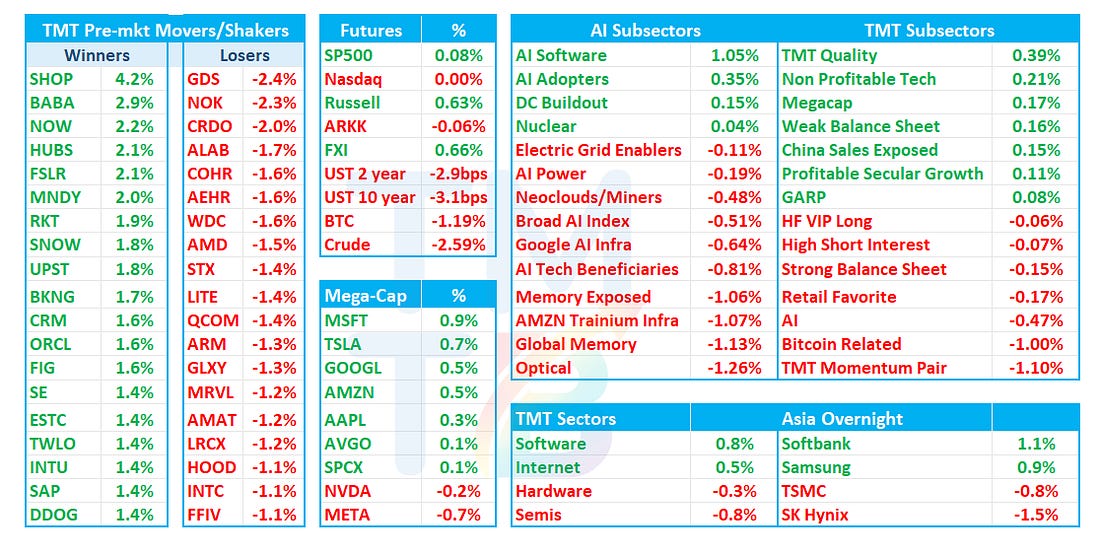
In the U.S., semis -1% taking an early breather after yesterday while Software/Internet both up 50bps+. SHOP +4% leading the way higher on some agentic loser --> pot'l agentic winner narrative reversal after Tobi and Mark announced SHOP’s deeper integration into Muse. BABA +3% after their APSARA conference where they laid out a path to 20GW of data-center power by 2032 and unveiled a new chip. MSFT +1% leading Mega caps higher while META -70bps digesting yesterday’s big move (2nd biggest non EPS ever). Here’s META fwd returns after big moves (h/t J. Fazzuza at Jefferies for the idea):
Overnight, Asia mostly quiet despite the big move in the U.S.: Hang Seng +0.18%, HSCEI +0.28%, SHCOMP +0.06%, Shenzhen -0.01%, Taiwan TAIEX +0.17%, Korea KOSPI +0.15%
Let’s get to it…
SNDK: Rosenblatt initiates Buy/$2,400, sees AI turning NAND from commodity storage into a system-critical component
Rosenblatt says rising model sizes and inference intensity are shifting NAND’s value proposition toward density, performance, endurance and supply certainty, with Sandisk’s BiCS8/BiCS10 roadmap supporting a favorable cost/performance position. Rosenblatt highlights management’s FY28–30 framework for mid/high-teens revenue growth and new business-model agreements with eight major NAND customers covering an estimated ~65% of FY28 production, which should reduce historical cycle volatility. Rosenblatt sees FY30 non-GAAP EPS approaching ~$300 and initiates Buy with a $2,400 PT.
ERIC: MS downgrades to UW/$9, sees North America weakening and limited AI/DC exposure versus NOK
MS says Ericsson’s North American revenue is declining and margins are rolling off peak levels, while the stock’s +15% YTD move has partly benefited from Nokia’s broader rerating. MS argues that comparison is less compelling given ERIC lacks direct AI/data-center exposure and prefers NOK within European telecom equipment. MS downgrades to Underweight from Equal Weight and cuts PT to $9 from $11.
SHOP: DB says Muse partnership helps refute AI-disintermediation bear case, reinforces Shopify as commerce infrastructure layer
DB says Shopify CEO Tobi Lütke announced Muse will let consumers discover Shopify merchant products and complete purchases via Shop Pay inside the agent, another proof point that leading AI platforms are integrating with SHOP rather than routing around it. DB argues Shopify Catalog, merchant connectivity, trusted checkout and payments infrastructure remain valuable even if the consumer interface shifts to agents, though take-rate economics remain an open question. DB sees agentic commerce as TAM-expansive and reiterates Buy/$185.
META: StoneX says Muse traction is real but monetization looks more like cost recovery than a near-term profit driver
StoneX says Muse’s ~730K U.S. downloads in its first 10 days and #1 App Store ranking validate product-market fit, but argues the product materially increases infrastructure intensity through dedicated VMs, browsing, storage, CPU/memory and subagents. StoneX sees subscriptions primarily covering compute costs rather than creating meaningful standalone profit, with longer-term upside more likely from commerce referrals/transaction economics and reinforcing WhatsApp/Instagram/AI Glasses engagement. StoneX maintains Hold, arguing strong adoption adds to rather than resolves META’s AI ROIC debate.
META/CPU: Tae Kim says Muse validates personal-agent demand, but CPUs are the cleaner way to play the trend
Tae Kim says Muse’s #1 App Store ranking and META’s +11% move show investors are beginning to price personal AI assistants as a major new consumer platform, with MS estimating every 100M Muse users could add >$1B of revenue and ~$0.35 of 2028 EPS. But he sees the ultimate app winner as highly uncertain given coming competition from OpenAI, GOOGL, AAPL and others, and instead prefers the picks-and-shovels CPU trade as agents drive massive incremental browser, scheduling, search and code-execution workloads. He favors AMD/INTC/NVDA/ARM, avoids QCOM, and sees EXPE/BKNG as negatively exposed as agents increasingly control the travel customer relationship and pressure OTA commissions.
META: Mizuho says Muse + Connect increasingly make META look like a consumer AI platform, reiterates OP/$750
Mizuho says Muse’s rapid adoption, including ~730K downloads in its first five days and ~2.5M cumulative installs by Sept. 21, strengthens the case that META is building a broader consumer AI platform rather than a standalone agent. Mizuho expects Connect to showcase Muse-on-glasses, where hardware + model + agent + commerce converge, potentially creating a new distribution layer for search, commerce and digital services. Mizuho also sees third-party connectors and transaction-based monetization as meaningful longer-term upside, though agent quality and competitive response remain key risks.
BABA: Alibaba Unveils AI Chip to Drive 20GW of Data Centers by 2032 - Bloomberg
> Bloomberg reports Alibaba unveiled its Zhenwu V900 AI accelerator, claiming ~3x the performance of its predecessor and support for clusters of up to 500,000 chips for frontier-model training. Alibaba is targeting 20GW of cloud data-center capacity by 2032 as part of its $53B+ three-year AI investment push. The company also plans a 5–10T parameter model and is preparing to list its T-Head chip unit.
BABA: GS sees AI Cloud scaling toward 20GW by 2032 with Qwen + custom silicon strengthening the stack after APSARA conference/management meetings
GS says after Alibaba’s APSARA conference, including an analyst meeting with the Group Chairman and management, the company laid out a path to 20GW of data-center power by 2032, supported by Alibaba Cloud, partners and its custom T-head silicon. Management highlighted Qwen’s roadmap toward much larger 5–10T parameter models, Qwen MaaS ARR already at ~RMB20B and tracking toward RMB30B by YE26, while new Zhendingwu V900 infrastructure targets ~3x current performance. GS remains above Street on Alibaba Cloud growth at ~53%/55%/55% y/y over the Sep/Dec/Mar quarters and reiterates Buy.
Analogs: Hearing Edgewater positive saying July/Sept demand activity strongest YTD, with B2B holding 1.2-1.5x
Memory:

TWLO: TD Cowen raises PT to $300, sees consumer AI agents creating a new communications demand vector
TD Cowen says rapid adoption of Muse, Instinct and other consumer agents should drive higher volumes of calls, texts, WhatsApp messages and agent-to-agent communications, creating incremental usage across TWLO’s communications infrastructure. TD Cowen also sees upside from rising identity/governance needs around agent activity, including Verify/2FA and Styx-powered authentication, and believes these trends can support growth into 3Q/4Q and longer term. Reiterates Buy and raises PT to $300 from $260.
TWLO: Wolfe says consumer agents add a new Voice/messaging demand leg after pre-quiet period call with management
Wolfe says management sees consumer agents like Muse/Instinct driving more “exhaust” communications including OTPs, reservations and notifications, while Voice should benefit because there is no viable OTT alternative to traditional telephony for many agent use cases. Management also sees longer-term upside from two-way messaging and agentic identity, with compliance/trust potentially becoming a key TWLO differentiator as AI-driven communications scale. Wolfe came away more positive but says 3Q upside should be more modest at ~2–4% versus the prior ~5% beat; reiterates OP/$290.
MSFT: Oppenheimer raises PT to $570 after headquarters meeting with management, sees Azure/M365 acceleration + better capex discipline
Oppenheimer says its meeting with management reinforced confidence that Azure and M365 Commercial can sustain acceleration into FY27 as Copilot monetization strengthens, more compute comes online and enterprises increasingly standardize on MSFT as their primary AI platform. Oppenheimer says management’s tone was positive on demand and agentic adoption, with Azure demand still above capacity through year-end even as GPU dock-to-live times have improved ~50% over the LTM.
CRWV: Evercore ISI deep dives, says portfolio breadth + software differentiation support pricing/margin upside versus other neoclouds
Evercore ISI says CRWV’s differentiation comes from serving the full AI workload lifecycle across training, inference, agents and physical AI, with ancillary products beyond GPUs expected to exceed ~$500M ARR by YE26 and growing >100%. ISI highlights CRWV’s scale/performance leadership, with >1.5GW active today, >1.85GW expected by YE26 and >3GW in CY27, alongside industry-leading inference benchmarks. ISI also sees multiple monetization tailwinds from ~25% higher pricing on long-term deals, better contribution margins, short-duration capacity priced near ~$40M/MW and longer real-world GPU useful lives; reiterates OP/$150.
COHR: Stifel says PhotonLink opens ~$30B incremental SAM, with CPO/NPO ramps adding new growth vectors after meeting with CTO
Stifel says COHR’s new PhotonLink platform expands its 2030 SAM by ~$30B on top of the existing ~$60B portfolio, with full-solution content reaching up to ~$15K per 100T chip. Stifel says its meeting with CTO Julie Eng reinforced that COHR’s breadth across ~16 component categories is a real differentiator, with >10 CPO, >10 NPO and >5 chip-to-chip engagements already underway. Stifel expects scale-out CPO to ramp in 4Q26, followed by scale-up CPO/NPO in 2H27, and sees this content as largely SAM-expanding rather than cannibalizing pluggables; reiterates Buy/$420.
P: JPM sees hyperscaler wins + GM recovery supporting ~20% medium-term growth into Investor Day
JPM says Everpure’s Investor Day setup is anchored by continued enterprise share gains plus hyperscaler revenue potentially reaching ~$1B, or ~11% of sales, by FY30 after securing two of the top five U.S. hyperscalers. JPM expects aggregate revenue growth to track around ~20% medium term, while easing memory-cost pressure and pricing actions should drive gross margins back above 70% and operating margins into the low/mid-20s by FY30. JPM reiterates Overweight, viewing the combination of growth and margin leverage as supportive of a Rule-of-40 profile.
NTDOY: BNP Paribas initiates Neutral/$14, sees strong IP offset by Switch 2 margin/cycle risk
BNP Paribas says Nintendo’s IP remains one of the most valuable and defensive assets in global entertainment, with Switch 2 selling 19.9M units within nine months, but sees FY28 pressure as higher component costs force volume ambitions lower and weigh on gross margins. BNP is also cautious on demand elasticity after Switch 2 price increases and says software momentum has yet to fully validate the platform cycle. BNP models just ~1% revenue CAGR from FY26–29 and initiates Neutral with a $14 ADR target.
DeepSeek / Moonshot / China AI: China probes alleged customer-data routing to Claude – The Information
The Information reports China’s CAC is investigating DeepSeek and Moonshot after Anthropic alleged they forwarded sensitive user data to Claude without disclosure. Anthropic cites over 23 million Moonshot exchanges during May–July and over 12 million DeepSeek exchanges across 14 days in July. Officials have interviewed company staff; the investigation remains open and no penalty decision has been made.
DeepSeek/China AI: Plans Huawei-powered model training – The Information
The Information says DeepSeek CEO Liang Wenfeng told investors shifting AI model training onto domestic chips is one of the company’s biggest priorities, with Huawei expected to begin delivering new training-capable chips as early as 4Q26. Liang said the effort “has to work,” as DeepSeek looks to reduce reliance on Nvidia and believes Huawei could reach Nvidia-level performance within a few years. DeepSeek is currently training a 2T-parameter model and plans an 8T-parameter model, while investing ~RMB30B to expand compute capacity. DigiTimes, citing earlier Bloomberg reporting, notes a separate planned 160,000-chip Huawei order for a 1GW inference site could take over a year to fulfill.
NTES: BNP Paribas initiates OP/$180, names NetEase top pick on IP-driven game pipeline
BNP Paribas says NetEase has one of the strongest track records in China gaming, with Naraka, Eggy Party and Where Winds Meet validating its ability to build original IP and upcoming Ananta providing another catalyst. BNP models ~8% total revenue CAGR and ~9% games CAGR from 2025–28, and sees strong visibility into earnings growth; initiates Outperform with a $180 ADR target and names NTES its top APAC gaming/entertainment pick.
TCEHY: BNP Paribas reiterates OP/HK$670, sees AI becoming a longer-term growth driver across games, ads and engagement
BNP Paribas says Tencent has built AIGC capabilities across foundation models, developer/tooling infrastructure and distribution through its social ecosystem, giving it broader AI exposure than gaming peers. BNP sees AI reducing content-production costs while also improving engagement, time spent and content distribution, and says more evidence of AI lifting games/ads could drive a valuation rerating. BNP reiterates Outperform with an HK$670 PT.
BILI: BNP Paribas initiates OP/$23, sees ads + margin expansion sustaining the structural growth story
BNP Paribas says Bilibili’s 371M MAUs, 116.5M DAUs and ~113 minutes/day of engagement support continued traffic growth despite slower user acquisition. BNP sees advertising as the primary monetization engine, modeling ~22% ad revenue CAGR and ~10% total revenue CAGR through 2028, while operating leverage drives strong profit growth. BNP initiates Outperform with a $23 ADR target.
ABNB/BKNG/EXPE: Bernstein says AI referral traffic is emerging as a new travel discovery channel, while Expedia app trends remain the key weak spot
Bernstein says AI referrals to OTAs have more than doubled as a share of traffic since the start of 2026, an early sign that travel discovery is beginning to shift toward AI platforms including Google, Muse and Instinct. Bernstein sees ABNB as the cleanest setup with QTD web traffic +17.7% and models a ~2.1% room-night beat, while BKNG trends have improved enough for a ~1.4% beat. EXPE is the concern, with app MAUs down ~11% y/y across brands, potentially outweighing B2B strength and driving a slight room-night miss.
MDB: Citi sees Investor Day + .Local NYC building the AI case, with room to raise long-term targets
Citi says MDB is seeing stronger traction across AI-native/frontier labs and enterprise deployments, with native MCP support driving higher Atlas traffic and reducing friction for agentic workloads. Citi expects Investor Day to highlight Atlas/EA adoption, hybrid/sovereign AI use cases and potentially raise the Rule of 40 framework as Atlas approaches ~30% growth and profitability nears the existing 20% target. Citi remains positive into the events and keeps Buy/High Risk.
SPOT: BNP Paribas says music-industry checks support another price hike, while AI disruption fears remain limited after field trip
BNP Paribas says meetings with current/former music-label executives, digital music providers and artist management reinforced confidence that the next DSP/major-label negotiations should drive another ~$1 subscription price increase, with limited expected churn. Checks were more skeptical on Spotify’s forthcoming AI tier given uncertain artist buy-in and monetization, while audiobook adoption remains healthy and margin-accretive. BNP says the broader industry remains constructive on AI disruption risk, viewing catalogue/IP value as durable and Suno more likely a B2B tool than a scaled consumer threat; reiterates OP/$640.
SPCX:
[
Similarweb
@Similarweb
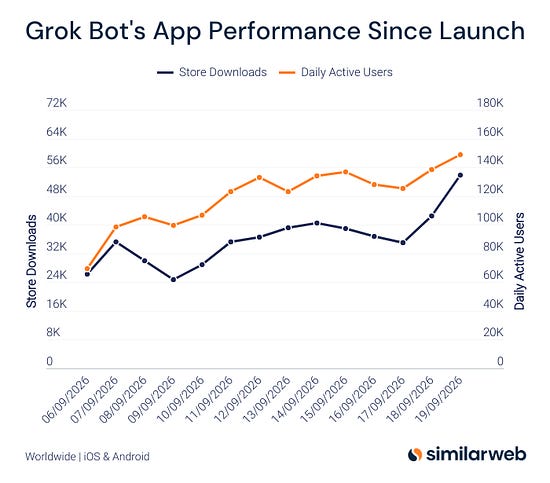
. @bot 's app performance continues to grow, with DAUs nearing 150K
8:26 AM · Sep 22, 2026 · 2.88K Views
1 Reply · 5 Reposts · 41 Likes
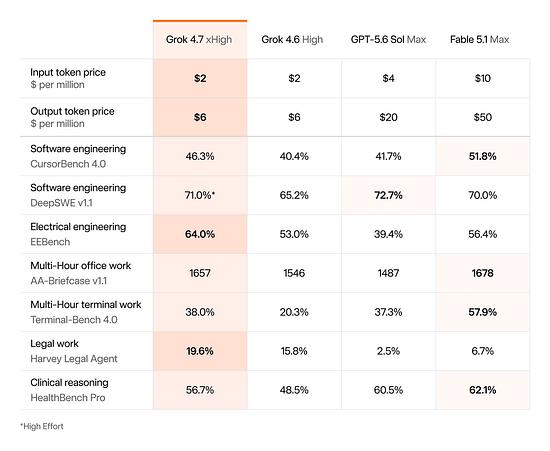
Grok 4.7 out yesterday:
[
SpaceXAI
@SpaceXAI
Grok 4.7 is here. It's a notable improvement over Grok 4.6 at the same price and speed.
4:17 PM · Sep 21, 2026 · 10.7M Views
- 28K Replies · 2.81K Reposts · 26.2K
Likes
NEWS:
OpenAI/Anthropic:
[
@jason
@Jason
My lord, three IPOs are worth more than… all IPOs in the last 45 years of tech 🤯

2:17 AM · Sep 22, 2026 · 259K Views
21 Replies · 382 Reposts · 3.66K Likes
Samsung: HBM4 strains 4nm capacity; expansion under review – DigiTimes
DigiTimes reports Samsung is reviewing 4nm expansion, with HBM4 base dies consuming over half of capacity and utilization already full. Q3 HBM4 revenue is expected to more than triple sequentially. The report also cites 4nm price increases of 10–15% for US/Chinese customers and 5–10% for Taiwanese customers; expansion and a potential 2nm HBM5 line remain under review.
MU: Taiwan union moves toward strike vote ahead of earnings – DigiTimes
DigiTimes reports Micron’s Taoyuan union plans a strike-authorization vote after September 21 mediation failed to resolve profit-sharing demands. An announced one-time NT$1 million employee bonus has not settled the dispute. Micron reports earnings September 30, with a board meeting October 9 Taiwan time; no strike or production interruption has been announced.
SiC / DIOD: China’s capacity squeeze redirects orders to Taiwan – DigiTimes
DigiTimes reports AI-server and high-voltage EV-charging demand is tightening Chinese silicon-carbide foundry capacity, redirecting orders to Taiwan. Six-inch supply is most constrained, while eight-inch ramps face yield and qualification hurdles. The report identifies Episil, Foxconn’s HYS and Diodes as potential beneficiaries, with some Taiwanese six-inch lines already fully utilized; it does not quantify incremental orders or revenue.
AI: Safety concerns and testing deadlines strain researchers – FT
FT reports staff at the UK’s AI Security Institute and major AI labs are experiencing stress linked to safety concerns and demanding testing schedules. More than a dozen senior researchers have left Anthropic, OpenAI and Google DeepMind over two years, citing safety priorities or development pace. The article highlights retention and testing pressures without quantifying a financial impact.
AI: 73% say companies are not doing enough to prevent serious harm – Reuters
Reuters reports its Ipsos poll found 73% of US adults worry AI companies are not doing enough to prevent serious harm, while 55% favor slowing development. Negative views of AI’s societal impact reached 39%, versus 36% last month; 11% were positive. The online survey covered 1,277 adults through September 20, with a ±3-percentage-point margin of error.
DeepSeek: Chinese AI firms invited to UN Security Council discussion – Reuters
Reuters reports DeepSeek is expected to brief the UN Security Council on AI risks on September 23, alongside participation from US labs. Moonshot has also been invited, while DeepSeek founder Liang Wenfeng does not currently plan to attend. The plans remain fluid, and neither Chinese company immediately responded to Reuters’ requests for comment.
OpenAI: Calls for US-led global technical standards for frontier AI – Reuters
Reuters reports OpenAI is proposing coordinated international standards for frontier AI, including systems that improve their own capabilities. The proposal calls for common measurements and incident-reporting protocols across national frameworks. OpenAI describes development pacing as keeping alignment research ahead of capabilities; Sam Altman is scheduled to address the UN Security Council on September 23.
US–China: Summit to discuss trade truce and AI dialogue – Nikkei Asia
Nikkei Asia reports the September 24 summit will address a trade truce expiring November 10, tariff relief and AI cooperation. Beijing favors extending the truce through early 2029, while US officials have discussed three to six months. The two sides plan a formal AI dialogue, with Washington proposing notifications for incidents involving national-security risks.