2026.09.23 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
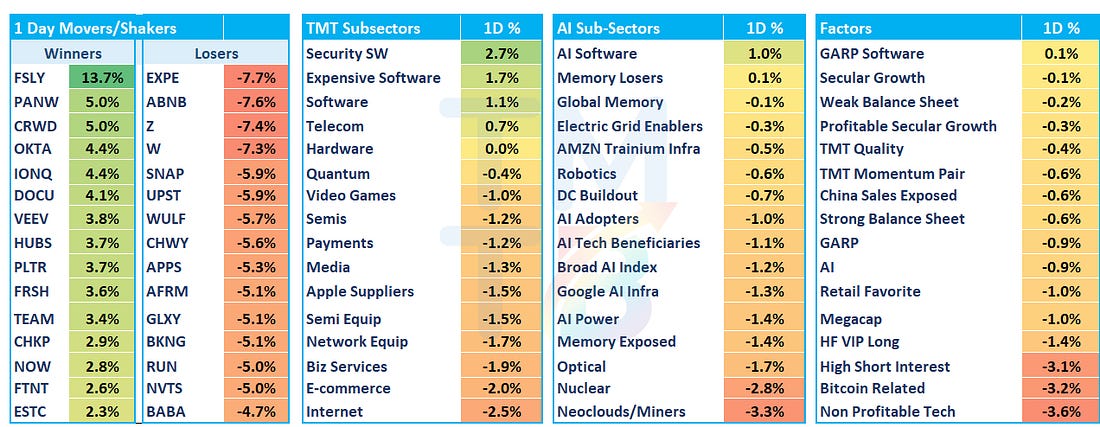
Good afternoon. QQQs -85bps today in another frenzied session driven by animal spirits, just not the usual buy everything type. Instead, investors continued hunting for the less obvious winners and losers from the consumer agentic theme, shuffling or pressing positions and re-examining their priors. PMs are back in the early-2026 SaaSpocalypse workflow: panic, Claude, trade.
Today it was GOOGL’s -4% turn under the microscope after largely escaping the initial selling. Early in the day, Stratechery had a piece arguing that agents pose a more fundamental challenge to GOOGL than chatbots: chatbots still leave a human in the loop to advertise to, while agents are designed to take that human out of the process. His argument is that Google’s slow rollout is not just a product problem, but a business-model conflict: building the best agent potentially undermines the Search economics it is trying to protect. Search also lacks the physical-world anchor that helps protect platforms doing the actual fulfillment or booking work.
There was some similarly good discussion and points made in TMTB Slack here:
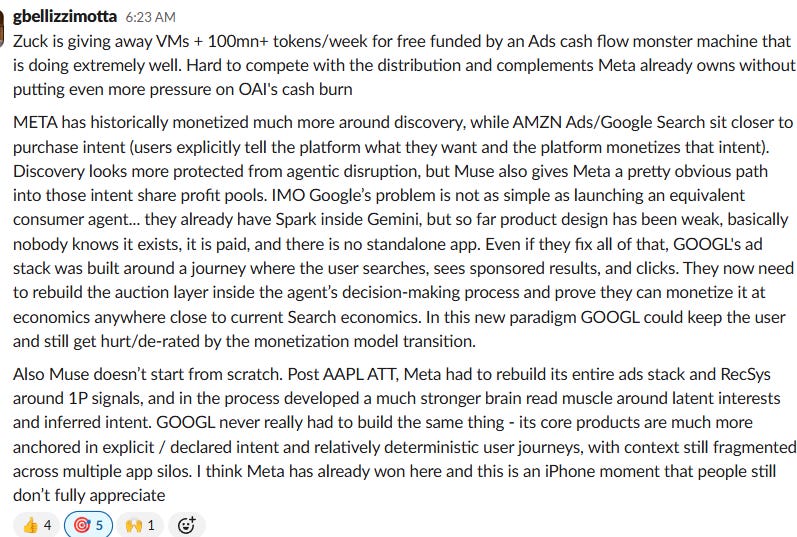
The discussion in TMTB Slack took that a step further than Ben: unlike the initial ChatGPT use cases, Muse goes directly after highly monetizable queries in travel, retail and insurance. The concern isn’t simply whether Google can launch a competing agent, but whether retaining the user would preserve anything like today’s Search economics in a much more competitive market. Bulls pushback that lower take rates aren’t a foregone conclusion, agents could turn previously direct/unpaid commerce into monetizable traffic, and adoption will take time. Investors know that Google can build this, but debate is how much it will earn on the other side, and how painful the transition could be. AnonCapital framed it nicely: I think that's the real narrative question regarding TPU/GCP complex v search. LT probably settled out ok, but air pocket in that transition is probable.
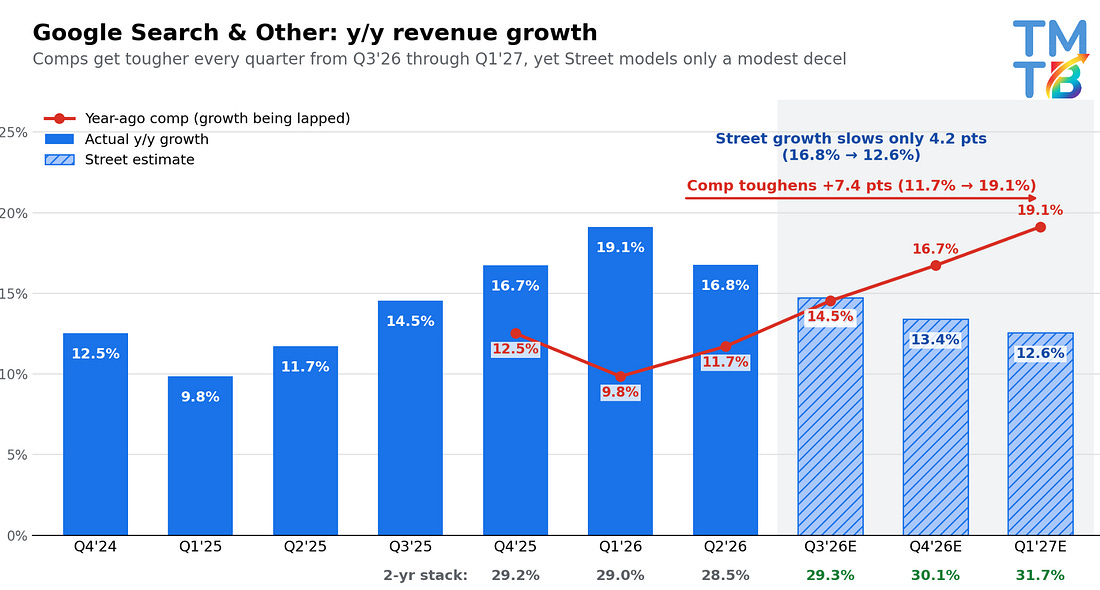
This debate all comes on the backdrop of mediocre 3p data (search inline, possible YT/networks miss) and a search set up that points to a likely search decel to low double digits. We called out this chart in our weekly Sunday showing the tougher comps ahead:
As we’ve written over the last couple weeks, this is one of many debates in Tech that likely won’t be settled soon. We’re still in the discovery and “~~re-rate the multiple~~ shoot first, ask questions later” phase. Outside of GOOGL, perceived losers continued to underperform: OTAs -5-8%; AMZN -2%; CART -3%; DASH -1.5%.
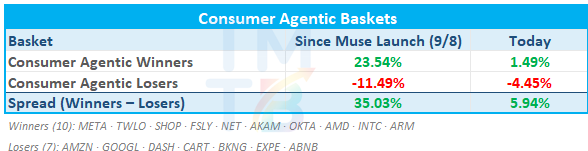
The Consumer Agentic Winner vs. Loser spread was another +6% today and is now +35% since the Muse Launch on 9/8:
In macro land, yields surged 10-16bps across the curve as Fed expects moved in a hawkish direction with the market now pricing in closer to 80% chance of hike at the next meeting and 36bps worth of hikes this year (and 55bps in 27). The cause was a hotter than expected Sept flash PMI report, which the market took as “good is bad.” Brent was up 440bps.
OK, let’s get to the good stuff…
AI/SEMIS
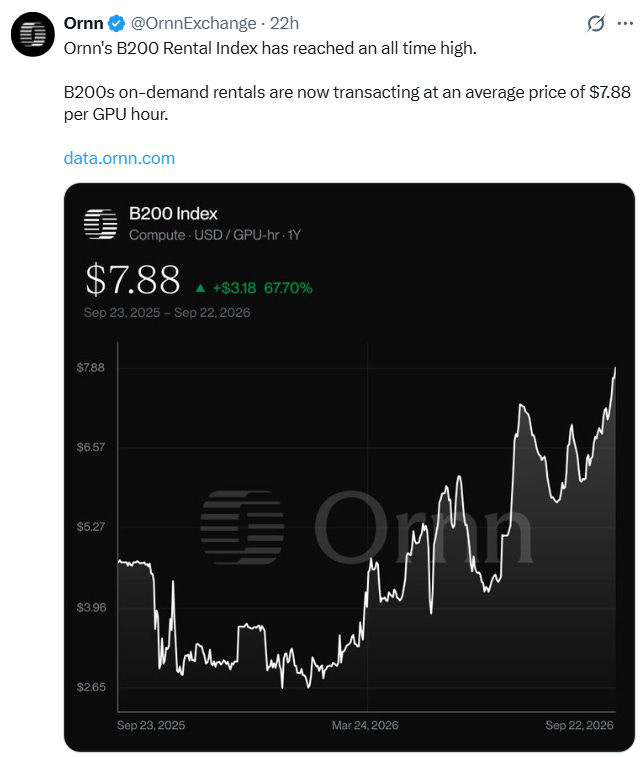
Slow day in semis with HDDs and analogs outperforming. Memory underperformed: SNDK -4%; SKHY -3%; MU -2%. Still a lot of bull vs. bear debate on these stocks despite the better performance as of late. BE/GEV flattish with some outperformance on the bullish GS power note. AVGO -2.6% on the FT reporting that China state-assets regulator is surveying Broadcom switch use at state-backed data centers, potentially leading to informal guidance to reduce purchases.
INTERNET
- META +1% continued to rally ahead of Mark’s keynote at Connect tonight
- OTAs continued to get hit on consumer agentic fears with ABNB -8% leading the way lower as MS called them out saying they have more to lose given they are ~90% direct traffic. So MS’s point is basically: ABNB has more to lose because more of its current advantage is tied to owning the customer interface directly.
- SHOP -3.5% continues the agentic winner —> agentic loser —> agentic winner merry go around. Yup, it’s the phase of the Muse cycle where a product screenshot can move more market cap than an earnings report.Today it was an account on X posting a screenshot of META launching their own wallet in Muse alongside SHOP and Stripe. Stock quickly dipped 7%.
Ummera & dsnc in TMTB Slack were quick to jump in and explain why this doesn’t matter for SHOP:
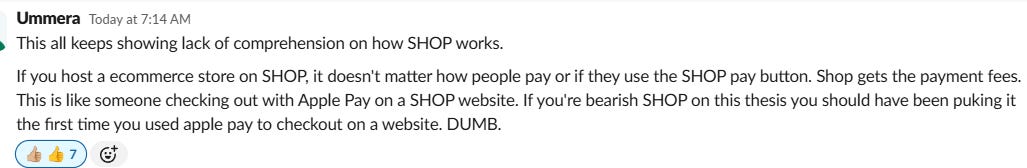

Sell side was also out defending. Devitt at Rosenblatt said today’s SHOP selloff on Meta Pay fears was overdone, as Meta Pay appears to be simply Meta’s existing wallet extended into Muse rather than a new payments rail that disrupts Shopify Payments. Mizuho was also out saying today’s SHOP weakness on Meta Pay headlines is a buying opportunity, arguing consumer wallets like Meta Pay/Stripe Link don’t change Shopify’s payment economics or take rate because Shopify Payments remains the merchant-side infrastructure processing the transaction.
Ok, glad that’s cleared up. We should get some 3p data shortly on SHOP — will be interesting to see if it has accelerated since the MUSE launch at all, which would confirm the bulls’ suspicion of it being an agentic winner.
SOFTWARE
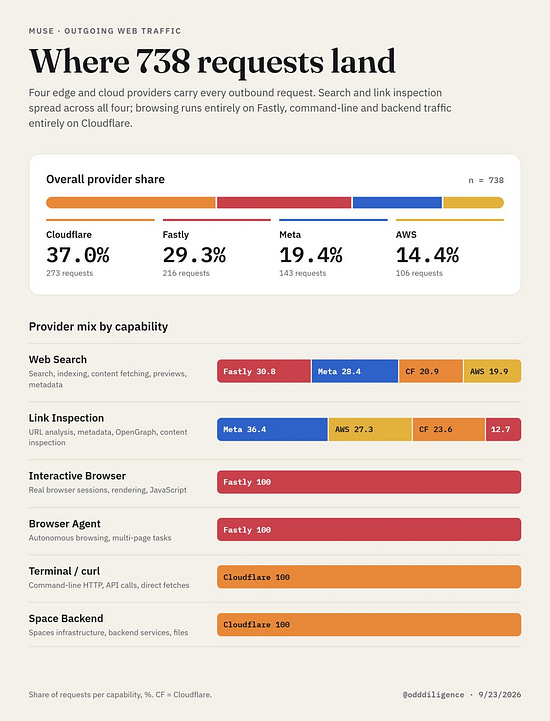
- FSLY +13.7%: This tweet was going around showing FSLY may have a much more meaningful role in Meta’s Muse than investors realized. Odd Diligence ran 738 tests and found Fastly handled ~29% of Muse traffic, including 100% of browser-based requests, versus Cloudflare at ~37% overall
[
Odd Diligence
@OddDiligence
Interesting $FSLY finding from testing Meta Muse. Through a series of hundreds of tests, it appears that the $FSLY role with Meta Muse is greater than analysts have noted Over the past week, I created several test websites and ran 738 controlled tests to send traffic from Muse …
5:20 PM · Sep 23, 2026 · 1.42K Views
2 Replies · 15 Likes
At the Investor Day earlier in the week , 9/22, CEO was asked if they benefit from consumer AI use cases like Muse and said: “Yes. I am pausing because we have a lot of respect for our customers’ confidentiality. But we do benefit from those things... including privacy capabilities for agents.”
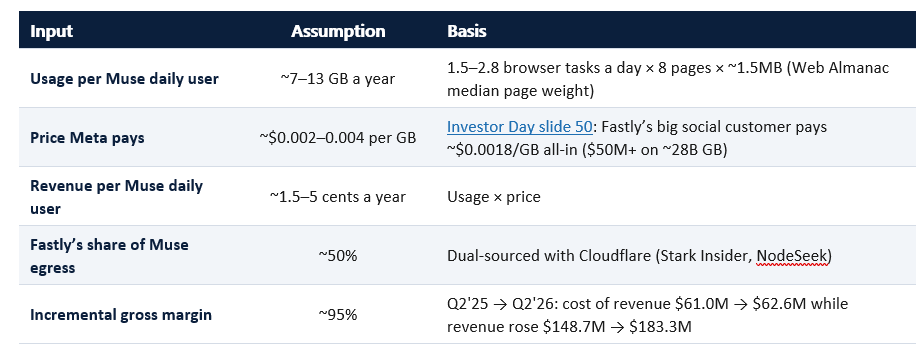
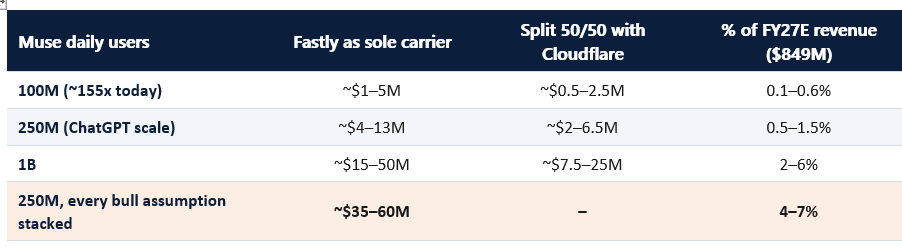
We ran some numbers and the impact, even under a very bullish assumption, is likely only 4–7% of revs and closer to ~10% of operating income. Fastly gets paid on bytes (and possibly connections) carried. Agent browsing is heavy on requests and light on bytes; Fastly’s CEO put it as "agents aren’t watching videos yet." Adding +10% to FY27 revenue (~$85M) needs about 1.7B Muse daily users at realistic pricing with Fastly as the only carrier. That is roughly half of Meta’s entire 3.6B daily users.
Reminder: FSLY fell 38% on 5/7/26 after an OpenClaw/agent run-up, when Network Services grew only 11%. Not saying this can’t continue to rally in this environment, just, you know, beware of the X pumps…(no position here)
- Cyber continues to show outsized strength as names continue to hit new highs: PANW/CRWD +5%.
- OKTA +4.5% sounded bullish at their investor day and we think it’s the best agentic play out of the 3. CEO Todd McKinnon discussed the scale of the agentic opportunity, saying agentic identity could ultimately be as large as the overall identity market. The Blueprint Alliance reinforced OKTA’s positioning as the neutral identity/security layer across a fragmented ecosystem of agents, apps and clouds, while recent O4AA product additions further support that positioning. Monetization is still early, with O4AA currently priced off human identities, but management suggested the model could evolve as agent adoption scales. On the core business, CRO commentary was also constructive, with improving sales productivity, lower attrition and healthy pipeline/yield.
- PLTR +3.7%; Rosenblatt was out saying PLTR’s FAA SMART expansion highlights how much runway remains in government, with the AI-powered flight-management system now being deployed across the three major Washington-area airports in its first U.S. rollout. The firm said the deal reinforces its bullish government checks while commercial is already growing +110% y/y.
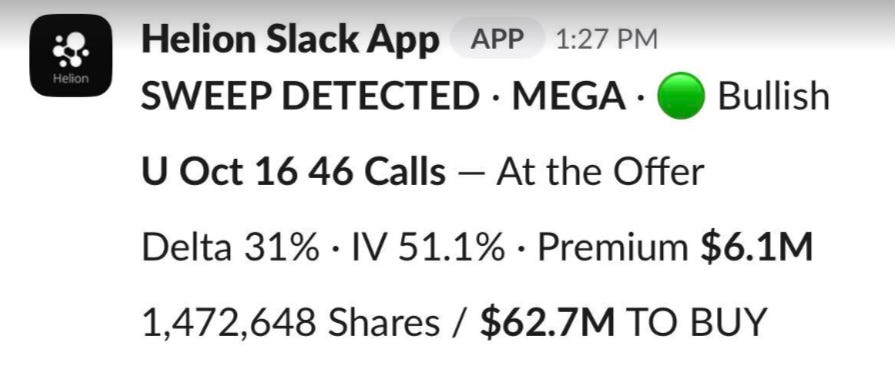
- U +2.3% on bullish call activity and some fairly positive commentary from Edgewater. H-cap flagged for us in TMTB Slack:
- APP -4% as Edgewater continues to be lukewarm on the stock, taking numbers down for Q4 and 2027
- ORCL -3% doing ORCL things.
- HUBS +4% as JPM said partner pipelines remain healthy but sales cycles are lengthening
- CRM +1.8% finally managed a green day.
ELSEWHERE
- DELL +17bps: MS was out recapping a 1-on-1 with DELL COO Jeff Clarke, who argued this AI cycle is structurally different, with Agentic AI driving 87x inference-token growth by 2030 and structurally expanding the compute/storage TAM even as server density pressures near-term unit growth. Clarke expects component shortages could persist 5+ years and sees the infra pricing/margin floor moving higher as TAM expands and competition eases.
- TTWO +40bps: yup still holding, largely because selling it would require admitting I’ve been holding it this long.
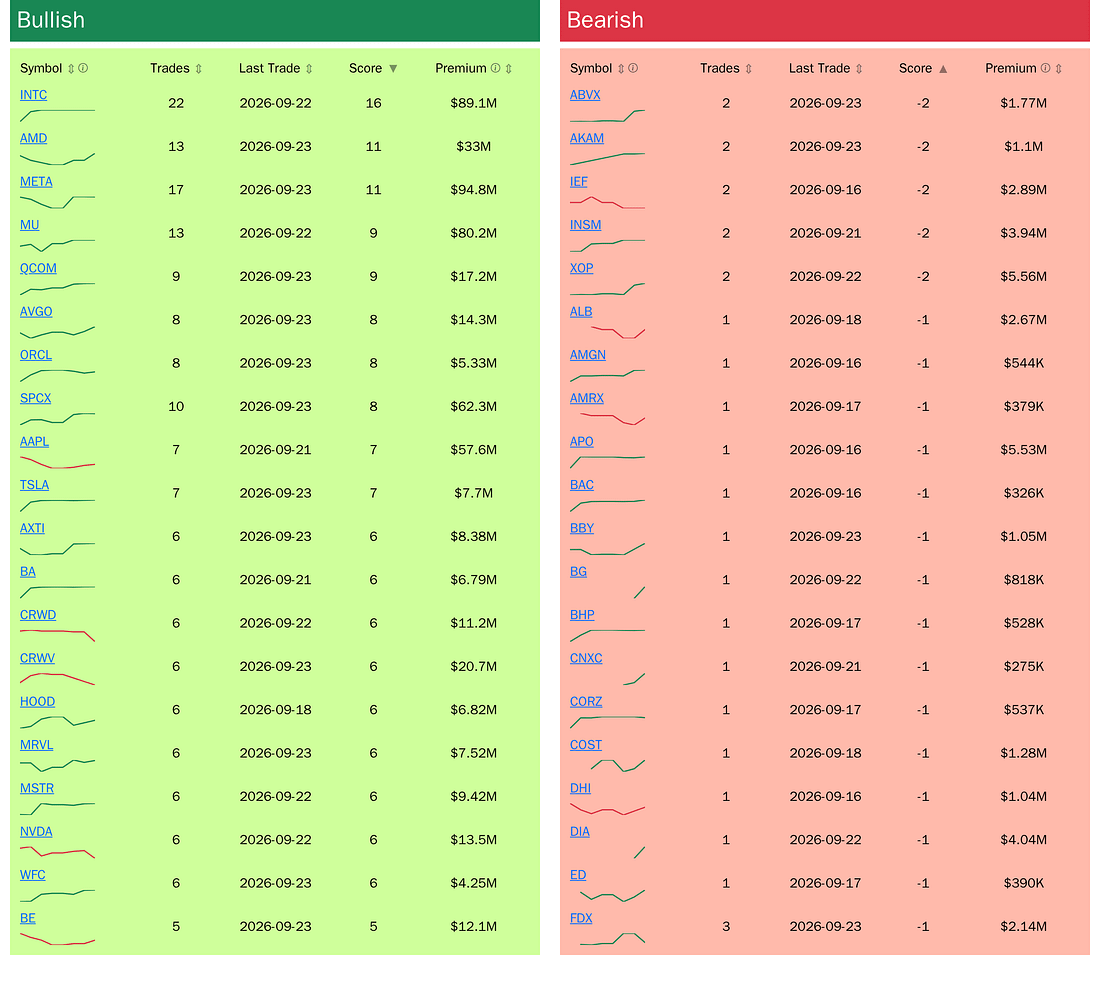
BULLISH AND BEARISH WEEKLY OPTION FLOW
Source: RunningoftheBulltards