2026.09.24 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
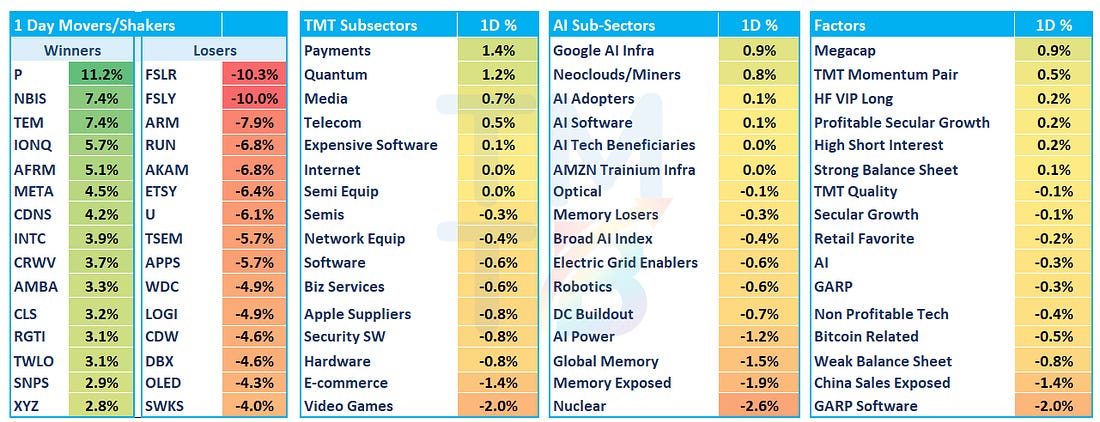
Good afternoon. QQQs flat (-1bp) in a session that looked a lot worse early. QQQs were down ~90bps at the lows before bouncing, led by META +4.5% (best month since 2013, knocking on the door of $2T) and a sharp reversal in the CPU complex (AMD +2.4%; INTC +3.9%, both off -2.5% lows). Semis -33bps after opening down ~2%, while software -90bps lagged again as the AI-loser basket stayed under pressure (INTU/PATH/ACN/CTSH -3%+).
Rates and oil continue to be top of mind on the macro front. The long end sold off again (TLT -1.3%): the 10Y rose ~10bps to ~5.2%, the highest since 2007, and the 30Y touched 5.5%, highest since 2004, helped by a sloppy 7-year auction (cleared at 5.085%, highest since 1993) and more hawkish Fedspeak (NY Fed’s Williams said another hike “may be appropriate by the end of the year”). Crude +2.8% (WTI ~$95; Brent ~$106.60 after spiking to $108 when Saudi Arabia intercepted Houthi missiles aimed at Yanbu, its export route around Hormuz). QQQs turned up around 12:15, jumping ~80bps in 30 minutes, when Reuters reported the US and Iran are discussing a phased deal to reopen Hormuz. Trump is hosting Xi at the White House (trade truce extended to January). BTC flat. Fed expectations didn’t shift much as the market continues to price in 40bps of incremental hikes this year (the odds of an increase on 10/28 stand at >70%) and another ~55bp in 2027.
In AI infra land, the day was bookended by two very different headlines. Before the open, Bloomberg reported ORCL -3.5% sent a force majeure notice to the Blue Owl-backed developer of Project Jupiter, its giant New Mexico campus, to shield itself on payments if the site slips. ORCL isn’t walking away from the capacity and says Jupiter remains on schedule. The glass half full empty read from investors is that this potentially makes lenders more cautious about funding the next project.
After the bell, things more positive as Anthropic signed an $11.6B, seven-year commitment with AKAM (+20% post-close) for CPU capacity. Coming from a frontier lab, not a consumer app after the MUSE narrative ramped CPU stocks over the last couple weeks. Just shows how much CPU demand there is out there across the board.
Details:
The AKAM deal with Anthropic is $11.6B of contractual commitment over seven years to support Anthropic’s “accelerating CPU workload demands” on AKAM’s Cloud’s distributed infrastructure (Can expand by up to another $9B, for ~$20B of total potential commitment). That’s ~6x the $1.8B, seven-year Anthropic deal from May (at the time the largest contract in AKAM’s 28-year history), and the 8-K suggests tonight’s $11.6B comes on top of it (two new project plans signed 9/18 under the May master agreement; worth confirming on the call). The stock had closed at the lows right before the release, giving back part of its edge/agentic run alongside FSLY. Warrant to Anthropic for up to ~5% of the company (7.7M shares) at a $111.33 strike, basically today’s close. ~2% vests on the first payment under the new plan; ~1% more for every additional $3B committed.
Read-throughs from Claude:
AKAM’s cloud already runs on AMD EPYC. The current top tier is 5th-gen EPYC and the one before it is 3rd-gen. I found no Intel or Arm servers anywhere in their lineup. The dollars are modest for AMD. My rough math is about $1–1.4B of CPUs over 2027–28.
JBL. The 8-K has Jabil holding Akamai’s $1.7B of memory on consignment and buying it back at cost as it uses it. That means Jabil is building the servers. It’s big revenue at thin margins.
Lenovo (992 HK / LNVGY). It signed a new 7-year hardware deal with Akamai on 9/23, likely the second server supplier.More details:
$5.5B of capex tied to the deal, including ~$1.7B of extra 2026 capex to “secure and pre-purchase critical supply chain components, including memory” (per the 8-K, a memory order through Jabil). For reference, 1H26 capex was ~$550M and they had $4.6B of cash at 6/30. No change to the 2026 revenue guide. Call ongoing right now…Reminder: AKAM round-tripped the May deal. It jumped 27% on the day, then gave all of it back by 9/18 although that included the big July semis drawdown.
Let’s get to the good stuff…
AI/SEMIS
- Neos strong on the back of a pair of upgrades as GPU pricing remains firm. CRWV +4% was upgraded by JPM saying pricing backdrop has strengthened materially, with July pricing +25% across SKUs, recent short-duration contracts signed around ~$40M/MW, and short-term capacity commanding roughly 3x long-term pricing. BNP upgraded NBIS +7% as they see 2027 as key catalyst as scarcity pricing drives materially higher AI Cloud returns, calling out a path to $22B+ ARR exiting 2027, 30% above street as META/MSFT capacity ramps and incremental capacity reprices higher. Remember, NBIS has more near-term leverage to pricing.
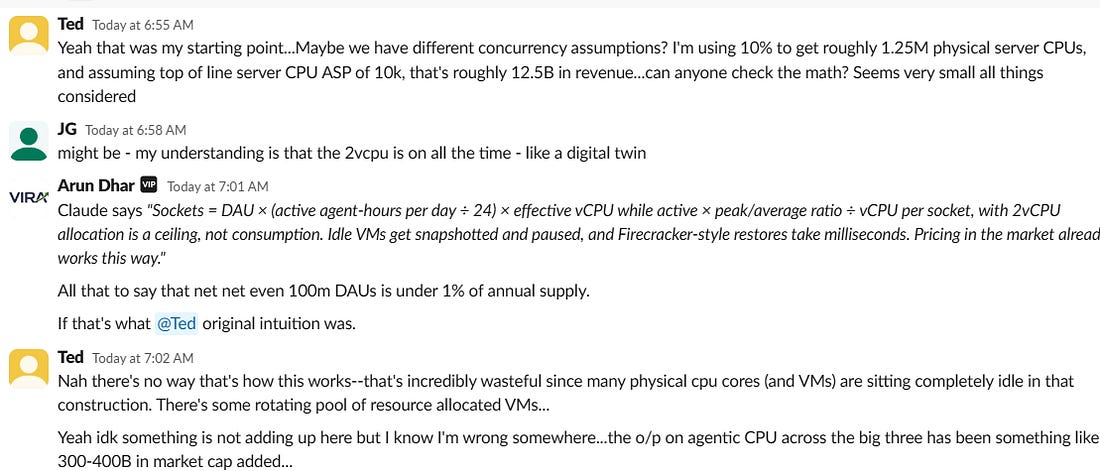
- AMD +2.4% / INTC +3.9% reversed hard off the morning lows (INTC closed at the highs), shrugging off the M-sci shipment datapoint on AMD we flagged this morning. KeyBanc’s bus-tour note helped INTC (14A “~1 year ahead of where 18A was”), and NBIS told customers it’s raising AMD EPYC CPU instance prices ~25% on 10/1. Lots of questions on the odd one out: ARM -7.9% and closed near the lows. No great answers other than giving back some outperformance over the last two weeks. Lots of debate over how much actual incremental impact there is from MUSE and consumer agentic apps where event some bulls think although directionally right, a little over their skis at the moment (although Anthropic/AKAM deal post-close just adds some fuel to CPU demand is insatiable narrative). Some good discussion in TMTB Slack here on the topic:

- P +11% as they updated their guide well above street at analyst saying, saying they expect FY28 revenue to $7.0–7.3B, +39–45% y/y, vs. consensus ~$6.2B, putting the midpoint ~15% above Street and accelerating from ~37–38% growth expected in FY27
- HDDs weaker despite some positive checks at Edgewater: WDC -5%; STX -2%. This comes on the back of Cleveland checks, which we heard called out Average ASP of $27/TB in ‘27 and some OEMs already paying $40+/TB. Memory also underperformed: SNDK -3.5% continues to chop after Raspberry pi’s CEO said NAND prices may be approaching peak.
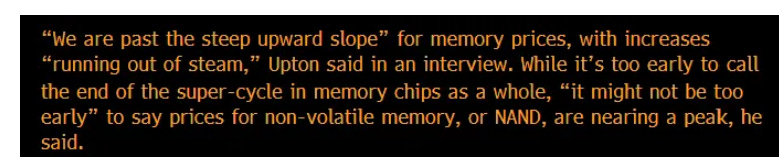
Investor preference for memory names has declined significantly as the story has changed from one of earnings/pricing upside to cheap & buybacks. MS was out last week saying that clients went from $24 of long for every $1 of short to about 5.5–6 to 1, and it is the area being added back to least and sector with biggest debate and growing skepticism. MU +80bps acted a little better in front of earnings next week. Outside of CPUs, it’s unclear to us where the memory beta bid will shift to in AI semis. Still a very choppy environment with lots of dispersion and open debates/lack of clear NT direction/narrative across the sector.
- CDNS +4.2% / SNPS +2.9% as BNP upgraded SNPS to Neutral from Underperform ($420 PT) and BofA framed the 9/30 investor day as a re-rating catalyst.
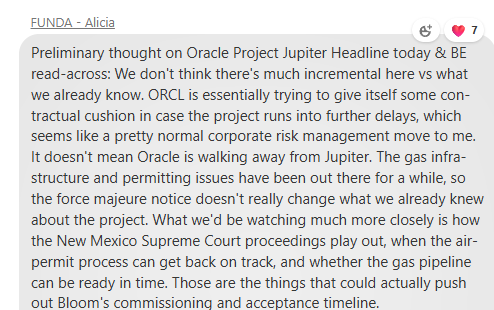
- BE -3.1% (-8.7% at the lows): ORCL’s Project Jupiter runs on ~2.45GW of Bloom fuel cells. Good thoughts from FUNDA:
- Optical mixed: TSEM -5.7%; COHR -3.3%; LITE -0.9%; CIEN +0.7%; MTSI +3.3%. TSEM closed at the lows with no news after a +14% five-day run. Wolfe’s ECOC recap was about as bullish on demand as it gets (META showed amplifier huts going from 48 fiber pairs to >4,000; Lightera has closed its fiber order book; PAM4 DSPs sold out through 2027 at AVGO and MRVL), but Notter is resisting COHR’s PhotonLink story. Jefferies’ Curtis sees optical next year “closer to a double” and named MTSI his top SMID pick.
INTERNET
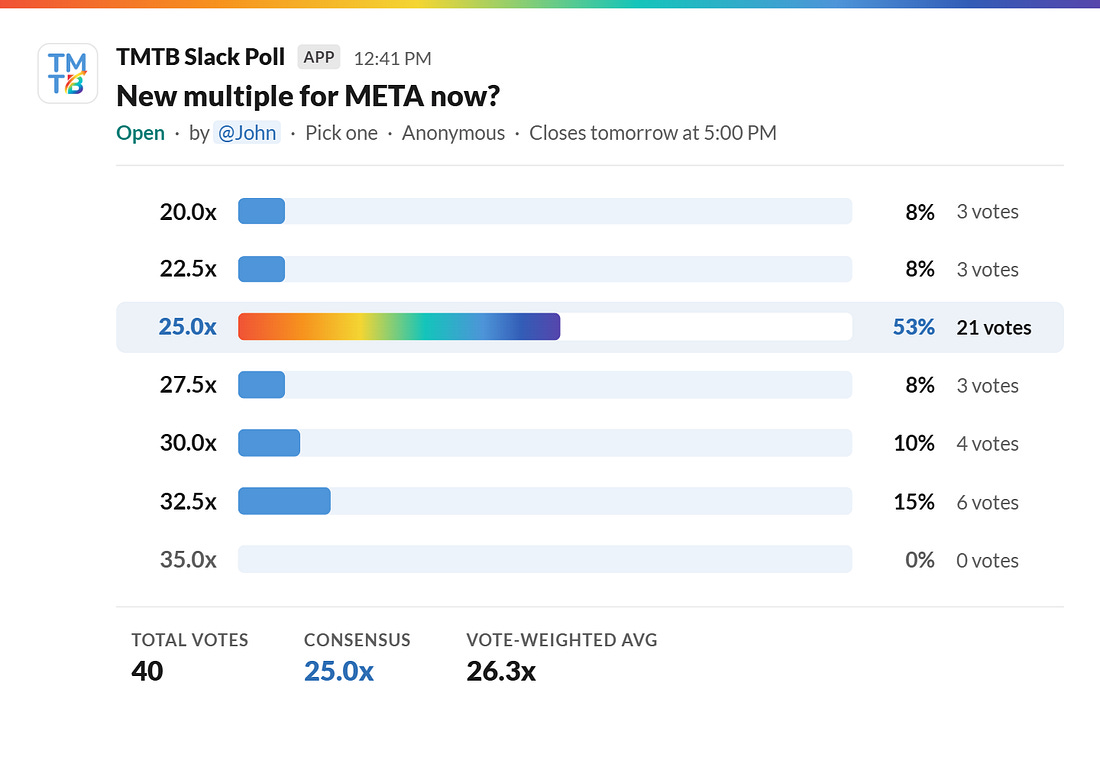
- META +4.5% continues its outstanding run, hitting 52-week highs and moving within a stone’s throw of ATHs near $800. An agency budget check we heard today also had Meta 3Q spend growth reaccelerating to 13.5-14% (from 12-12.5% three months ago) on Instagram/Reels. Bulls are circling 25x CY27 EPS of $36 despite Muse likely not driving much incremental earnings this year or next. Really amazing to see such a 180 in the narrative around the company and Zuck, going from “where’s the return on all this AI spending?” to “whose business model is he coming for next?” as he’s nailed the landing on multiple product launches over the past few weeks
- SHOP +2% continues to act better as investors come around to consumer agentic being a tailwind for now, with SHOP still powering checkout even when shopping starts elsewhere. Some outstanding questions remain around how much GMV is truly incremental vs. simply shifting channels, whether payments attach and take rates hold up, and whether agents eventually gain enough control over shopping traffic to demand a bigger cut. We’ll be on the lookout for 3p data to see if it confirms the burgeoning bullish agentic thesis.
- GOOGL +1.3% with Gemini 4 reportedly nearing release. A check we heard had Google core search tracking HSD in 3Q vs. the 7.5% they'd penciled in, though on AI Mode citation clicks, they said it doesn't come close to offsetting the loss in traffic relative to the conversion rate increase…AMZN flat continues to struggle to gain a bid
- ETSY -6% as Arete downgraded, saying they see limited room for further share multiple expansion, saying Etsy deserves to trade at a discount to its closest peer eBay and citing valuation for the downgrade with Etsy shares up nearly 70% from the February low. Arete noted while company’s recent results showed stability in its marketplace, much of this was driven by tariffs.
- MELI -2.5% slid around a company event where it announced one-hour delivery in Sao Paulo and prescription-drug sales through its own pharmacy (read: more spend).
- OTAs caught a bid: TRIP +6%; ABNB +1.2%; EXPE/BKNG +1% after BTIG argued agents are more likely to route travelers toward scaled OTAs than disintermediate them.
SOFTWARE
- U -6% on META unveiling Horizon Create/Studio, letting users build 2D/3D games from AI prompts on Meta’s own engine and distribute them directly across Facebook/Instagram. The bear read-through is bigger than AI making coding easier: META is bundling creation, the engine and distribution, potentially allowing casual-game creators to bypass Unity altogether. Still early access so far and need to see how this builds out, but a new entrant never a great thing.
- DT +27bps as Oppenheimer added to top pick saying DT’s AI positioning is beginning to show tangible traction, with >1,000 customers observing AI/LLM workloads, +150 q/q, and AI cohorts growing ~1.5x faster than non-AI customers
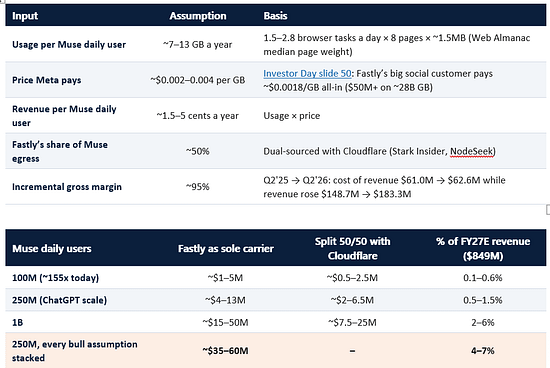
- FSLY -10% giving back some of yesterday’s gains, which were driven by growing excitement around Meta Muse using Fastly, after checks suggested the exposure is real but concentrated in browser-navigation tasks rather than across all Muse traffic. We wrote how the numbers impact didn’t exactly match the stock move — called this out mid-day in TMTB Slack and in the EOD Wrap/X post-close:
[
TMT Breakout
@TMTBreakout
Not saying $FSLY can't continue to rally in this environment, but I ran the math and impact to #s doesn't seem big at all. Agent browsing is heavy on requests and light on bytes. As FSLY's CEO put it this week, “agents aren’t watching videos yet.” Under our usage/pricing…

Odd Diligence @OddDiligence
Interesting $FSLY finding from testing Meta Muse. Through a series of hundreds of tests, it appears that the $FSLY role with Meta Muse is greater than analysts have noted Over the past week, I created several test websites and ran 738 controlled tests to send traffic from Muse
9:48 PM · Sep 23, 2026 · 38.8K Views
12 Replies · 15 Reposts · 177 Likes
We’re not involved and don’t have a strong view, just thought the move yesterday was outsized vs. impact. Overall, everyone seeing uplift to CDN infra likely good for operating mgs/leverage.
- DDOG +2%: Wolfe out after the close raising PT to $340 with a pretty bullish note saying agents are driving more tracing usage, which costs ~2x metrics, while faster software development is lifting APM spend by at least double digits. Wolfe cites anecdotes of ~50% AI-product attach among core customers following August monetization, while initial conversations suggest an increasing likelihood of direct involvement with Muse.
- ORCL -3.5% (-7.7% at the lows) after Bloomberg reported it sent a force majeure notice to a Blue Owl unit, the developer of Project Jupiter, to put off payments if the site gets derailed. Semafor added that New Mexico has repeatedly denied permits for a required gas pipeline, pushing the project back at least six months; banks have lent $18B to build it with $3B of Blue Owl equity below that. Oracle said force-majeure notices are “commonplace in developments this scale” and Jupiter remains on schedule. OWL -3.7%.
- OKTA +60bps continues to act well as investors see it as key beneficiary from agentic AI and after sell-side was out positive after their investor conference yesterday, where mgmt framed agentic identity as potentially one of the largest future categories in cybersecurity, with Okta for AI Agents able to sell independently of a customer’s existing workforce identity provider.
- DBX -4.6% on a Citi downgrade to Sell; Enders called the AI story “premature.” Doesn’t help that DBX shows up in Axios’s “Muse could hit some subscription models” chart making the rounds

- AI losers stayed under pressure: INTU -3.4% (GS reiterated Sell on tax commoditization; -22% in a month), PATH -3.4% (BMO cut its PT to $15 after the investor day: AI ARR >$250M but no long-term targets), and ACN/CTSH -3.3% with IT services weak across the board (EPAM -2.8%; INFY -2.3%; IBM -2.5%) despite no company news. Overhangs keep piling up there: BMO yesterday saw "muted IT services demand heading into CY27," and CTSH itself published a case study of a 7-person team using Devin delivering a 37% net cost saving on a platform rebuild (not good for billable hours).
- ZS -4% AH after announcing CRO Mike Rich is stepping down (staying on as an advisor through YE); Head of WW Sales Ross Tackett takes over 10/1.
- TEM +7.4% closed at the highs as genomics/life-science tools ripped (ILMN +7% ahead of joining the S&P 500 Monday; TXG +11%), plus Leica adding two Tempus/Paige pathology AI apps to its Aperio store.
- APPS -5.7% after its Chief Business Officer resigned to become CEO elsewhere.
ELSEWHERE
- Solar stocks fell after Trump admin indicated that an offer to advance stalled wind and solar projects as part of negotiations on legislation to speed energy permits could be taken off the table: FSLR -10%; RUN -6%
- TTWO -1.6%: Meta’s AI game-creation push hit it too. Red day, as is tradition.
- PC/hardware under pressure: LOGI -4.9%; CDW -4.6%; HPQ -3.2%; DELL -2.5%. No fresh news, but the PC overhang keeps building: HPQ's planning assumption of a MSD decline in CY27 PC units (Monday), UBS flipping 2027 PCs to a decline (Tuesday), and Phison's CEO warning this morning that higher memory prices could weigh on PC/smartphone demand.
- AFRM +5.1% as Truist reiterated Buy ($85) on the expanded Amazon partnership into the UK, calling the pullback an attractive entry at 17x CY28 EPS. XYZ +2.8%; Cash App becomes a direct-deposit option in Workday payroll on 10/1.
- DIS +2%: GS sees the price hikes as a bundling wedge (standalone Disney+/Hulu premium +13% to $21.49 vs. the Duo bundle +10% to $21.99).
- VZ +1.7%: Co told Wolfe its call-center humans are already organized to identify and refuse to talk to bots. Wolfe sees cable, not wireless, as the more exposed side of telecom.
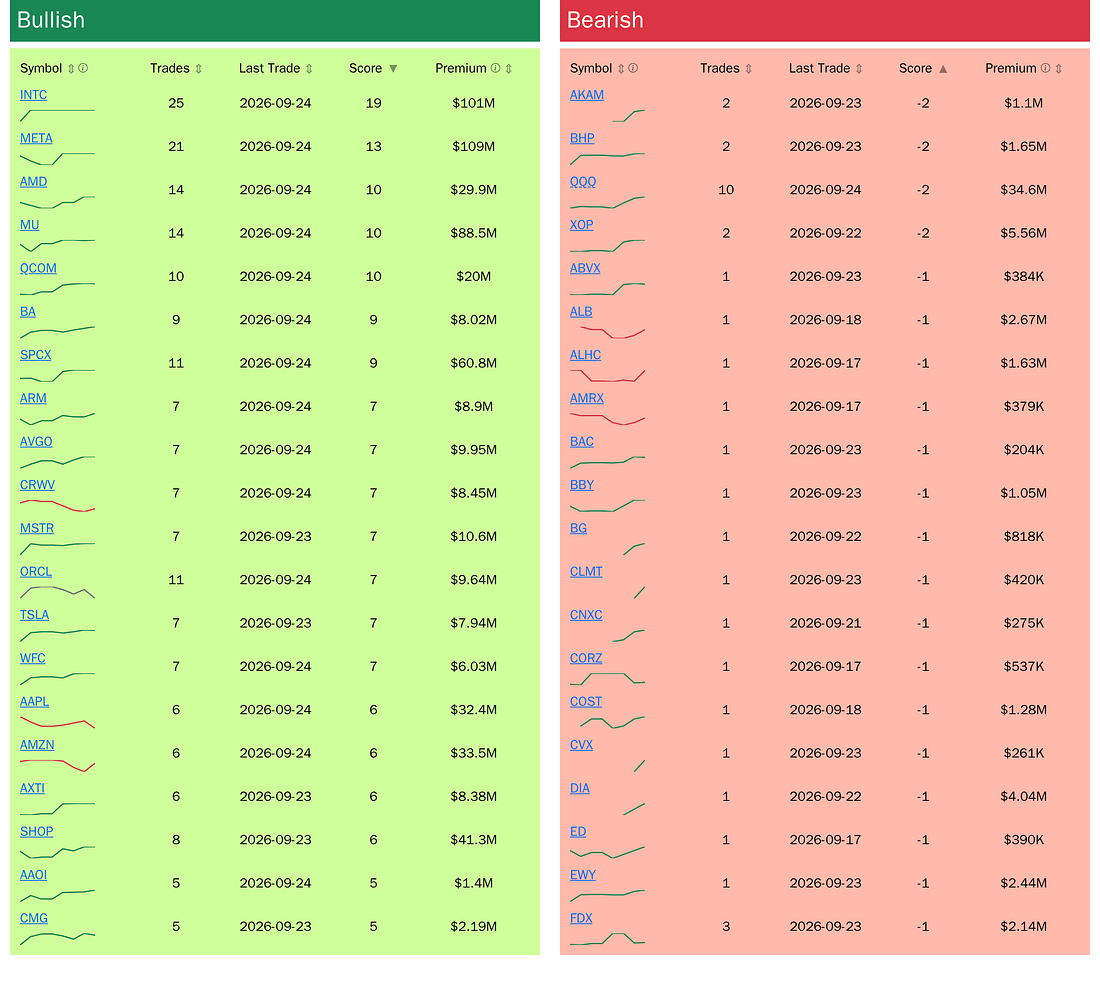
BULLISH AND BEARISH WEEKLY OPTION FLOW
Source: RunningoftheBulltards