2026.09.25 | Substack | Markets | TMTB Morning Wrap
原标题:TMTB Morning Wrap
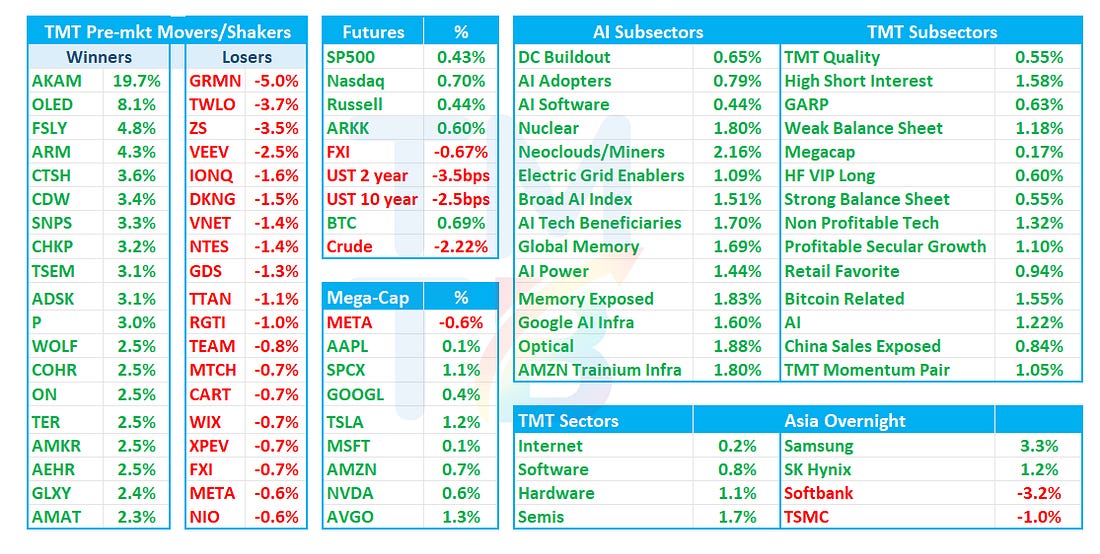
Good morning. QQQs +70bps as investors digest a wave of headlines pointing to a possible diplomatic off-ramp between the US and Iran around Hormuz. The reports first began circulating during Thursday’s session, with Iran later confirming it had sent Washington a proposal that would restore the framework of the June MOU within seven days, after which the two sides would begin talks on Tehran’s nuclear program. Yields ticking down 3-4 bps across the curve although Crude +2.5% is staying bid.
In Tech land, Semis +1.8% helped by the big AKAM/Anthropic deal annoucned after the close for “accelerating CPU workloads”. AKAM +19%. CPU names bid: ARM +4% / AMD +2% / INTC +2%. META -50bps looking to digest some recent strength. SNPS +3% on an HSBC upgrade while TWLO -4% on an HSBC downgrade. DDOG +1.5% as Wolfe says checks show increasing likelihood of being involved with META’s Muse.
Overnight, mainland China and Korea were closed but otherwise Asia mixed: TPX +1.31%, NKY +1.3%, Hang Seng -1.01%, HSCEI -1.21%.
Happy Friday. Let’s get to it…
AKAM: $11.6B Anthropic deal to support Anthropic’s “accelerating CPU workload demands” transforms CIS growth outlook, with potential expansion to ~$20B
Sell side generally positive on the deal, saying Anthropic’s 7-year ~$11.6B commitment is a major validation of AKAM’s cloud infrastructure strategy, with an option for another ~$9B that could take total contract value toward ~$20B. Revenue contribution is minimal in 2026, builds to roughly $150–300M in 2027 and ramps through 2028 toward a ~$1.7B annualized run-rate, materially accelerating CIS growth. The deal requires substantial upfront capex and likely pressures FCF near term, but sell side sees the stronger revenue visibility, premium CPU economics and potential follow-on frontier-lab wins as enough to shift AKAM from a “value” story toward a higher-growth compute asset.
Read-throughs from Claude:
AKAM’s cloud already runs on AMD EPYC. The current top tier is 5th-gen EPYC and the one before it is 3rd-gen. I found no Intel or Arm servers anywhere in their lineup. The dollars are modest for AMD. My rough math is about $1–1.4B of CPUs over 2027–28. NVDA previously flagged Akamai’s Vera deployment plans. Vera targets agentic workloads (code, orchestration, data processing) with high-bandwidth LPDDR5X.
JBL. The 8-K has Jabil holding Akamai’s $1.7B of memory on consignment and buying it back at cost as it uses it. That means Jabil is building the servers. It’s big revenue at thin margins.
Lenovo (992 HK / LNVGY). It signed a new 7-year hardware deal with Akamai on 9/23, likely the second server supplier.
SNPS: HSBC upgrades to Buy/$700, sees business model shift + agentic AI turning Synopsys into an AI beneficiary
HSBC says SNPS is moving toward a licensing-plus-royalty model in Design IP while agentic AI could shift EDA from human-seat subscriptions toward higher-value usage/consumption as agents orchestrate more design work. HSBC sees these changes driving revenue growth to ~15% in FY27 vs. ~11% consensus and lifting the earnings CAGR from ~7% in FY24–26 to ~28% in FY26–28. Upgrades to Buy from Hold and raises PT to a Street-high $700 from $490.
DDOG: Wolfe raises PT to $340, says agentic AI + Muse could drive another leg of observability demand
Wolfe says ecosystem checks show agents materially increasing observability intensity as every tool call, retry and handoff needs to be traced, with traces costing roughly 2x metrics and already driving higher consumption. AI coding tools are also accelerating software-development velocity by ~2–3x, creating more code/services/pipelines for DDOG to monitor, while Wolfe’s initial conversations suggest an increasing likelihood of DDOG becoming directly involved with Meta’s Muse. Wolfe’s upside case now implies ~32% FY25–28 revenue CAGR vs. ~25.5% consensus and sees DDOG as one of the best-positioned ways to play inference/agentic demand.
OpenAI/CBRS:
[
🚨 AI News | TestingCatalog
@testingcatalog
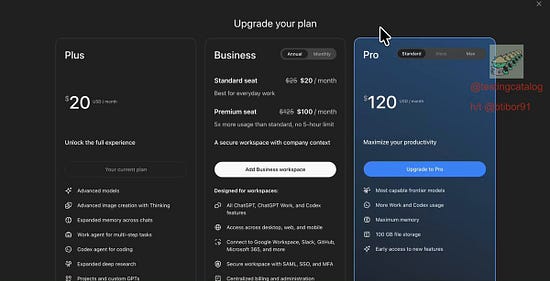
BREAKING 🔥: An upcoming $500 ChatGPT Pro Max plan will likely be powered by @cerebras infrastructure. > So far, "Fastest Work and Codex" are the only changes in the plan description compared to ChatGPT Pro. > Usage limits could still be higher as well 👀 \* The plan price is
🚨 AI News | TestingCatalog @testingcatalog
OPENAI 🔥: The upcoming ChatGPT Pro Max plan will cost $500. So far, this will be one of the most expensive AI subscriptions available on the market. I hope "it will be worth the wait" 👀
11:05 PM · Sep 24, 2026 · 209K Views
70 Replies · 43 Reposts · 1.09K Likes
TWLO: HSBC downgrades to Reduce/$211 after Muse-driven rally, says market is overpricing agentic upside
HSBC agrees consumer agents should drive more calls, messages and authentications, supporting higher communications volumes for TWLO. But after a ~30% rally since Muse launched, HSBC says valuation assumes too much value capture, arguing Meta’s own AI voice stack limits Twilio’s ability to monetize the highest-value parts of each interaction. Downgrades to Reduce from Hold with a $211 PT.
ZS: CRO Mike Rich stes down due to personal reasons and Zscaler promotes Ross Tackett to CRO, effective Oct. 1
ZS named Ross Tackett Chief Revenue Officer, expanding his remit from Head of Worldwide Sales to oversee global sales, revenue operations, strategic partners and GTM execution.
U: Freedom says Meta Horizon Create/Studio selloff looks overdone, competitive impact likely distant
Freedom says Meta’s Horizon Create/Studio announcements hit U disproportionately, but the products remain early and could take significant time to become meaningful competitors. Unity already has its own AI/agentic creation tools and broader capabilities across physics, live ops, acquisition and monetization, while Create/Studio currently look more focused on game creation. Freedom believes both U and RBLX are well positioned to weather Meta competition; reiterates Buy/$48.
SPCX: Mizuho says rising AI compute pricing supports premium monetization as capacity ramps
Mizuho says industry pricing is moving higher, reinforcing confidence that SpaceX can sustain premium compute economics as it adds capacity, with management reiterating a ~$30–50/W 2027 pricing framework near the upper end. A new third-party hosting deal could contribute roughly $1.1B/month at the high end once live, while SPCX retains the option to divert capacity toward Grok, enterprise workloads and Cursor if internal returns are better. Reiterates OP/$200.
[
Elon Musk
@elonmusk
@minchoi Colossus 1 is 150k H100, 50k H200 and 30k GB200. Colossus 2 is 110k GB200 and 440k GB300. Another 220k GB300 will be fully operational next week and another 220k in November. If we get lucky, yet another 220k GB300 by late December.
3:44 AM · Sep 25, 2026 · 942K Views
617 Replies · 708 Reposts · 9.39K Likes
ORCL / OWL / BE : Jupiter lease remains binding as permitting and partner changes complicate buildout – WSJ / FT / Reuters
> WSJ reports Oracle remains bound to its Project Jupiter lease despite unresolved power supply and permitting. Oracle removed land-and-power partner BorderPlex; air permits remain outstanding, and a proposed gas pipeline has twice been rejected over its route through state land. Rent can be deferred for up to three years, but the lease extends to preserve total payments. FT reports Oracle must still cover debt interest and an equity return during delays. WSJ says at least one lender sold project debt below 90 cents on the dollar. Oracle says Jupiter remains on schedule, and Blue Owl says commitments are unchanged.
BE: MS says Project Jupiter force-majeure notice looks precautionary, sees no impact to Bloom economics
MS says ORCL, Blue Owl and Bloom all indicate the 2.4GW Project Jupiter remains on schedule, with Bloom contracted for
- 2GW of fuel cells across 2027–28. MS views the force-majeure notice as contractual protection rather than evidence the
project is slipping, and says Bloom’s contract protects its economics even if deployment timing changes, including the ability to redeploy systems elsewhere. MS leaves estimates unchanged, sees the 1.2GW order worth roughly $1.25B of EBITDA, and reiterates OW/$310.
SPOT: Hearing M-sci saying net adds improved exiting Sept
GOOGL:
[
Pythia Cap: Partially Conductive
@PythiaR
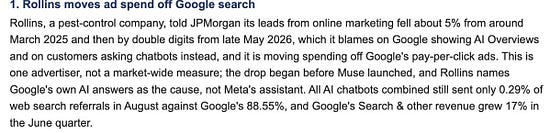
Interesting commentary from $ROL on $GOOG search.
6:34 PM · Sep 24, 2026 · 23.8K Views
9 Replies · 8 Reposts · 128 Likes
CMCSA: KeyBanc downgrades to UW/$18, sees broadband competition + C&P EBITDA pressure worsening
KeyBanc says broadband net adds remain under pressure from FWA/fiber competition, cutting 3Q/4Q and 2026 net-add estimates further below consensus. It also expects Cable & Platforms EBITDA to worsen in 4Q as ARPU/EBITDA improvement fails to offset subscriber pressure, while theme-park weakness adds another headwind. KeyBanc cuts estimates and downgrades CMCSA to Underweight from Sector Weight with an $18 PT.
AAPL: Bernstein sees December-quarter margin downside from sharply higher memory costs; keeps OP/$370
Bernstein’s BOM/mix work points to December-quarter Apple gross margin of ~46.2%, ~50bps below consensus, and EPS of $2.87 vs. $2.92 Street as higher DRAM/NAND costs outweigh premium iPhone mix. International price increases provide some offset, but memory accounts for ~90% of the estimated $168 y/y device-cost increase on a 256GB iPhone 18 Pro Max.
Memory: Memory / Nanya: CXMT expansion raises 2027 commodity-DRAM pricing risk despite HBM shortages – Commercial Times
> A Money Weekly analysis republished by Commercial Times argues memory pricing could diverge in 2027, with HBM remaining tight while CXMT expansion pressures mature DRAM. It says CXMT’s fifth-generation process increases dies per wafer by at least 50%, and estimates the company holds about 15% of global DRAM wafer capacity but 11% of bit output. The analysis estimates roughly 70% direct competitive overlap with Nanya after accounting for customers and qualifications. It also cites Acer chairman Jason Chen’s expectation of lower average memory costs next year.
ERIC/NOK: BNP says RAN outlook is stable overall but mix shifts away from North America; AI-RAN remains too early to call
BNP says Dell’Oro’s 2026–27 RAN outlook is broadly unchanged, but North America has weakened toward the low end of the prior range while China/rest of Asia ex-India improved. Nokia is more exposed to North American MNO capex, so near-term cuts are a headwind, though 2027 should see some recovery as spending normalizes. On AI-RAN, BNP says Ericsson remains more cautious while Nokia is gaining traction with a more aggressive edge-inference approach, but the market is still too early to determine which strategy wins.
META:
[
Dynamicmoats
@DynamicMoats
$META

8:41 AM · Sep 25, 2026 · 614 Views
1 Repost · 3 Likes
AFRM: DB says agentic-commerce fears are premature; QTD trends remain business as usual
DB says AFRM pushed back on concerns that Muse/agentic shopping will pressure BNPL economics, arguing consumers still prioritize access to credit, affordable monthly payments and no late fees, while Muse currently redirects users to merchant sites. QTD volumes, consumer behavior and credit are tracking normally, with Amazon UK live and INTU/ServiceTitan partnerships ramping. Management also highlighted positive early results from its transformer underwriting model and sees selective APR increases/future bank charter as offsets to higher rates; maintains Buy.
TSLA: MS says Semi is an underappreciated autonomy/software opportunity with dramatically better economics than consumer FSD
MS says Tesla Semi could eventually monetize unsupervised FSD at roughly $12–18K/month per truck vs. ~$100/month for consumer FSD, with ~82K autonomous Semis by 2040 implying ~$17B of software revenue and ~$7.5B of incremental EBIT. Autonomous trucking could drive ~2.3x higher utilization and ~20% lower cost/mile, taking annual profit per tractor from ~$31K to ~$189K, or ~6x.
TSLA: Semi rollout brings large orders; pricing and production ramp remain undisclosed – Reuters
Reuters reports Tesla is expanding Semi deliveries from Nevada, with PepsiCo, DHL and US Foods among customers featured at Thursday’s event. Reuters cites a 2,500-truck order from a coalition including Microsoft and PepsiCo, plus a separate 500-truck Einride deal.
TTAN: TD Cowen says Max acceleration remains intact and recent GTV softness looks macro-driven after meetings with VP IR
TD Cowen says after meetings with VP IR Jason Rechel, it came away incrementally confident that recent pressure from GTV softness, Max revenue-recognition dynamics and the CRO transition is not indicative of a fundamental issue. Max adoption continues to ramp, with 3-year deals and a ~3-month revenue lag creating a bigger 4Q/1Q step-up, while new “Mini Max” should broaden adoption beyond the >700 Max customers targeted by year-end. Cowen views 2Q GTV growth of 17% as largely impacted by macro/weather/calendar factors rather than TTAN-specific weakness and reiterates Buy/$100.
NEWS:
OpenAI / Cybersecurity: GPT-6 Cyber preview could arrive at September 29 DevDay – Reuters
> Reuters, citing Fortune, reports OpenAI plans to preview GPT-6 Cyber within days alongside a product intended to help customers deploy the model securely and automatically. The cybersecurity model could be unveiled at the September 29 DevDay event with a dozen or more other products. Fortune says a limited group in OpenAI’s application-only Daybreak Red program already has alpha access. OpenAI did not immediately respond to Reuters, and the launch timing remains reported rather than confirmed.
GDDY / GEN: Gen Digital makes takeover approach for GoDaddy; terms remain undisclosed – FT
> FT reports Norton owner Gen Digital made a takeover offer for GoDaddy in recent weeks, with discussions at an early stage and no certainty of a transaction. A deal would give Gen access to more than 20M small-business and individual customers and roughly 81M domains, approximately one-fifth of registrations globally.
AI models / Jev: TypeSafe pitches low-cost decision model; investors offer $10B-plus valuations – FT
> FT reports TypeSafe AI is receiving investment approaches at valuations of $10B or more after launching Jev, versus its previous $200M valuation. Jev handles classification and routing decisions inside software rather than generating chat responses. FT says Vercel recorded more than twice the first-day paid-developer interest of any prior model launch.
AMZN: Plans $3B Indian quick-commerce investment through 2030 – Reuters
Reuters reports Amazon plans to invest $3B in Indian quick commerce by 2030, including $1B by end-2027, citing two sources. Plans include expanding Amazon Now’s neighborhood warehouses from roughly 750 to 1,300 by April and improving inventory software and demand forecasts. Amazon declined to confirm the spending but said the business exceeded $1B in annualized gross sales.
Optical networking: CPO production ramp expected in 2028–29 as pluggables persist – Commercial Times
Commercial Times cites researcher Lin Wei-chih forecasting limited 1.6T co-packaged optics shipments in late 2026, 3.2T system validation in 2027 and a larger production ramp in 2028–29. He expects pluggable, linear-drive, near-packaged and co-packaged optics to coexist over the next five years. The report puts conventional 1.6T pluggable power consumption at roughly 22–28W, potentially reaching 40–60W at 3.2T. Optical-engine manufacturing, fiber alignment, testing and packaging yields remain constraints.
TikTok / Social media: First US teen-harm trial starts September 28 in Alabama – Reuters
Reuters reports TikTok’s first US trial over alleged harm to teenagers is scheduled to begin September 28 in Alabama and last two to three weeks. The state alleges addictive design and misleading safety claims, seeking penalties and other relief. At least 27 other states and Washington, DC have also sued.
MELI: Tests one-hour delivery in Brazil and begins pharmacy rollout – Reuters
Reuters reports MercadoLibre launched a one-hour delivery test in part of São Paulo, including medications and food, and plans to expand it. Its own São Paulo pharmacy begins prescription sales this month. Third-party pharmacies are scheduled to join its Brazilian marketplace in October, initially through three unnamed chains, with 20 physical drugstore locations expected on the platform by year-end.