2026.09.27 | Substack | AKAM | Gaetano AKAM Thesis & Model
原标题:AKAM: My Newest Position. Let’s Visit the Thesis and Financial Model
Worth a look.
I had barely paid attention to this company before recently.
The reason it caught my attention is that the business could look dramatically different over the next couple years than it does today. I was researching them with all the Muse developments and found them quite boring initially. But then realized they are on the early stages of a major inflection.
Akamai runs a huge global network of computing infrastructure. Historically, a lot of that was used to help companies deliver websites, video and other internet traffic faster.
Today, there are really three pieces that I want you to understand.
Security is the largest business. It generated $604M in Q2, up 10% YoY. Akamai helps companies protect their applications, data and internet traffic. AI should create more demand here as software agents make more requests, access more data and interact with more systems.
Delivery and other cloud applications generated $396M in Q2 and declined 6% YoY. This is the mature piece of the business.
Cloud Infrastructure Services, or CIS, generated only $99M in Q2, but grew 39% YoY. This is Akamai renting computing capacity to customers.
Anthropic just committed $11.6B over seven years to use Akamai’s CPU infrastructure. Revenue starts in the second half of 2027 and should ramp toward roughly $1.7B annually by the end of 2028.
Akamai has other large cloud contracts too. Altogether, management says the major CIS contracts already signed should eventually contribute roughly $2.2B of annual revenue.
That compares with CIS running at only about $400M annualized today.
So the way I see it is that security can continue growing around high single digits to low double digits, delivery can keep shrinking, CIS can potentially go from a small part of Akamai today to one of its largest businesses over the next few years.
AI helps both sides. More AI workloads create demand for Akamai’s compute infrastructure. More agents and machine-to-machine activity create more things that need to be secured.
This is why I took an initial position.
Now let’s look at the financial modeling and where I would be interested in adding more.
This article reflects my personal research, estimates and opinions for educational and informational purposes. It should never be viewed as individualized investment, financial, legal or tax advice, or as a recommendation or solicitation to buy or sell any security. The financial forecasts, valuation ranges, price targets and scenario analysis shown here are my own estimates based on currently available information and assumptions that may prove inaccurate.
TLDR
- I took shares around $117.
- My current 12-month base valuation is around $160/share.
- My 2028 base case is roughly $6.0B of revenue and $8.60 of adjusted EPS.
- Bear / Base / Bull: ~$90 / ~$160 / ~$205-$215.
- The main growth drivers are Security and the CIS ramp.
- The biggest risks are Anthropic concentration, CapEx and CIS margins.
Akamai currently guides to roughly $4.45B-$4.53B of 2026 revenue and $6.40-$7.05 of adjusted EPS.
My 2028 base case is:
Revenue: ~$6.0B Adjusted operating margin: ~26%-27% Adjusted EPS: ~$8.60
Most of the change comes from CIS. The new Anthropic agreement contributes only $150M-$300M in 2027, then ramps through 2028 toward roughly $1.7B of annual revenue by year-end.
The economics are better than I initially expected too. Management says its large CIS contracts generally produce cash gross margins in the mid-60s to mid-70s and operating margins in roughly the 20%-30% range once deployed.
At a $1.7B Anthropic run rate, a 27% operating margin would imply roughly $460M of annual operating profit.
The tradeoff is the upfront spending. Akamai expects roughly $5.5B of CapEx to support the new Anthropic commitment through 2028, so a lot of the spending arrives before the revenue. There is some dilution layered into this as well. Anthropic received warrants tied to the agreement, and Akamai has paused buybacks while it funds the cloud build. I already account for a higher diluted share count in my base valuation.
For valuation, I use 18.5× 2028 adjusted EPS:
$8.60 × 18.5 = ~$159/share
My bear case is around $90, with slower CIS deployment and weaker margins.
My bull case is around $205-$215, with stronger cloud execution, continued Security growth and additional large AI infrastructure wins.
I leave the additional $9B Anthropic expansion opportunity outside my base case.
It’s pretty crazy to me that the market basically rountripped the entire Anthrophic deal.
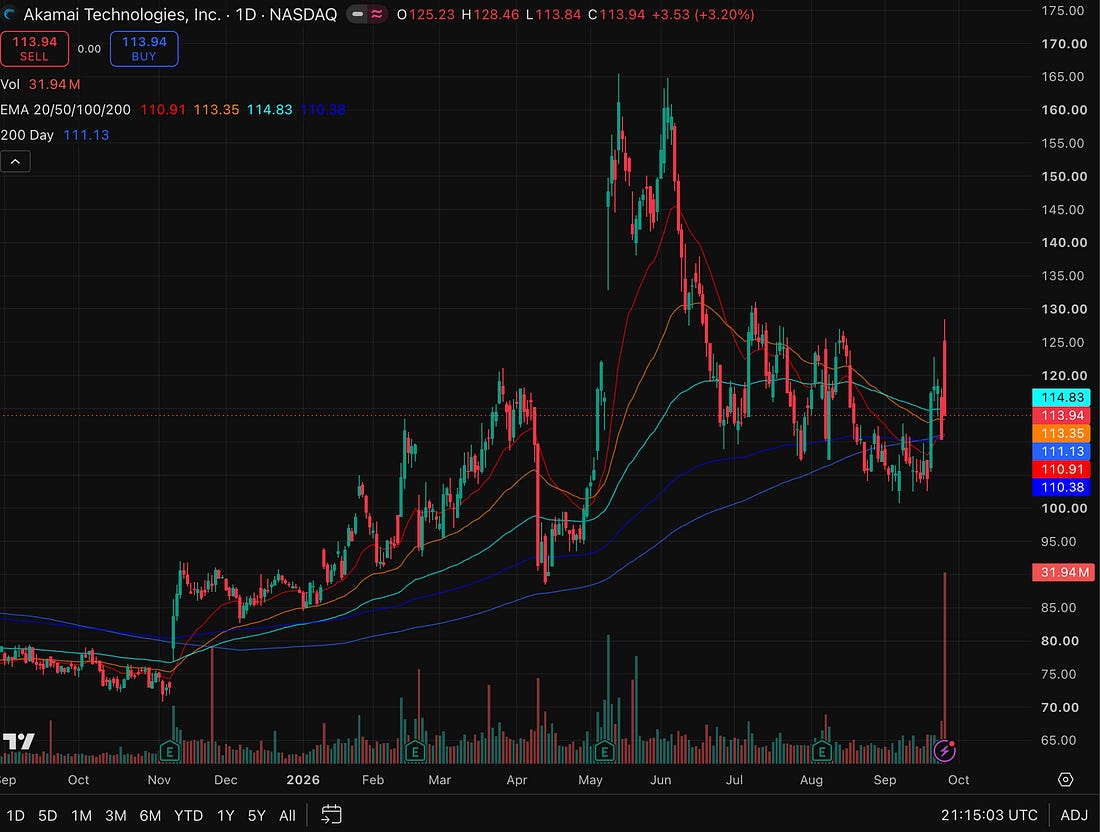
But it did, so I need to respect that. Dilution, customer concentration, Capex. Lots of things for the market to work through.
Right now the 200EMA is at $110.4 and the 200D is at $111.13. I intend to add to my position either overnight or tomorrow anywhere around these levels. I have been conservative with my adds lately, and while I don’t love how heavy the stock was on Friday, I am comfortable owning shares here with a multi-year investment time frame.
I would think that ~$110 area to hold for now, unless macro is really rough. But I am investing here with the mindset that that ~$90 level is definitely possible while this all plays out.
Disclosure: I currently own shares of Akamai Technologies (AKAM) at an average cost of approximately $117 per share. My position, average cost, portfolio weighting and views may change at any time based on new information, market conditions, valuation or portfolio management decisions, and I may buy or sell shares without providing an update.
This article reflects my personal research, estimates and opinions for educational and informational purposes. It should never be viewed as individualized investment, financial, legal or tax advice, or as a recommendation or solicitation to buy or sell any security. The financial forecasts, valuation ranges, price targets and scenario analysis shown here are my own estimates based on currently available information and assumptions that may prove inaccurate.
Investing involves substantial risk, including the potential loss of principal. Akamai faces execution, customer-concentration, capital-intensity, financing, cybersecurity, competitive and dilution risks. Readers should conduct their own due diligence and consider their own financial situation, objectives and risk tolerance before making any investment decision.