2026.09.28 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
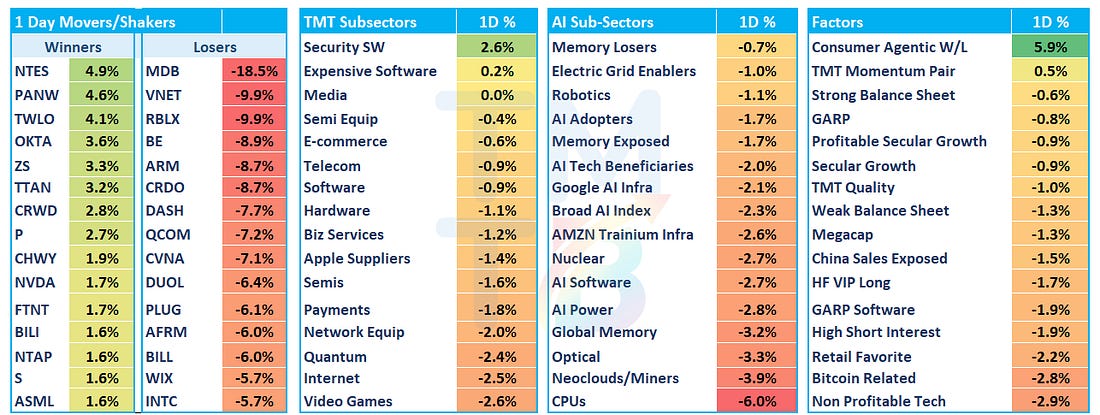
Good afternoon. QQQs -1.1% in a risk-off start to the week, with most of the damage done in the first hour (QQQs -1.7% at the lows around 10:45am) before an Iran headline mid-afternoon helped claw some back. Semis -1.7% led lower (-3.6% at the lows) as the CPU (AMD -3.5%/INTC -5.5%/ARM -8%) & META (-5%) Muse trade unwound hard as the Muse hype cycle reached the point where investors began to dig into the numbers rather than just narratives and rocket emojis. At some point in every hype cycle, even Tech investors decide to open Excel.
On CPUs, this Freda Duan X post was making the rounds, concluding the sandbox layer is much smaller than many expected: serving 100M Muse DAU takes ~1 GW in her base case, but only ~0.1 GW of that is the CPU/VM layer (sub-$1B of CPU content, or ~65K 192-core CPUs, plus ~$2B of DRAM). In other words: 100M DAU is under 1% of a year’s CPU supply. So, slightly less than the ‘buy every CPU on Earth’ the tape implied the last couple weeks (ah, simpler times!). Bull case pushback is bigger picture: a big TAM (and sentiment) expansion rather than units as standalone agentic racks are ~46% of a ~$200-220B+ 2030 server CPU TAM (vs. $30-40B a year today) at ~2x traditional ASPs.
Re: META, concerns over a potential OAI competing product coming out at Dev Day and also questions around how much consumer shopping habits will actually change hit the stock. Stock was also hovering around 15% to 25x FY27 $36 = $900 (the broad consensus on both multiple and EPS), so seems like a logical spot to digest the recent rally, especially given Muse is unlikely to monetize in any meaningful way until ‘28, either on a subscription, ad, or commission cut basis (although Instinct CEO threw out some interesting numbers today in the ILTB pod, saying 50% of Instinct’s transaction volume is travel and they are already doing $1B+ a year in total volume). We wrote about this whole turn in the CPU/Muse hype cycle in more depth in our weekly yesterday (paywall opened in case you’re interested).
NVDA was the standout +1.7% in semis after announced $150B buyback on top of their existing authorization. Software -55bps held in far better than the headline of the day would suggest (META going after enterprise AI with MDB’s -18% CEO) as cyber ripped and offset the hit to app software (NOW -3%; CRM -3%; MSFT -1.3% TEAM/HUBS/MNDY -5%). CJ left effective immediately after less than 11 months, Dev Ittycheria is returning as interim CEO, and MDB reaffirmed guidance, the day before its investor day. As we said in TMTB Slack this morning, CJ is probably one of the most highly regarded enterprise execs in tech, and it’s hard to see what they can say tomorrow to reassure. Investors were looking for a 3-5pt raise to the long-term Atlas growth target (now >20%) going into the event; that’s a tough ask for an interim CEO. FUNDA called it “a major blow” given CJ was driving the GTM revamp that “was just starting to bear fruit.” Not everyone thinks he’s worth that much: Ummera: “I think CJ’s impact on MDB has been overrated. Hopping to prestige positions like a pod PM” while the news also brought the bears back out, arguing the departure confirms MDB isn’t a real AI beneficiary; Postgres is. Here’s his departure note on LinkedIn:

Favorite take of the day in TMTB Slack:

TMTB Slack
Just another quiet Monday in Tech.
Back to the tape. Macro didn’t help things. The long end sold off again, 10Y +7bps to ~5.25% (still the highest since 2007) with the 2Y +7bps to ~4.93%, and Fed Governor Cook added fuel: she expects “continued pressure on inflation from the AI buildout… and from the pass-through of higher oil prices,” and the “labor market appears to be well positioned to handle an increase in rates.” The market has ~70% odds of a 25bp hike on 10/28, ~40-50bps of hikes for the rest of the year and ~100bps cumulative through Dec ‘27. Oilround-tripped finishing flat: up as much as ~4.5% after Trump rejected Iran’s proposal to reopen Hormuz, then faded as Saudi restored East-West pipeline flows and Axios reported ~2:20pm that Trump is open to sanctions relief for concrete nuclear steps. BTC -2% to ~$83K.
Ok, let’s get to the good stuff…
AI/SEMIS
Big Day tomorrow for OAI:

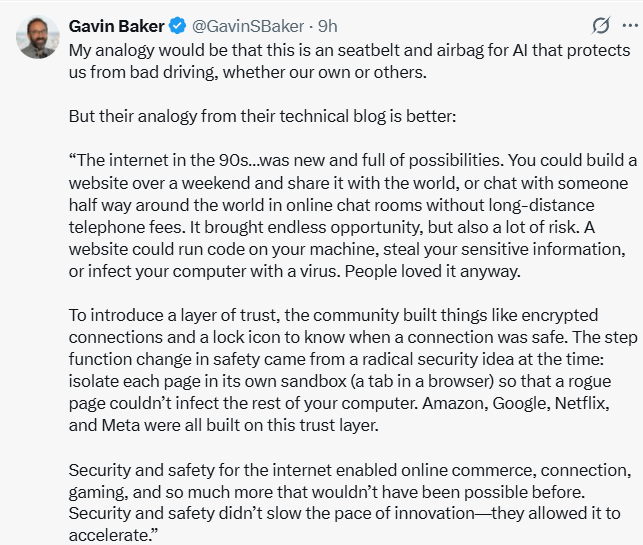
- NVDA +1.7% after adding $150B to its buyback (to $235B, the largest-ever US authorization), launching an Open Agent Safety Platform on a day AI-agent breaches were in the headlines, and The Information reported China is weighing approvals for BABA/ByteDance to buy the RTX Pro 5500 (ByteDance eyeing ~1M units. In our weekly yesterday we wrote we thought MSFT would get the Megacap bid given META digestion, and muddied GOOGL/AMZN narrative, but given the META enterprise push, looks like NVDA took the reins. Here’s Gavin on NVDA’s safety push (I liked the framing)
- AVGO -1%: popular funding short outperforming in today’s unwindy day
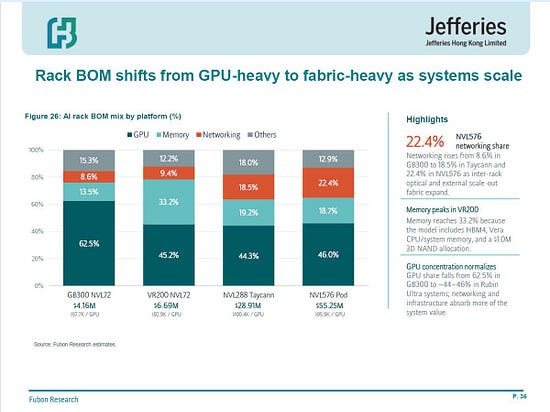
- Optical weaker: CRDO -8.7% givving back all of Friday’s gains; COHR -4.5%; ALAB -3.6%; CIEN -3.6%; GLW -3.3%; LITE -2.2%. COHR/LITE flipped from green early to -6.8%/-6.4% at the lows despite Citi raising its LITE PT to $1,400 (OCS an ~$11B merchant TAM by 2030) and a JPM fireside where COHR said supply, not demand, is the binding constraint. Part of it is the ECOC hangover: the pushback we’re hearing from some investors is that COHR’s PhotonLink was product consolidation rather than the new services layer some hoped for, so a bigger setup meant a bigger letdown. On CRDO, the investor debate is whether the soft back-half AEC guide is mechanical (timing, 1.6T visibility) rather than lower attach. This chart from Jefferies being passed around on networking/optics increasing BOM as NVDA’s fabric-heavy systems scale:
[
Sami
@Sam67024298780
I repeat: Value is shifting from DRAM to OPTICS.
Sami @Sam67024298780
Long $LITE, Short $MU $NVDA is accelerating upgrading NVLink to pool more HBM together to reduce HBM contents per GPU to defend expensive memory costs, so value is shifting from DRAM to optics.
2:56 PM · Sep 26, 2026 · 296K Views
27 Replies · 99 Reposts · 824 Likes
- BE -8.9% gave back Friday's +8% with no news. The Jupiter force majeure overhang isn't going anywhere, and K on TMTB Slack noted the NM regulator rules on ORCL's power permit in November: "Clearly a significant delay is priced into the stock." High-beta power came in with it: PLUG -6.1%; VRT -3.6% despite Bernstein's five hyperscaler checks calling quality concerns overblown
- Memory de-risked into MU on Wednesday: SKHY -5%; SNDK -3.7%; MU -2.6%. SKHY on Bloomberg’s report that Solidigm is weighing a US IPO as soon as 2027 at up to $100B. Sell-side out with bullish MU previews (JPM sees the DRAM/HBM shortage through CY27-28); investors are focused on FY27 margin durability as LTAs get layered on. HDDs bounced hard off the lows: STX +51bps (from -5.1%); WDC -78bps (from -5.4%)
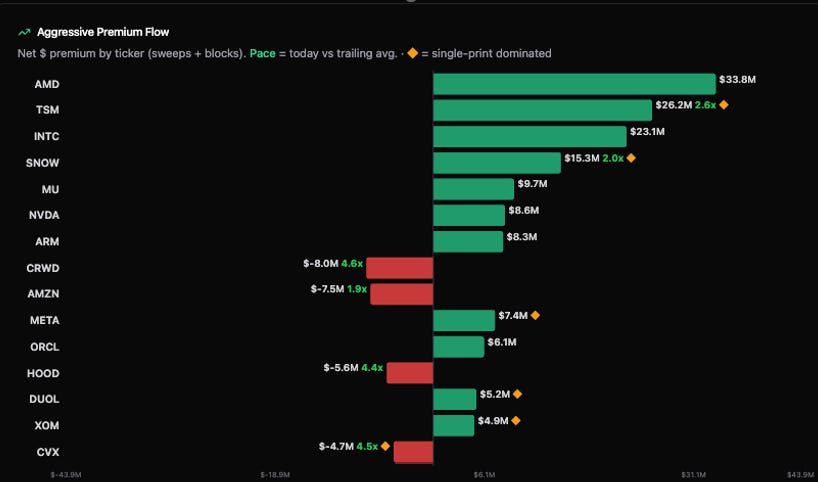
- CPUs: Not much else to say other than the above in the intro and what we wrote in our weekly. H-cap in TMTB Slack flagged a CPU bid in the options market despite the weakness:
- Post-close, AMD -4% agreed to buy Fei-Fei Li’s World Labs AI startup (Physical AI) for $8.2B
- ASML +1.6%; TSM +50bps acted well. UBS named ASML a top pick into Q3 (€2,350), seeing January's backlog update and an above-consensus FY27 guide as the catalyst, and raised its TSM 2027/28 capex forecasts to $90B/$105B from $80B/$95B
- MRVL -3.8% fell despite bullish investor-day previews: RBC expects the GOOGL custom-silicon opportunity to rise at least $2B from the $10B+ framework; UBS went to $335 from $310 on 350K Maia units in 2027.
- CBRS -4.8% fell with AI beta despite a Reuters report it will supply AI systems to cloud startup Gimlet Labs.
- P +2.7% kept going after last week's analyst day; ), NTAP +1.6% in sympathy
- APH +63bps on an edge check: VR Ultra doubles backplane density.
- AI hosting/miners: IREN -5.5%; GLXY -4.2%; HUT -4.2%; WULF -3.9% with BTC -2% and yields at highs, despite Jones initiations (HUT Buy/$130; WULF Buy/$30; IREN Hold, noting only MSFT is investment grade among its customers)
INTERNET
- META -5%: In addition to what we wrote above, Moffett Nathanson was out also questioning how big agentic commerce would be: it estimates only ~11 monthly purchases per average consumer are realistically agent-addressable, sees grocery/travel as difficult to automate given habitual behavior, choice and trust, and notes AI referrals still represent <1% of ecommerce traffic. The firm sees household administration/calendar management as Muse’s strongest consumer use case, but expects monetization to come primarily through incremental engagement/ad impressions rather than large commissions or subscription revenue.
- DASH -6%: didn’t hear much here other than some chatter being passed around of fears CEO Tony Xu leaving to go to META.
- DUOL -6.4%: no news; AI-disruption fears remain the overhang heading into OAI’s Dev day, and the CEO sold ~$6.2M under his plan last week.
- RBLX -9.8%: Jefferies downgraded to Underperform modeling FY27 bookings +5% vs. Street 13% saying viral cohorts churn and the new algorithm prioritizes retention. JPM also out neg peak CCUs -4% w/w to 27.7M, though September’s y/y decline improved to -12% from -25%. Hedgeye had a call after analyst upgraded to a long, although we haven’t gone through it. We want to get more positive here, but data just not showing us enough right now (Steal and Egg is decel’ing) and this continues to be a data-drive stock first and foremost. U -4.1% in sympathy, still digesting META’s Horizon Create/Studio.
- JPM published a “U.S. Consumer Agentic AI Vulnerable” basket (22 names living off consumer inertia, search friction or control of traffic). Names circulating on X included CVNA -7%; WIX -5.7%; AFRM -6%; UPST -3.3%; XYZ -4%; RDDT -4.5%; Z -3.5%, and rates didn’t help the fintechs (SOFI -3.9%). On CVNA -7%, MS argued the opposite: best positioned as agents enter car buying.
- China split: NTES +4.9% as MS named it Top Pick ahead of Ananta’s 1/15/27 global launch, while China AI infra sold (VNET -9.9%; GDS -3.4%), with CSI 300 telecom services -6%+ on fears of new US limits on AI components.
SOFTWARE
- Cyber ripped off the open: PANW +4.6%; OKTA +3.6%; ZS +3.3%; CRWD +2.8%; S +1.6%; FTNT +1.7%; NET +1.5%. No bid pre-market despite a weekend of AI-agent breach headlines, but NVDA named CRWD and PANW as security partners on its agent safety platform. OKTA got post-Oktane PT raises and BTIG had positive checks onPANW ). Basket shaking off fears that OpenAI will claim cyber as their own TAM at Dev Day tomorrow.
- TWLO +4% gaining back some of Friday’s 10% drawdown, driven by an HSBC downgrade where the analyst got his Math all wrong.
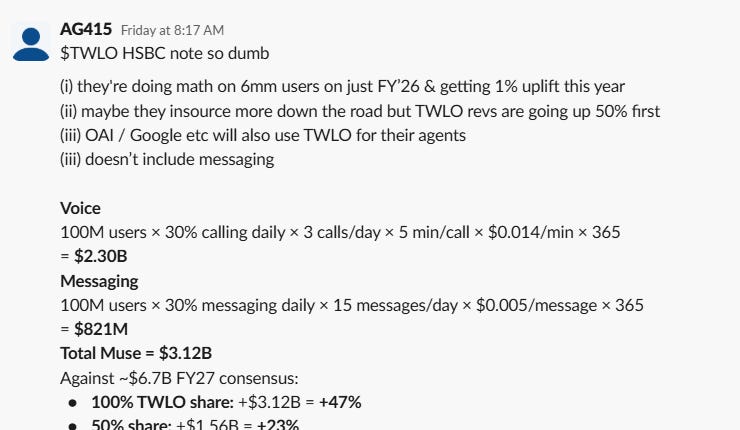

Wolfe was also out today raising its PT to $350 from $290 on the personal-agent thesis: agent-placed voice calls possible by 4Q with no domestic carrier alternative, plus Stytch-based agentic authorization worth $85-170M of incremental revenue.
- SNOW -2.3% recovered most of a -5.7% drop after a $3.5B 0% convert and losing its SVP of Sales for the Americas to OpenAI.
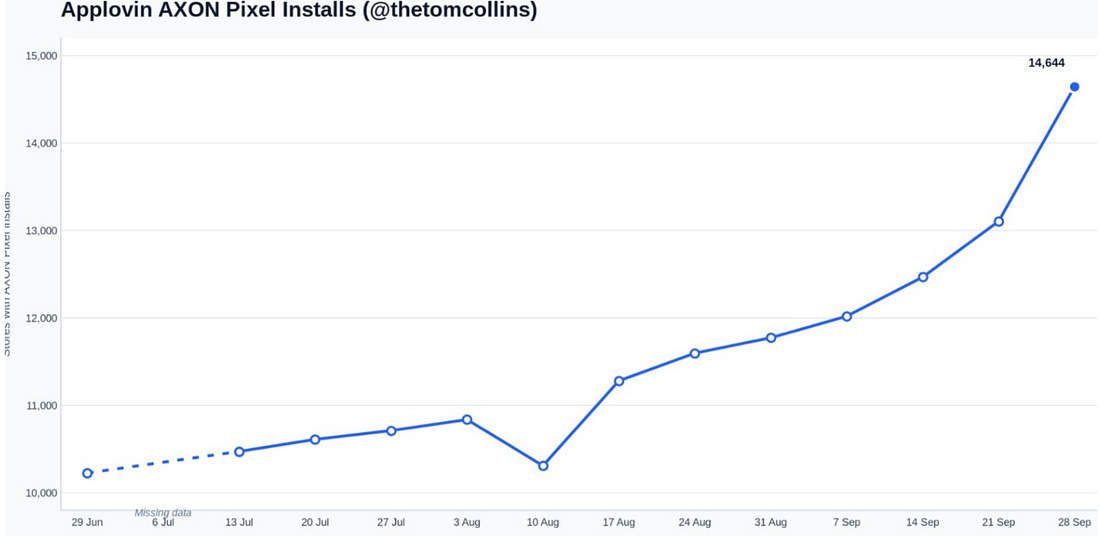
- APP -81bps faded from +3.6% at the open (3p data on X and Citi had AXON pixel installs +11.7% w/w). An ad-budget check we heard was less constructive: APP spend tracking +17.6% vs. 18.5% expected, with the e-commerce click-out one that “just doesn’t work.”
- · PATH -2.2%: D.A. Davidson downgraded to Underperform (PT $10 from $16) on rising customer resistance to AI pricing as cheaper agent alternatives emerge; sees 4Q ARR risk.
- ORCL -3.3% (-4% at the lows) stayed heavy as the OpenAI headlines piled up: the training pause, Florida asking a court to bar it from developing new models, and SoftBank pricing a record $11.1B junk bond to refinance its $40B OpenAI bridge loan.
ELSEWHERE
- TSLA -3.9% into Q3 deliveries this week: JPM cut its 3Q number to 482K from 516K and its PT to $415 from $445; Cantor is at 421,758 vs. ~448.7K consensus. Roadster reveal 10/1. RIVN -4.4%; LCID -4.2% in sympathy.
- Solar sold with yields: RUN -5.5%; ENPH -4.6%; FSLR -2.7%, FSLR fading from green after KeyBanc’s valuation upgrade to Sector Weight (AMC credits plus cash ~$135/share; still ~2 years of US inventory).
- COIN -1.7% faded from +1.9% with BTC despite KBW initiating at Outperform
BULLISH AND BEARISH WEEKLY OPTION FLOW

Source: RunningoftheBulltards