2026.09.29 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
Good afternoon. QQQs +19bps in a choppy session: +55bps at the open, flat by late morning with the 30Y pushing through 5.6%, and modestly green into the close. Semis +1.2% led the way higher, though well off the +2.4% highs from just before 11am, with semicap (AMAT +5.2%; KLAC +3.9%; ASML +3.6%; LRCX +3%) bid on the TSM Texas report and optical (LITE +5.7%; GLW +4.7%; COHR +3.5%) bouncing off Monday’s ECOC hangover. Software -20bps lagged for a second day as app software (MNDY -3.8%; HUBS -2.5%; ADSK -1.9%; TEAM -1.4%) made its lows mid-keynote at an OpenAI Dev Day where the main focus was selling agents into the enterprise, while consumer internet names hit on Monday bounced (DUOL +6.2%; CVNA +5.2%; DASH +4.9%).
Macro didn’t help. The Conference Board’s September confidence print was ugly (81.9 vs. ~89 expected, the lowest since April 2014, with respondents citing fuel costs and jobs), and the curve bear-steepened: 2Y -3bps to 4.89% on the data while the long end kept selling off, with the 10Y +2bps to 5.26% (+30bps in a week) and the 30Y +3bps to 5.59% for the first time since 2002. NY Fed’s Williams said at 2pm that “one further upward adjustment of the federal funds target range may be appropriate late this year,” with no urgency after the September hike; the market still has ~70% odds of a 25bp hike on 10/28, ~40-50bps of hikes for the rest of the year and ~100bps cumulative through next September. Crude -3.6% to ~$89 as Saudi Red Sea exports recovered, Gulf flows got back above 90% of pre-war levels and DOE offered a 40M-barrel SPR exchange. BTC flat at ~$83.5K.
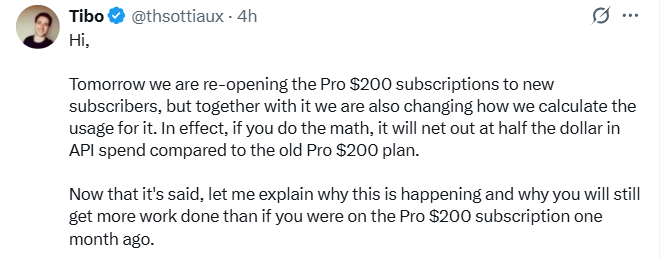
OpenAI was in focus all day, even before Dev Day. First Tibo was on X saying they are lowering usage on the $200 Pro Plan:
Then, Axios reported around 10:15am that OpenAI’s annualized revenue run rate is up more than 70% since the start of 3Q to almost $70B, with B2B revenue more than doubling over the same period and more consumer revenue added in 3Q than in all of 2025. Compare that with the last number given to the media ($40B on 8/13) and Yipit’s ~$43B (9/17). RI and PHC dug into the math for us in TMTB Slack:
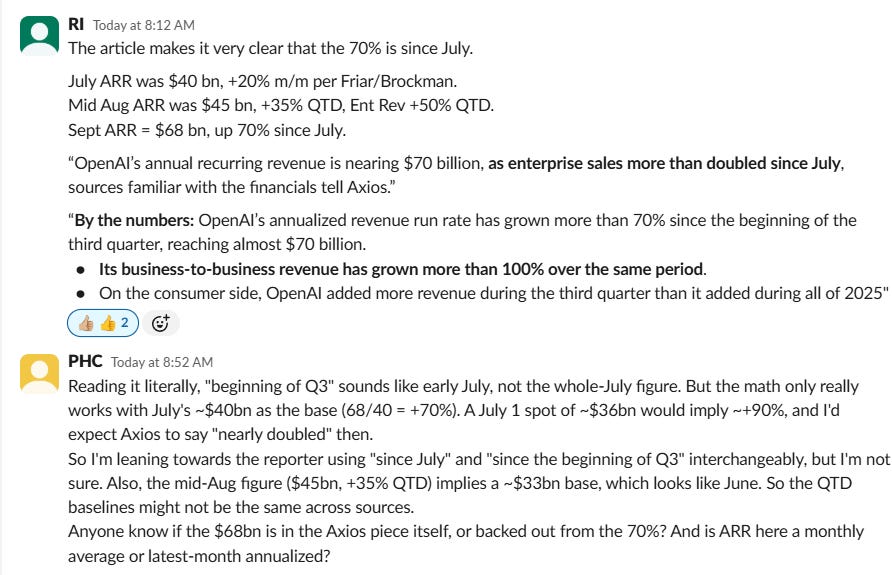
Open AI related names ripped on the news: ORCL +4% went from +1% to +8.4% in about 30 minutes, BE +10.8% touched +15% (although was helped by a bullish MS note as well), and the neoclouds and semis peaked right after.
Second, Dev Day. Less ‘AGI has arrived,’ more ‘please contact your enterprise sales rep.’ The headliner was Dots: always-on agents with their own cloud computer and browser and 4,000+ app connectors, pitched squarely at work and bundled with paid plans (plus a new $500/month tier with 25x the usage capacity of the standard ChatGPT Plus plan and Ultrafast tier up to ~8x faster at ~6x the price). Also: ChatGPT Space, where people and agents co-edit docs, sheets and decks and assign each other tasks; GPT-6.1 Sol at a fifth of Astra’s price; an Ultrafast tier and an enterprise Marketplace where customers can spend their OpenAI commitments with 32 partners (NOW, CRM, HUBS, PANW, CRWD, ADBE, FIG among them). No consumer agent to take on Muse as it seems OAI has ceded the space to META +3.3%, which bottomed at 1:05pm as the keynote started & rallied into the close.
Third, at 1:40pm Bloomberg reported OpenAI is targeting at least $30B at a ~$1.4T valuation after pushing back its IPO, a bridge round in place of an IPO as it focuses on AI-safety concerns; Altman told Bloomberg investors are patient on the IPO timeline.
Outside of that, big Tech dinner at the White House today where Trump said “whoever wins superintelligence wins” and floated renaming AI “Super Intelligence.”
Let’s get to the good stuff…

AI/SEMIS
- Semicap (AMAT +5.2%; KLAC +3.9%; ASML +3.6%; LRCX +3%) bid all day on EDN’s report that TSM is weighing a second US campus of six advanced-node fabs, with Dallas the leading candidate and investment potentially above the $265B committed to Arizona (not yet board-approved). Wells Fargo called it incremental for semicap, and memory capex helped: CXMT approved $5.2B for DRAM R&D and testing, and Samsung sees HBM eating nearly 30% of industry DRAM wafer capacity in 2027, up from ~20%.
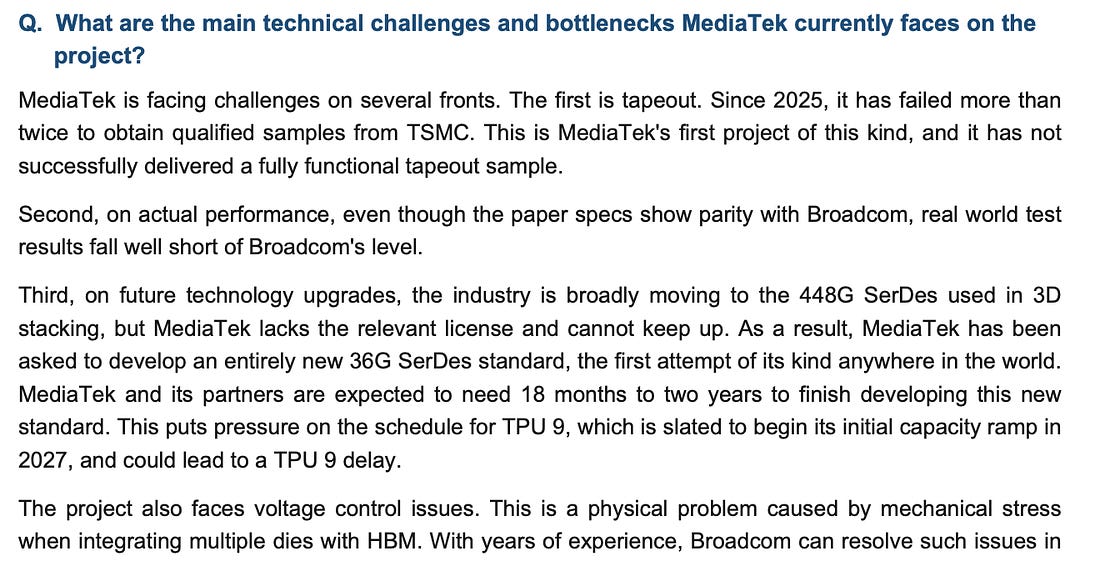
- MRVL +4.5% as MediaTek fell 7.1% in Taipei on rumors that GOOGL’s TPU v9 (HBM4E) work could shift to MRVL; MediaTek called the order-loss claims false. Investor day is next Tuesday (10/6), where Jefferies expects a $40B+ FY30 revenue target (~$22B custom, ~$15B optics), with MSFT’s Maia ramp the swing factor. The Mediatek piece in question was from a now deleted substack post, but the relevant piece was passed along by Jukan in TMTB Slack:
- AVGO +1.6% shrugged off 3p chatter that TSM trimmed its CoWoS allocation to the mid-200s from the high-200s (TPU 8i/SunFish ramp pushed out, META volume uncertainty); the S-1’s $161.2B of AVGO-related leases is the more important number I heard investors focused on today.
- BE +10.8% more than made back Monday’s no-news -8.9% (the Jupiter force-majeure overhang), touching +15% right after the OpenAI headline. MS was bullish this morning saying the new 158K sq ft Fremont facility could eventually double capacity toward ~10GW, supply-chain checks point to 5-6GW of production by YE27 and 8GW+ in 2028 (vs. MS’s 1.8GW/3GW shipment estimates), and Ameren Missouri is recommending 500MW of fuel cells through 2030 (BE’s first meaningful regulated-utility deal). Stock continues to act well as one of few ways to play BTM as fuel cells are easier to permit with voter opposition to data centers and big power supply gap in ‘27/’28 has investors focused on any beneficiaries. Bulls focused on October, which is effectively the deadline to sign for power by end-2027.
- Neoclouds spiked with the OpenAI headline and faded: NBIS +2.4% (+6.5% at 10:25am), CRWV +1% (+6.4%) and CBRS -91bps (+8.8% at 10:45am, round-tripped after Dev Day even thought most read the Ultrafast as a Cerebras win).
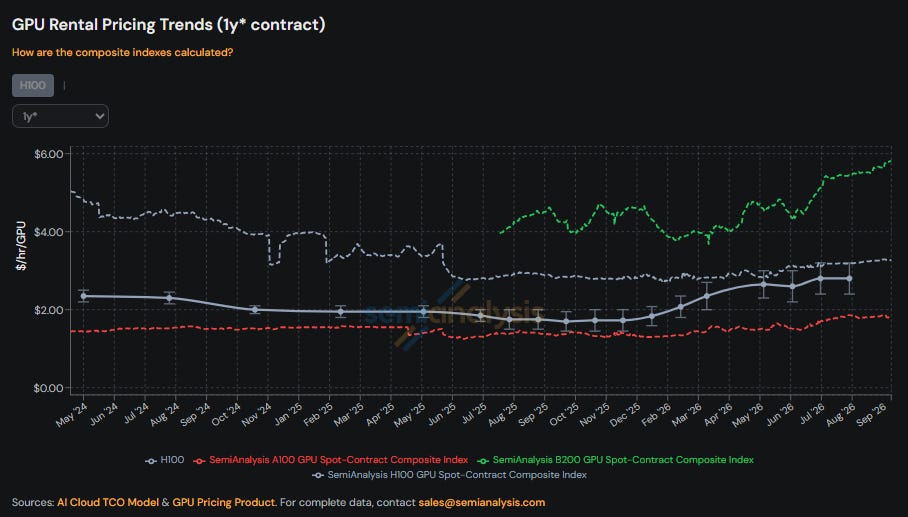
- GPU Pricing: B200 continues to increase
 Source: SemianalysisMemory into MU’s print tomorrow: SKHY +2.6%; MU +1.1%; SNDK +98bps, with HDDs lagging (STX -87bps; WDC +6bps). TrendForce was out saying 2027 HBM prices +121% as HBM4 ramps, while Bernstein otu saying conventional shortages through 2027 but trimmed 2027 HBM pricing as Samsung gains share, with 2028 the normalization year (supplier GMs from ~90% peaks toward the high-70s exiting ‘28). ISI was out saying SNDK is the biggest beneficiary from long-running agents as KV Cache and suspended agent state spills into flash. Other names they mentioned: WDC/STX benefits from logs/traces, P/NTAP from enterprise context storage, and DELL/HPE from higher CPU/DRAM/NAND content. Networking/connectivity names including ANET/CSCO, CIEN/LITE and APH/TEL should also benefit as disaggregated inference drives more east-west traffic.
- NVDA -72bps remains the laggard: as Akh flagged in TMTB Slack, it’s +3.3% over the past month vs. AMD +29.7%, MU +11.7% and TSM +10.6%, although Arun gave some good context

- SPCX +2.6% as the sell-side cheered Monday’s Starship flight (orbit for the first time, 26 V3 Starlink satellites deployed), plus the Anthropic disclosure: up to $84.5B through 2029 is nearly double the ~$45B SPCX had disclosed, though it’s cancellable on 90 days’ notice. UBS sees 3Q revenue of $13.8B (7% above the Street) with the AI segment at $7.6B, against ~$13.2B of cash burn on $19.3B of capex.
- CPU names split: ARM +3.6% and INTC/AMD flat
- Some good debate in TMTB Slack herearound FUNDA’s morning piece saying distillation will get harder. FUNDA argued the recent narrowing between open-weight and frontier proprietary models is unlikely to last as OpenAI/Anthropic/Google increasingly hide raw reasoning traces, making cheap distillation materially harder. Open-weight labs will need more in-house RL, synthetic data and training environments, pushing them toward greater compute spend; FUNDA expects the model gap to widen back to roughly 6–12 months. In TMTB Slack, we officially reached the part of the AI cycle where HF PMs argue about RLVR over lunch. ALC fundamentally disagreed, arguing "China's biggest limitation is compute, not distillation." In ALC's view, the game is now post-training RL, where there's no clear path to distilling a bigger model, and China's large and growing labeled-data ecosystem better explains the recent catch-up. - atl42 countered that the compute gap is exactly why the China labs distill in the first place. Frontier labs are getting very good at hiding chain-of-thought, and those traces are what made RL affordable. Without them, China labs start RL from a weaker base and need more rollouts and compute they don't have, and final-answer distillation alone won't cut it for reasoning and enterprise work. - Arun Dhar landed in between: hidden traces make distillation roughly 10x more expensive, but off a negligible base. He added that RLVR is cheap, reconstruction attacks have gotten much better and the frontier labs distill each other anyway, so "distillation is a bigger problem for investors than it is in SV." atl42 and Arun ended up roughly agreeing the effect is marginal (fewer gradients, a lower RL starting point). atl42 argues those margins compound into a wider lead, especially with enterprises barely using the China labs as is, while ALC says time will tell whether the frontier really pulls away.
INTERNET
- META +3.3% bounced off Monday’s -5%, which was partly about fears of an OpenAI Muse rival at Dev Day although we thought it was just also sensible digestion after stock got RDDT +1.6% shrugged it off), and BofA/Citi were positive on the new Enterprise Platform.
- NFLX +1.5% as DB upgraded to Buy, arguing the market is too focused on softer US engagement: rest-of-world minutes grew 5.4% in 1H26 vs. US minutes -8.6%, at ~18x 2027 EPS.
- DUOL +6.2% made back most of Monday’s -6.4% as Dev Day had nothing aimed at language learning, and DA Davidson’s tracking of >170K users showed choppy weekly DAUs through most of September but the fastest week-over-week growth of the quarter in the final week.
- SHOP +3% as more agentic plumbing landed on the bulls side: WebMCP now covers checkout (agents can read, update and complete checkout, including Shop Pay, with buyer authorization), and MS argued SHOP monetizes the transaction rather than the impression, so it doesn’t care whether demand starts in Muse, Copilot or Gemini.
- DASH +4.9% recovered most of Monday’s drop- Monday’s JPM “agentic vulnerable” basket bounced as well: CVNA +5.2% as Jefferies’ web scrape has September retail units +40% y/y through three weeks, implying ~39% 3Q growth and ~5% upside to the Street; AFRM +3.1% as GS argued agents surface financing options at checkout more efficiently, making BNPL a beneficiary.
SOFTWARE
- ORCL +4% was the purest expression of the OpenAI headline, +1% to +8.4% between 10:05 and 10:35am before giving back about half. D.A. Davidson puts OpenAI at around half of ORCL's compute backlog, so a ~$70B run rate goes a decent way to making investors feel more comfortable, although not even the bulls here have confidence in stock acting better:

- MNDY -3.8% (-7.5% at the lows mid-keynote) as JPM downgraded to Neutral: partner checks point to lengthening SMB/mid-market sales cycles and weaker funnel creation, NDR is slipping to 109%, and AI products were ~17% of 2Q net-new ARR but still TEAM -1.4% (-5.9% at 1:25pm) traded the same way.
- HUBS -2.5% got no help from being named an OpenAI Marketplace partner (neither did NOW -1.1%; FIG +2.3% was the standout partner). M-sci data this morning was mixed: registrations better and SMB demand healthy, but enterprise CMS negative and Marketing net adds muted.
- U -35bps/app-84bps: Digiday was out detailing APP’s recent lawsuit vs. Unity to temporarily restrict rival Unity from collecting and using certain data generated through its mobile advertising business. AppLovin alleges Unity’s Ad Quality SDK has improperly collected data relating to advertisements served by AppLovin, including information about creatives, users and devices, impression revenue and engagemen...Lots of investor questions around what continues to plague U despite the positive checks. The META game announcements/world model releases/OAI Dev Day have been an overhang on what is somewhat of a HF hotel. Our sense is it should begin to start to act better heading into the Q now that those headline risks behind them.
- MDB +75bps went nowhere (-4% to +4%) after their investor day. Nothing like losing your CEO to META the day before Investor Day to loosen up the room:
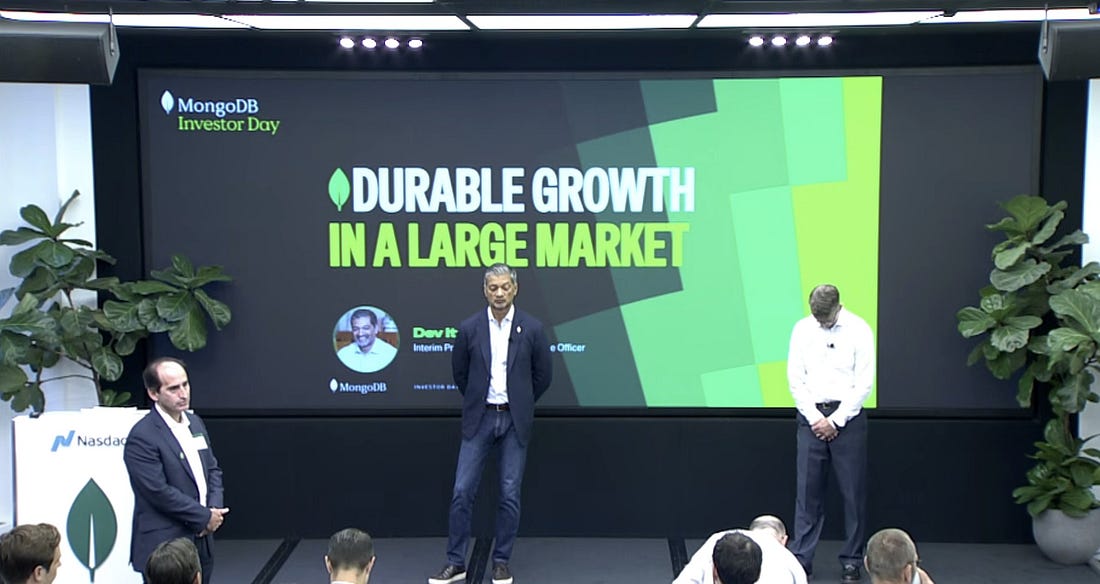 Still, new mgmt delivered roughly what the bulls asked for: a new 3-year model with total growth of 20%+ (from high-teens), Atlas mid-20s (from 20%+, the top end of what investors wanted), EA/other ARR 10%+, GAAP profitability from FY27, “pretty close to Rule of 50” by the end of the period and another $1B buyback. AI natives are 3-5% of Atlas revenue, growing 165% y/y. Pushback from investors was the new Atlas target is still below the ~27% Atlas growth in the FY27 guide, and bulls were hoping for more of a squeeze given how short people are.MDB’s updated long-term targets:

ELSEWHERE
- HPE -1.8% into tomorrow’s networking investor day: JPM expects a raised 3-year networking CAGR (vs. 5-7% prior) on AI DC switching growing 25%+ and sees Helios as a $5-10B opportunity, though HPE has just ~5% AI DC switch share vs. ANET’s 26%.
- AAPL -2.7% was weak from the open and ground lower: DigiTimes reported Foxconn’s foldable iPhone Duo assembly yields were just above 60% as of 9/17 (preorders 10/16), BofA argued agents like Muse raise the risk AAPL loses the iPhone “intent layer” (Siri still lacks persistent background tasks, broad third-party actions and an agent payment rail), and Bloomberg reported new CEO John Ternus is overhauling the company to run faster and leaner, including cuts to hardware program managers.
- DKNG -7.4% to a new 52-week low as the prediction-market overhang kept building: House Oversight widened its insider-trading probe with letters to prediction-market CEOs (CNBC, ~10am), posts on X flagged a CFTC crackdown on prediction-market incentive programs (~11am), and Kalshi is reportedly in talks to raise ~$1B (~1:25pm). Stifel’s handle data (OSB ex-predictions +15% y/y in the first two NFL weeks on lower promo) didn’t matter.
- FICO -26.5% (not on our screen, but hard to ignore) after FHFA Director Pulte said Monday night that Fannie and Freddie will use one mortgage pricing grid, moving VantageScore onto the existing FICO Classic grid; RKT will default to VantageScore 4.0 in 4Q.
- RIVN +1.2% as SVP of Autonomy and AI James Philbin and IR VP Chip Newcom at Evercore put point-to-point on early adopters at year-end and the full Autonomy+ fleet ‘a little later next year.’ New: LiDAR now ‘a few hundred dollars’; a 70% suspension cost cut; a ‘4,000 units a week’ North Star at Normal (215k capacity, 155-160k for R2); VW’s first joint-architecture vehicle is the ID.1; New York offers no eyes-off pathway. The $250m Uber milestone is still due in Q4.
- EQIX +0.4% as CFO Olivier Leonetti at RBC sized agentic AI at ‘50% of the AI demand’ and 30-40% of data center activity within three years. New: 40% more power deployed this year than planned, double 2025’s; hyperscaler and neocloud capex about 80% above last year; the 2029 guide raise owes nothing to the new capex, ‘a drag’ until around 2029; no equity issuance; xScale ‘starting to be a crowded portfolio.’ Interconnection will outgrow the base, with new offerings priced higher.
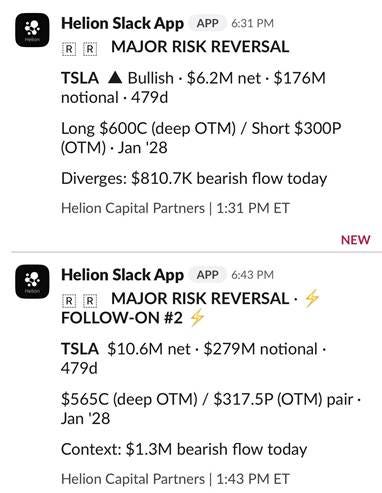
- MBLY -3.0% as Chief Communications Officer Dan Galves at Evercore conceded ‘many of the SuperVision partnerships that we thought were lined up didn’t really materialize.’ New: about 10% 2026 volume growth (3 points China exports, 3 safety stock, 4 top-10 customers against their minus 5% production); hands-free wins at four of five top-10 customers, BMW staying with Qualcomm; cloud-enhanced ADAS lifting ASP from $50 to about $90 at unchanged cost; Porsche at 300-350k units a year, ‘not in 2027’; robotaxi BOM ‘well below $10,000.’- · TSLA -1.3% into Friday’s Q3 deliveries, with consensus around 450K and a range from Cantor’s ~422K to JPM’s 482K. H-Cap in TMTB Slack flagged big bullish risk-reversal flow into the print:
BULLISH AND BEARISH WEEKLY OPTION FLOW
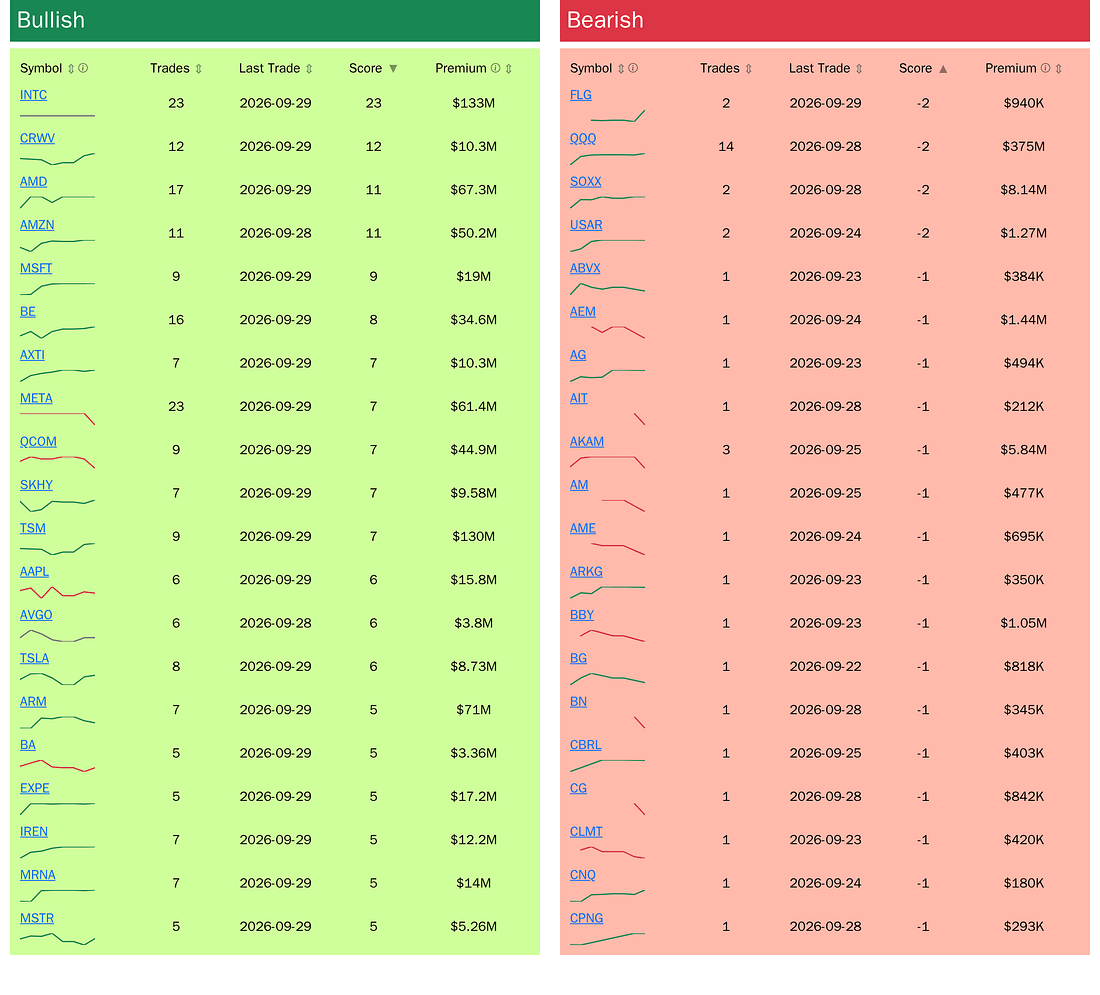 Source: RunningoftheBulltards
Disclaimer:
This newsletter is published for informational and educational purposes only. Nothing here is individualized investment advice, a recommendation tailored to any person’s circumstances, an offer, or a solicitation to buy or sell any security or financial instrument. This newsletter is not an investment advisory service, and no advisory or fiduciary relationship is created between me and any reader.
I actively trade the securities discussed here, often short-term. My positioning may be inconsistent with the views expressed, and I may buy or sell — including immediately before or after publication — without notice or updates. Price targets, upside/downside scenarios and time frames are illustrative opinions, not commitments to hold.
This publication is for the subscriber’s personal use only and may not be redistributed, republished, forwarded, or quoted without prior written permission.
Copyright © 2026 TMT Breakout. All rights reserved.
Full disclosures here