2026.09.29 | Substack | TSEM | TSEM: Foundry Behind the Optics Ramp
原标题:TSEM: The Foundry Behind the Optics Ramp
A quick thesis + financial model
If you invest in the AI infra buildout, Tower Semi has to be on your radar.
The setup over the past few quarters has improved materially and I believe this is one of the companies that has a really durable role to play.
They are a specialty semiconductor foundry. Other companies design chips, then use Tower to manufacture them. The part of the business I care about most is silicon photonics (SiPh), where they manufacture the photonic chips used inside optical transceivers and eventually NPO/CPO.
Q2 revenue reached a record $460M, up 24% YoY. Gross profit grew 72%, operating profit more than doubled and net income grew 95%. Q3 guidance calls for $520M of revenue, which would be another 13% sequential increase.
Silicon photonics is driving a huge portion of that acceleration. SiPho revenue grew more than 270% YoY in Q2 and reached a >$680M annualized run rate. Management expects that run rate to reach roughly $1B by Q4 2026.
The customer commitments give us unusually strong visibility into what comes next. They already have $1.3B of contractual SiPh revenue commitments for 2027, backed by roughly $290M of customer prepayments. Management has said its actual 2027 SiPho expectations are substantially higher than that contractual minimum. Customer capacity commitments for 2028 are larger again.
And they are meaningfully expanding production to meet those commitments. Its current SiPh and silicon-germanium (SiGe) capacity expansion is already being absorbed by customers, while the new Japan build adds another large wave of capacity for 2028 and beyond.
Today, most of the optical demand comes from 800G and 1.6T connections. Tower expects NPO to become a meaningful portion of SiPho shipments in 2027. Tower and NewPhotonics are already shipping laser-integrated 800G and 1.6T products, with 6.4T NPO products planned for the first half of 2027.
SiGe gives Tower another way to participate in the same growth. SiPho handles the optical side of the connection, while SiGe is used in the high-speed electrical components around it. More ports and faster links increase demand for both. Think TIAs, drivers etc.
Basically the thesis has moved from future optics demand to contracted demand, capacity expansion and rapidly growing earnings.
Management recently raised its 2028 financial model from roughly $2.84B of revenue and $750M of net income to $3.6B of revenue and $1.2B of net income.
That is roughly 27% more revenue and 60% more net income than management was targeting earlier this year.
Now let’s look at some financial modeling and where I personally really like the risk:reward for a long term hold.
This article reflects my personal research, estimates and opinions for educational and informational purposes. It should never be viewed as individualized investment, financial, legal or tax advice, or as a recommendation or solicitation to buy or sell any security. Financial forecasts, valuation ranges and price targets are inherently uncertain and depend on assumptions that may prove inaccurate.
TLDR
- I currently own zero TSEM shares. I have been in and out over the past few Q’s.
- I become much more interested around $195/share.
- My 12-month Bear / Base / Bull framework is ~$150 / ~$290 / ~$350.
- My base case uses roughly $3.6B of 2028 revenue.
Tower’s current 2028 target calls for roughly $3.6B of revenue, 45% gross margin, 38% operating margin and $1.2B of net income.
My base case stays close to that revenue target while leaving some room below management’s profitability target.
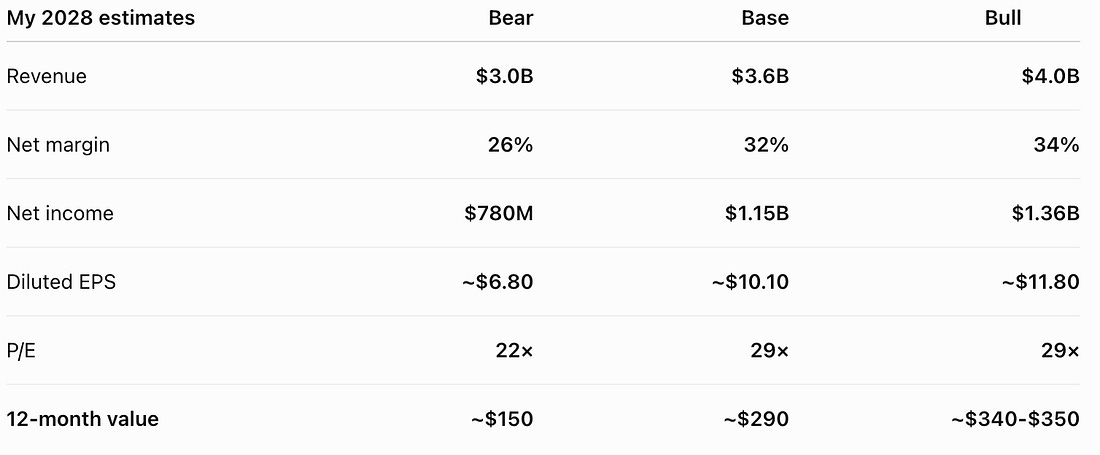
My base case stays very close to management’s $3.6B revenue target while assuming slightly lower net income than the company’s ~$1.2B target.
The contractual demand I mentioned earlier gives me more confidence using that revenue assumption than I would normally have with a 2028 management target.
At roughly $10.10 of 2028 EPS, a 29× multiple gives me approximately $290/share.
Around $195 is where I become much more interested in starting a position.

It’s a confluence of multiple supports. July lows aren’t too far off, theres’s been a consistent pattern of bouncing off that level, the 200EMA and 200D are both within a %. I like when multiple signs all converge, and the valuation can back it up for my desired return.
At $195:
$150 bear = ~23% downside $290 base = ~49% upside $350 bull = ~79% upside
I think getting toward $195 would probably require a rough few days for semiconductors or a broader macro-driven selloff. I don’t have high confidence that my number will hit.
I am deliberately being conservative with new entries in the current macro environment. So please keep in mind your own risk/reward when considering a position and understand that everyone’s portfolio is different. I also have exposure to GFS which has a lot of overlap.
Disclosure: I currently own no shares of Tower Semiconductor (TSEM). I may initiate a position at any time, and my views, desired entry price and valuation framework may change as new information becomes available.
This article reflects my personal research, estimates and opinions for educational and informational purposes. It should never be viewed as individualized investment, financial, legal or tax advice, or as a recommendation or solicitation to buy or sell any security. Financial forecasts, valuation ranges and price targets are inherently uncertain and depend on assumptions that may prove inaccurate.
Investing involves substantial risk, including the potential loss of principal. Tower faces semiconductor-cycle risk, customer concentration, capacity-execution risk, technology-transition risk, competitive risk and valuation risk. Readers should conduct their own due diligence and consider their own financial situation, objectives and risk tolerance before making any investment decision.