2026.09.30 | Substack | Markets | TMTB EOD Wrap: Micron First Takes
原标题:EOD Wrap: Micron (MU) First Takes
Good afternoon. QQQs +25bps on the last day of the quarter, fading from +97bps at the highs with most of the give-back in the last 40 minutes. Software over ~~AI~~ SI infra was the trade today: software +1.2% led, with the names hit by META’s enterprise push and OAI Dev Day bouncing hardest (MNDY +3% HUBS +3.7%; PATH +4.2%), while semis +21bps lagged (AVGO -1.1%; ASML -1.2%; SKHY -1.4%) and AI infra/power bled (JBL -10.1% despite a decent set of numbers& CBRS -8.9% reports they won’t be used in Ultrafast led the way lower)
Mega caps held in (AAPL +1.1%; AMZN +1%; GOOGL +93bps; MSFT +77bps), META -1.8% the lone man out. GOOGL was up 2% heading into the close before Bloomberg reported they were “grappling with internal skepticism over how well the flagship artificial intelligence model performs in key areas.” Then GOOGL actually dropped Gemini 4 “Argon” post-close and it actually looks pretty solid and right around the frontier on benchmarks:
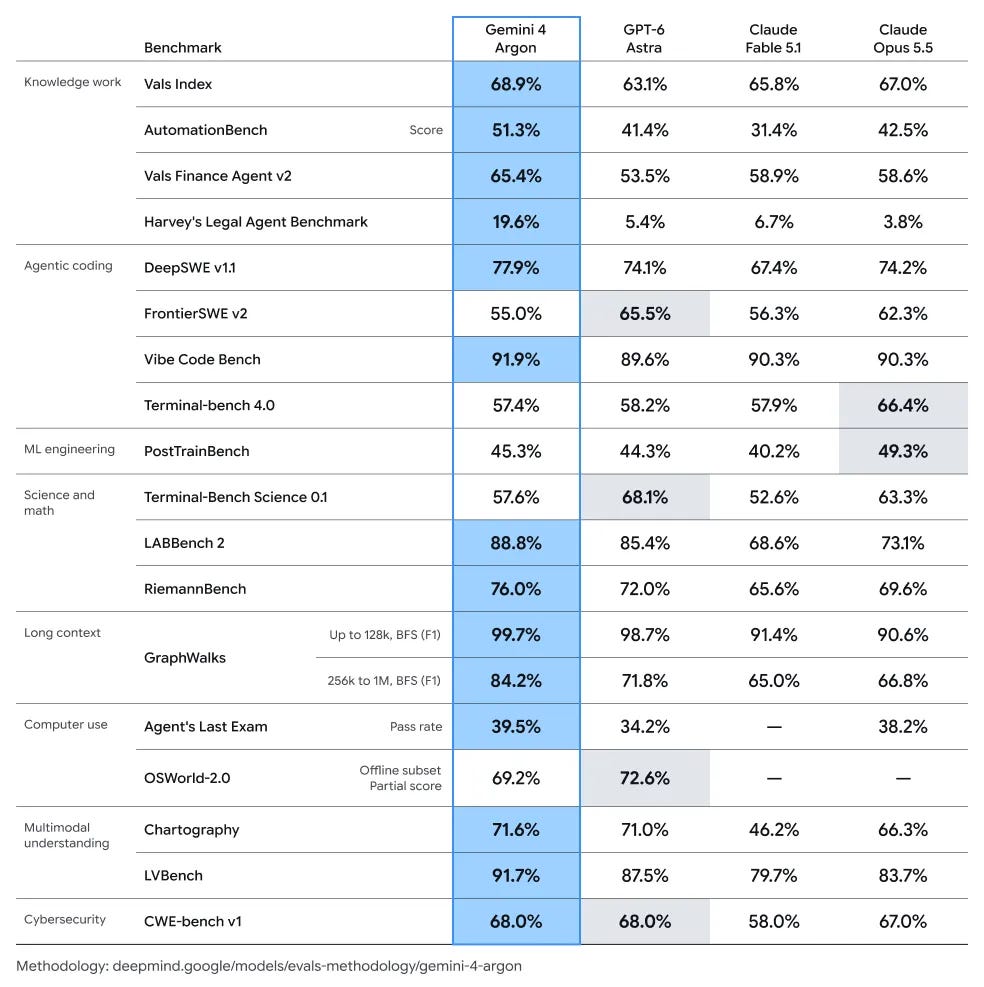
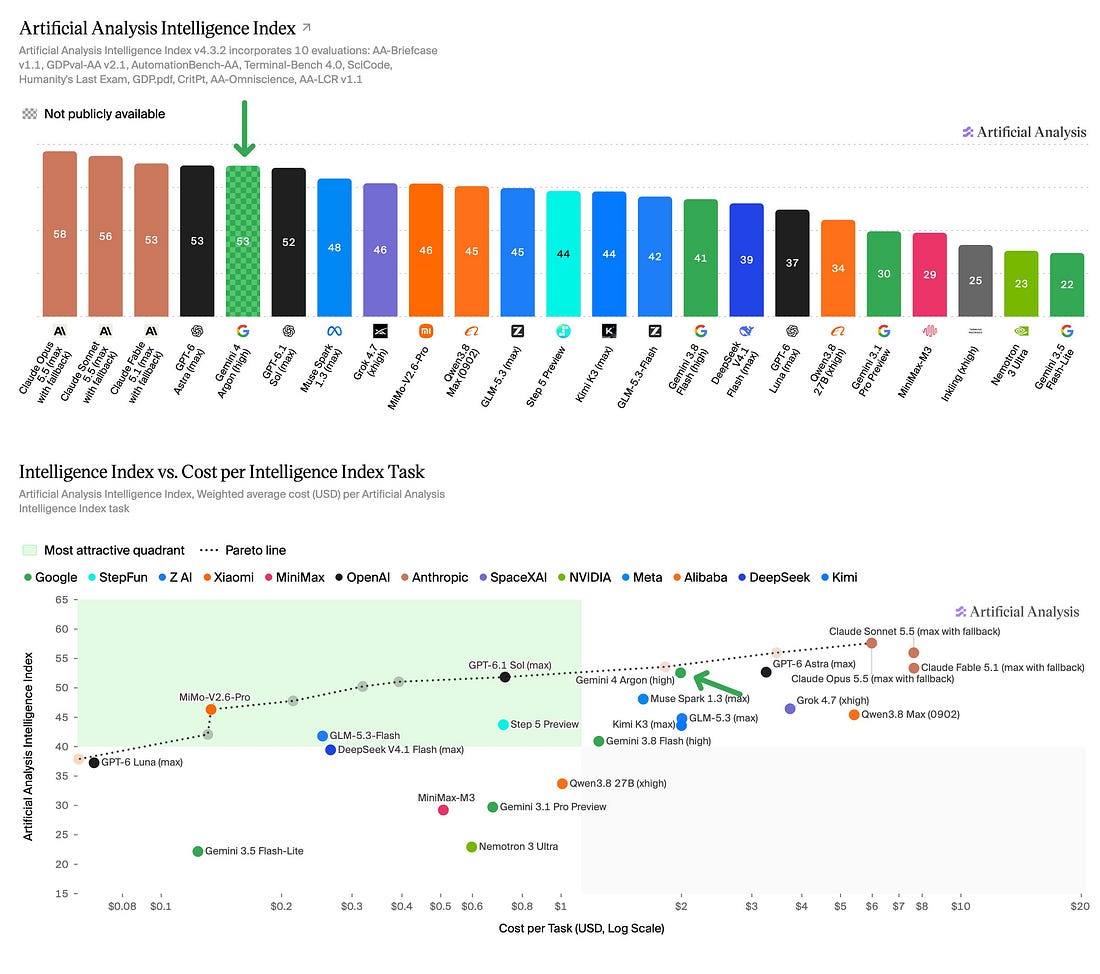
Cost is same price as Opus 5.5. The glass half full from bears will likely be: still 1-2 months behind and now what’s the catalyst for bulls to look forward to while search fears still abound…
Lets touch quickly on the macro today as its top of mind for investors: another bear steepener, this time on softer data. August core PCE came in at +0.2% m/m and 3.0% y/y vs. 0.3%/3.3% expected (a 6-month low, helped by a BEA methodology change) and ADP was +90K vs. ~70K; yields dipped on the print and then turned higher, with the 2Y -1bp to 4.88%, the 10Y +3bps to 5.29% (highest since 2007) and the 30Y +5bps to 5.64%. As @jturek18 on X put it (h/t Arun Dhar in TMTB Slack here): “dovish data right now is more pressure on the backend than it is relief on the front end.” Fed pricing went the other way: ~35% odds of a hike on 10/28 (from ~50% Tuesday and ~71% Monday), ~30bps of hikes priced for the rest of 2026 and another ~60bps in 2027. Just before the close (~3:50pm), Trump said on Truth Social that Fed Governor (and former Chair) Powell should resign over the Fed HQ renovation after an inspector general report, or be sued “for either corruption or incompetence.” WTI +1.4% to ~$90.6 as Trump denied an Axios report that he’d ease Iran sanctions. BTC flat at ~$83.7K.
Post-close:
MU +2%: Big revenue/EPS beat and strong FQ1 guide, with gross margin the only real blemish.
MU beat across the board, with FQ4 revenue well above Street and EPS above even the buyside bogey, while FQ1 revenue/EPS guidance also cleared expects. The one nit is gross margin guide: FQ4 hit the ~87% bogey, but FQ1 guides down to 86.25% vs. ~87-88% buyside, although initial read seems like it’s all due to mid-shift to HBM and they are saying Q1 will be floor for GMs in ‘27. Call ongoing.
“We anticipate fiscal Q1 to be the floor for gross margins in fiscal 2027. As Sanjay mentioned, we made a decision to increase fiscal 2026 incentive compensation in fiscal Q4. Most of the increase in fiscal 2026 incentive compensation pertaining to manufacturing was absorbed into inventories in fiscal Q4. As a result, the effects from the sale of these higher cost inventories principally impact fiscal Q1 gross margin. Fiscal Q2 benefits from less of this fiscal Q4 related compensation expense, but this benefit is offset by the impact of higher fiscal 2027 incentive compensation. We expect higher gross margins beyond fiscal Q1 for the remainder of fiscal 2027, with a more moderate rate of price increases.”
FQ4 revenue: $54.23B vs. ~$51B Street FQ4 EPS: $33.42 vs. ~$31.50 Street / $33+ bogey FQ4 gross margin: 87.0% vs. ~87% bogey FQ4 operating margin: 82.3% FQ4 operating cash flow: ~$44B FQ4 adjusted FCF: ~$33B
FQ1 revenue guide: $60-63B, midpoint $61.5B vs. ~$57B Street / ~$60B bogey FQ1 EPS guide: $37.15-39.15, midpoint $38.15 vs. ~$36 Street / ~$37.5 bogey FQ1 gross margin guide: 86.25% vs. ~87-88% bogey
Let’s get to the good stuff…
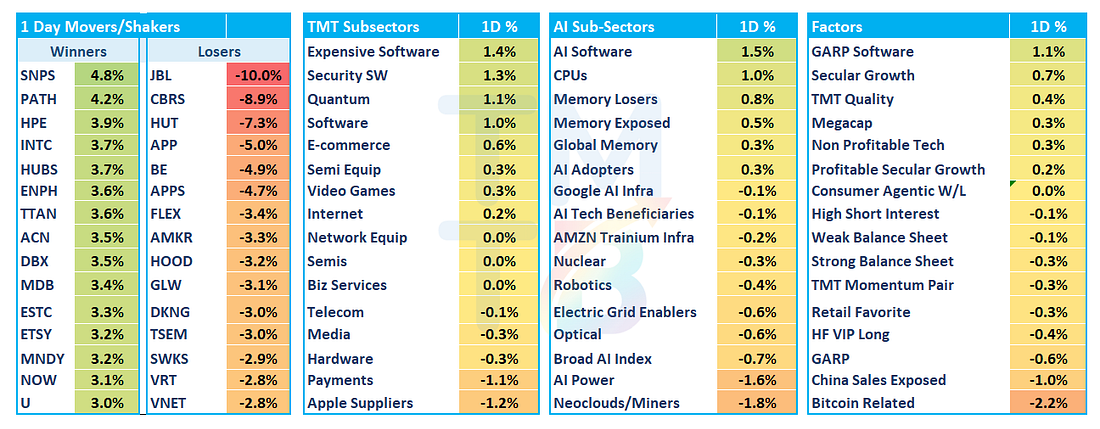
AI/SEMIS
- SNPS +4.8% had a busy day: a $1B+ AWS license deal spanning Graviton, Trainium and Nitro generations pre-market, then an analyst day with FY27 guidance two months early (revenue +15% to $11.15B vs. ~11% consensus; EPS +27% to $19.08; a $1B buyback) and the long-term revenue CAGR raised to mid-teens through 2030 from double digits. It also announced “GPT-Synopsys” with OpenAI, an AI model for chip design where OpenAI pays a training subscription plus a revenue share, structured so it “will not be cannibalizing our business” per CEO Sassine Ghazi. In the analyst-day thread in Slack here, Marengo flagged the new custom-silicon IP business getting to ~$1B of revenue by FY30, while EM countered that IP growth was in line with the high teens already expected. Up +7.3% at the highs; CDNS +1.9% in sympathy.
- INTC +3.7% got a cameo at the SNPS analyst day, where Ghazi raised the "you have lost Intel" question himself and answered it with an INTC video on 18A/18AP/14A co-optimization; INTC also hired Sunil Kaul from MRVL to run hyperscale and data center sales. Bluefin also had some positive checks saying High NA EUV has cleared several key obstacles, ready for adoption on 14A
- JBL -10.1% beat and raised and still got hit: FQ4 revenue $10.6B vs. $9.7B, an FQ1 guide of $10.6-11.4B vs. $9.98B, and FY27 revenue of $44.5B vs. ~$42.9B, with ~$22.1B of AI revenue (+54%). It traded as high as +2.9% before selling off all day. The pushback on the print: capex rising to 1.5-2% of revenue from 1.3%, inventory at 64 days vs. a 55-60 target, and margins back-end loaded. EMS peers were lower too (FLEX -3.4%; CLS -1.4%).
- CBRS -8.9% after SemiAnalysis said last night that OpenAI’s GPT-6.1 Sol Ultrafast “is NOT running on Cerebras but… at a low batch size on NVIDIA GPUs” (@SemiAnalysis\_ on X), a day after most read Ultrafast as a CBRS win. Isaac S. in TMTB Slack here reread a 9/16 post from @thsottiaux on X as CBRS not being able to handle Ultrafast yet, with NVDA swapped in. It didn’t help that ~19.4M shares came off lockup today with the stock now below its $185 IPO price.
- CRDO +1.3% as Jefferies came back constructive from hosting CRDO’s NDR in NYC yesterday. On SPCX, they admit visibility/messaging is unclear but noted SPCX’s plan to install another 660k GB300s across the Dec quarter, and potentially the Mar quarter, suggests 50-100% upside from current levels ($130-150M/qtr) vs. the implied flat AEC guide. Longer term, Jefferies also sees SPCX as a potential ZF Optics customer. Next up is OCP where mgmt will be hosting meetings with investors and CRDO should show its first MicroLED-powered ALCs and could lay out a MicroVCSEL roadmap.
- AI power gave some back: BE -4.9%; VST -1.8%. BE got two more bullish sell side mentions after yesterday’s bullish MS and RBC note (JPM: Fremont can add a GW every 6-9 months and reach 5GW at the same headcount; UBS: Ameren Missouri’s ~500MW fuel-cell plan makes BE the prime beneficiary) but gave back part of Tuesday’s +10.8%. The policy headlines kept coming: FERC accepted PJM’s emergency capacity plan for data centers but suspended it until 2/28, and the Senate blocked the GOP bill on data centers and household power bills 57-43.
- GLW -3.1% as Bernstein started it at Market Perform within an otherwise bullish networking/optical initiation, arguing the AI optical upside is largely priced in; MS flagged ~$800M of added capex/startup costs weighing on margins until ~4Q.
- TSM -15bps despite JPM raising EPS 5/6% on tighter N3/N2 and much faster capacity ramp
- SPCX +1% as Needham had some interesting snippets after an IR call, saying most announced AI compute deals now ramp in 4Q26, including one beginning in December, with those deals alone reaching a combined ~$54B annualized revenue run-rate and supporting management’s ~$100B total-company ARR target by YE26. Needham cut 2026/27 revenue and EPS to reflect the slower ramp, but sees upside if deployments accelerate.
- HUT -7.3% on a Form 144 showing CSO Michael Ho filing to sell 1.5M shares (~$139M) under a prepaid forward; CEO Asher Genoot said at 12:37pm that Ho borrowed against his stake to fund taxes on future vesting rather than selling:
Asher Genoot
@ashergenoot
Mike needed liquidity, including to fund taxes associated with future equity vesting and other personal liquidity needs. The simplest option would have been to sell stock. But Mike remains highly convicted in Hut 8 and wanted to retain as much exposure to the stock as possible.
4:37 PM · Sep 30, 2026 · 2.92K Views
1 Reply · 14 Likes
INTERNET
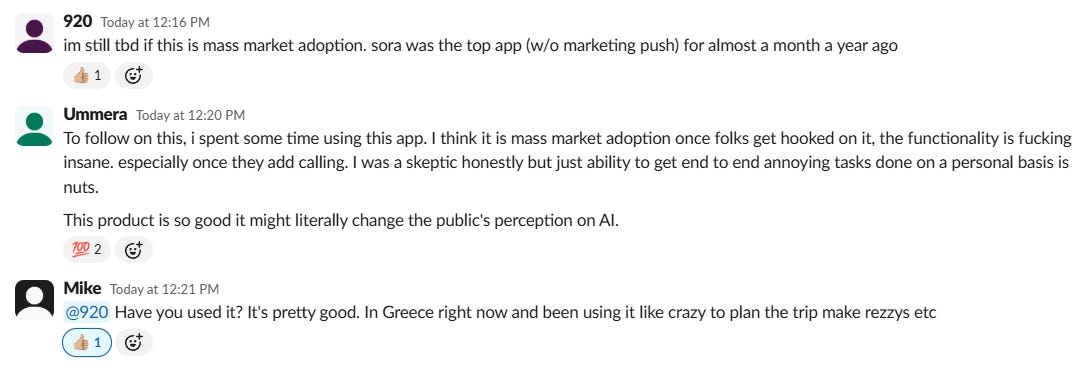
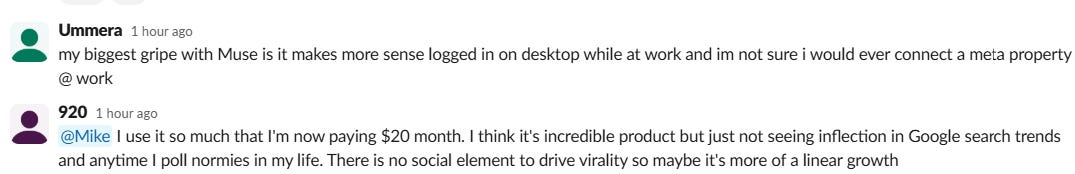
- META -1.8% was left out out the Megacap rally as it continues to digest recent strength even as Muse keeps putting up numbers: Sensor Tower data AB posted in TMTB Slack here has Muse past 5.1M US downloads in 22 days vs. 2.3M for ChatGPT over the same stretch. Some good feedback in TMTB Slack here on usage:
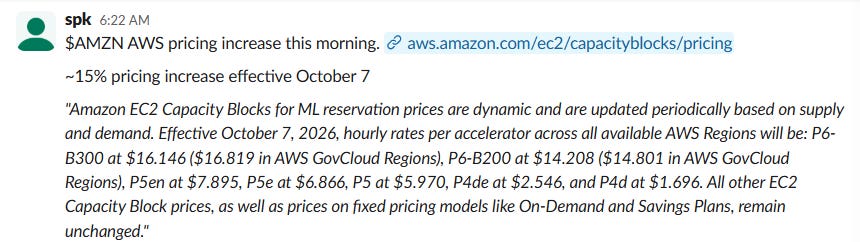
- AMZN +1% as BMO turned incrementally positive: its cloud expert check has committed spend accelerating ~300bps in 3Q as scarcity pushes customers into longer commitments, and it calls the $300B FY27 capex estimate conservative. The same expert doubted Trainium (roughly a dozen trialists) can match TPU (hundreds of external teams), and late in the day DIGITIMES reported Trainium 3 shipments are being slowed by component shortages and assembly bottlenecks. AWS also announced they are raising prices 15%;
- ETSY +3.2% with no real news, but the bull case making the rounds is that conversational search is an unlock for one-of-one SKUs that keyword search never handled well; card data shows only a 1-2pt decel QTD, and it sits at ~9x EBITDA vs. W at 15x and EBAY at 13x.
- DASH -1.9% launched a text-to-order agent inside Apple Messages at its DashForward event and said it’s in talks with META on Muse. Useful stat for the agentic-commerce debate from Citizens’ notes with the CMO: early agent traffic cut basket size by two-thirds.
- SHOP flat after a couple bullish notes. UBS was out saying they see modest but high-margin Payments upside, with Muse/Instinct preserving Shopify economics. Jefferies was out saying they see money transmitter licenses as next Merchant Solutions unlock, with ~5% ’28 OI upside. Investors generally coming around to the view that SHOP is agentic winner after the back and forth debate over the last few weeks.
- SPOT -1% as Wells cut NT numbers and said they think AI music tier launch is now Q2’27 vs Q1.
SOFTWARE
- MDB +3.4% had a delayed reaction to Tuesday’s investor day (+75bps then), touching +9.9%: the new 3-year framework calls for 20%+ growth with Atlas at mid-20s (from 20%+), 100-200bps of annual margin expansion and a $5B+ revenue path, plus $1B more buyback. Sell-side was out generally positive on the #s, but Evercore sees no idiosyncratic AI narrative yet at 8x EV/CY27 sales and a re-rating that awaits a permanent CEO after CJ Desai’s exit to META, and Stifel wants to see Atlas re-accelerate with Postgres a near-term overhang.
- The rest of software joined the bounce off Monday/Tuesday’s lows: SNOW +2.8% trying to get its groove back now that $3.75B convert behind them; NOW +3.1%; ADBE +2.9%; ADSK +2.9%; INTU +2.9%, etc.
- OKTA +2.1%. as Cleveland was out positive saying partners indicating Oct Q is tracking ahead of guide and competitive positioning in workforce identity has improved.
- ACN +3.5% into tomorrow’s FQ4 print, where UBS expects the focus on AI’s impact on the core business, noting ~60% of revenue now runs through its top 10 alliances (vs. ~50% in 2022) and ~60% is fixed-price (vs. ~50% in 2023).
- MSFT +77bps as Piper built out the M365 math: every 10% of E5 seats that migrate to the new $99/month E7 SKU adds ~$2B of annualized revenue, and Copilot/Cowork consumption can reach a ~$2B run-rate by FY28, in about half the time seat-based M365 Copilot took.
- APP -5% as Wells argued the e-comm pixel acceleration is a false start: most new pixels are APAC Shopify storefronts with little or no traffic, traffic-weighted adds are flat in September vs. 1H26, and it doesn’t see a customer inflection before 2027.
- U +3% taking to heart what we said yesterday, at least so far: “Our sense is it should begin to start to act better heading into the Q now that those headline risks [META/Dev Day/World Model releases] behind them.”
- ORCL -31bps recovered from a -2.2% low even as Aterio flagged power delays at Project Lighthouse (Port Washington, WI) on top of the Jupiter force majeure; K in TMTB Slack here thought it “reads as worse than NM.”
ELSEWHERE
- · AAPL +1.1% on a drip of Bloomberg news: new CEO John Ternus is pushing faster, broader releases and a flatter engineering org as AAPL absorbs part of higher memory costs, and the smart-home push (a ~6-inch display hub) launches 10/13. Counterpoint sees ~6M iPhone Duo foldables this year, with iPhone 18 Pro China launch sales +12% vs. the 17 Pro.
- HOOD -3.2% round-tripped from +6.3% at the highs after Tuesday’s Summit, sell-the-news style after a ~76% six-month run. MS liked the content: Robinhood Agents past 150K accounts (from ~100K at 2Q), US crypto perps up to 10x leverage (not in estimates), and HOOD potentially keeping ~25-30% of third-party agent-app economics.
- MBLY -2.3% as Barclays downgraded to Equal Weight, arguing it still hasn’t landed enough large advanced-ADAS wins to validate the ASP story (SuperVision ~$1,300 vs. ~$50 today on the VW ramp) while Horizon now has roughly half of China L2 ADAS vs. MBLY at ~25%.
- DKNG -3% as JPM, after a G2E meeting with the CFO, read the plan to pull prediction-market spend forward into FY26 as putting total FY26 adj. EBITDA below the $700-900M guide, even with handle +15% y/y through the first two NFL weeks. M-sci was also positive saying they are gaining share QTD
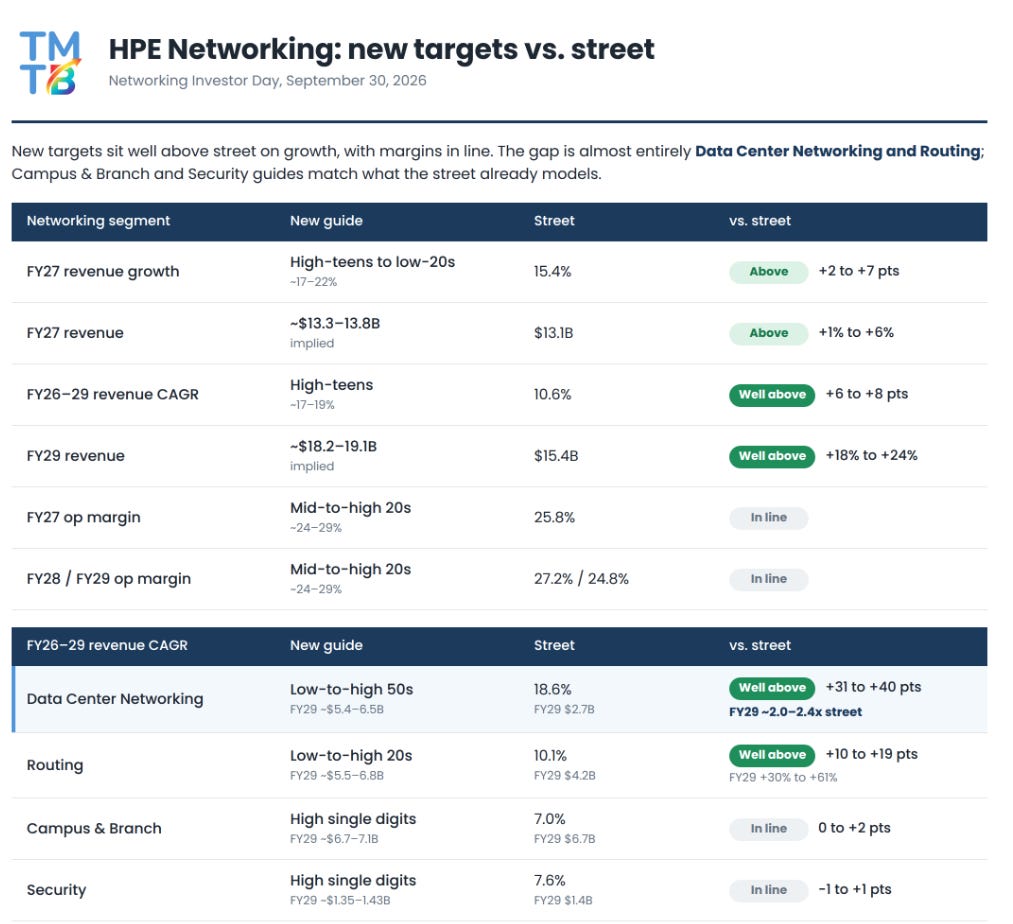
- HPE +4% after raising rev and synergy guidance but keep margin guide intact in front of their analyst day
Implied EPS:
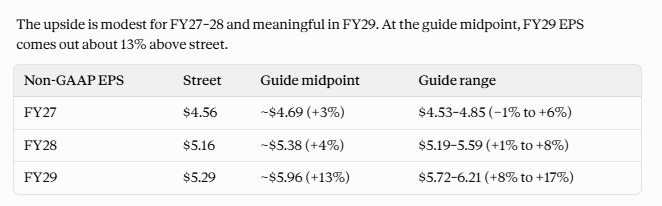
Bulls will say throw 15x+ on $6.25 which should get you something close to $100 in a year or two. Targets vs. street:
BULLISH AND BEARISH WEEKLY OPTION FLOW
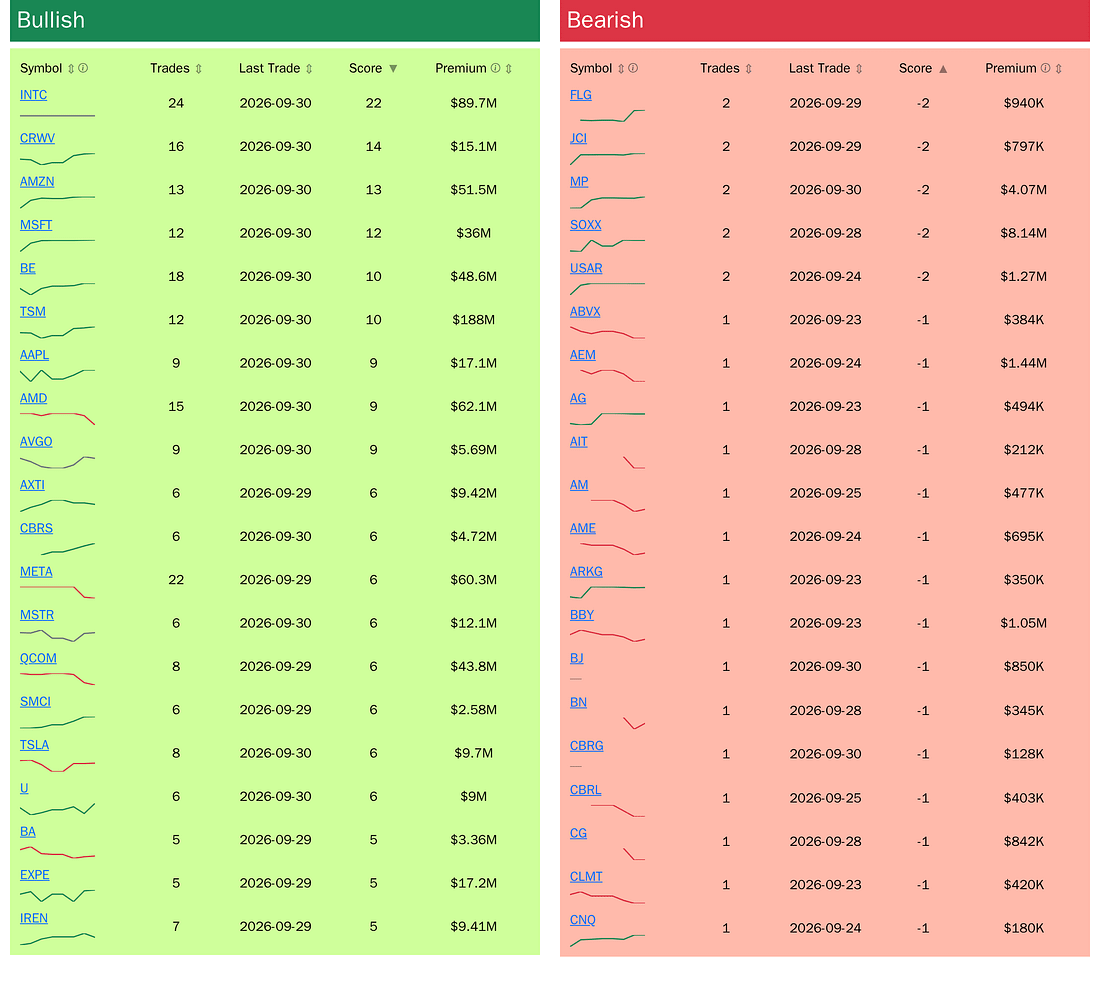
Source: RunningoftheBulltards