2026.10.01 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
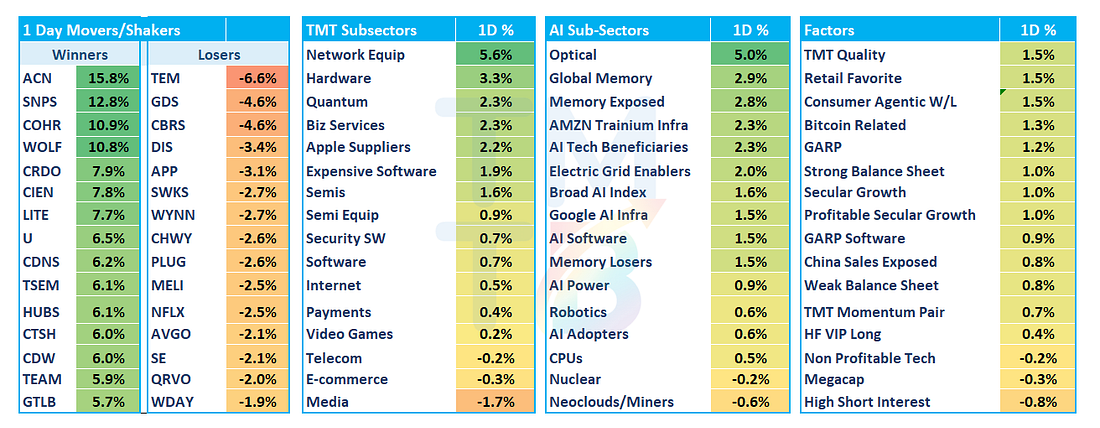
Good afternoon. QQQs +31bps in a choppy one: up ~40bps early, down ~50bps by 11am as stocks sagged even with bonds rallying, then a sharp ramp around 1pm to +66bps at the highs, before giving away half. Software +1.6% leading as the SI-loser squeeze continued: ACN +15.8% on a clean print vs. very low expectations took IT services with it (CTSH +6%; EPAM +5.5%; INFY +5.5%; IBM +2.6%); agent-exposed apps also caught a bid (HUBS +6.1%; TEAM +5.9%). Semis +1.4% didn’t lag however: optical ripped intraday (COHR +10.9%; LITE +7.7%; CIEN +7.8%) on a Morgan Stanley note that any China transceiver curbs start at 3.2T, and EDA kept going after the SNPS analyst day (SNPS +12.8%; CDNS +6.2%). Mega caps were mixed: NVDA +1.1% on bullish NDR recaps, while GOOGL -1.7% round-tripped a +2.7% open on the Gemini 4 Argon pop as consensus was that results were heavily benchmarked and focus shifts back to search fears/lack of consumer agentic product, AVGO -2.1% lagged after agreeing to lend Anthropic up to $42B and AAPL -81bps underperformed as well.
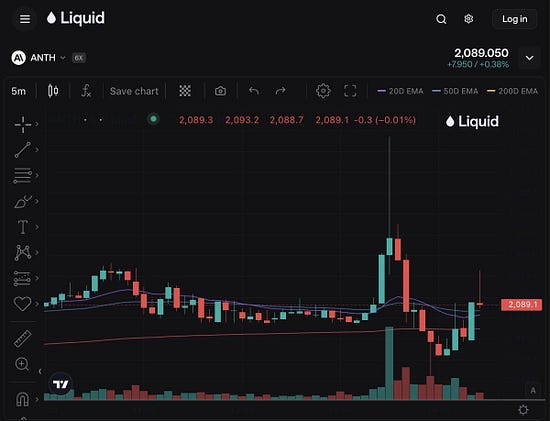
Speaking of Anthropic, in the afternoon Bloomberg reported they are targeting a IPO before Thanksgiving, with marketing as soon as the week of 11/9 and continuing to meet with investors in October; its pre-IPO perp on Liquid briefly spiked above a $2.1T implied valuation before reversing:
Liquid
@liquidtrading
JUST IN: Anthropic’s pre-IPO perpetual briefly spiked above a $2.1 trillion implied valuation before reversing after Bloomberg reported the company could begin its IPO roadshow the week of November 9, targeting a trading debut before Thanksgiving.
6:35 PM · Oct 1, 2026 · 55.3K Views
5 Replies · 4 Reposts · 20 Likes
In macro land, investors continued to focus on the long end of the curve. The 10Y spiked to ~5.34%, the highest since 2002, after the 10am ISM, where the headline was a touch light (54.5 vs. 55 expected) but prices paid jumped to 77.9 vs. 73, the highest since May, then yields reversed with no obvious headline, ~11bps off the high by mid-afternoon and led by the front end (the 2Y was down ~13bps at one point to 4.76%), to finish 10Y -6bps to ~5.24%. Vice Chair Jefferson said the Fed may need “more time” to decide on its next move, which some took as an effort to take some steam out of an October hike, which seemed to work as now only ~30% odds of a hike at the 10/28 meeting (down from 70%+ early this week). WTI +3% to ~$93 and Brent back above $100 after China reportedly suspended October fuel exports, with WSJ reporting a third carrier strike group headed to the Middle East. BTC +1.3% to ~$84.6K.
Ok, let’s get to the good stuff…
AI/SEMIS
- Optical ripped intraday after opening roughly flat: COHR +10.9%; LITE +7.7%; CIEN +7.8%. The note making the rounds was Morgan Stanley’s after its strategists met officials in DC: potential FCC rules on optical transceivers would likely start at 3.2T modules made in China (800G/1.6T left alone), with a workaround if US content is above 65% of the BOM, which it framed as a win-win for LITE/COHR as lasers stay tight without them taking on lower-margin module assembly (note was getting passed around on X by 11:17am here and getting a lot of play here on a re-post by Serenity (he’s back!)). That chips at the COHR bear case on Chinese transceiver share gains (the medium-term worry), though Ted in TMTB Slack here pushed back that a 3.2T start barely touches the Chinese module makers near term, since 1.6T will be around for a while. Optical investor sentiment has been increasing steadily since a wave of positive mgmt meetings throughout September and the usual retail optical bulls on X and substack are becoming louder as of late as we head into OCP on Oct. 12th.
- Some good discussion in TMTB Slack
here around LITE’s outsized strength. n asked if it was rumors of a new ELS customer, pointing to LITE saying at ECOC that one emerging ELS customer could ultimately be a bigger opportunity than NVDA given the optical intensity of its architecture, and guessed AAPL (CPO with M8 chips).
· Ted doubted it: that looks like a 2029 event, and AAPL’s demand would likely flow through NVDA’s CPO switches anyway since the fabric is NVLink/Fusion.
· HK and JL read it as flows, a reversal of the “long memory, short optics” bottleneck trade with ACN-driven unwinds, COHR outperforming LITE is unwindy action they said; JL also saw a delayed reaction to Bernstein’s positive initiation after investors leaned negative on optical ex-LITE on mixed ECOC checks.
· Arun Dhar disagreed: LITE “bucked the optics unwind bit for the most part,” so “something fundamental,” with the customer news already old.
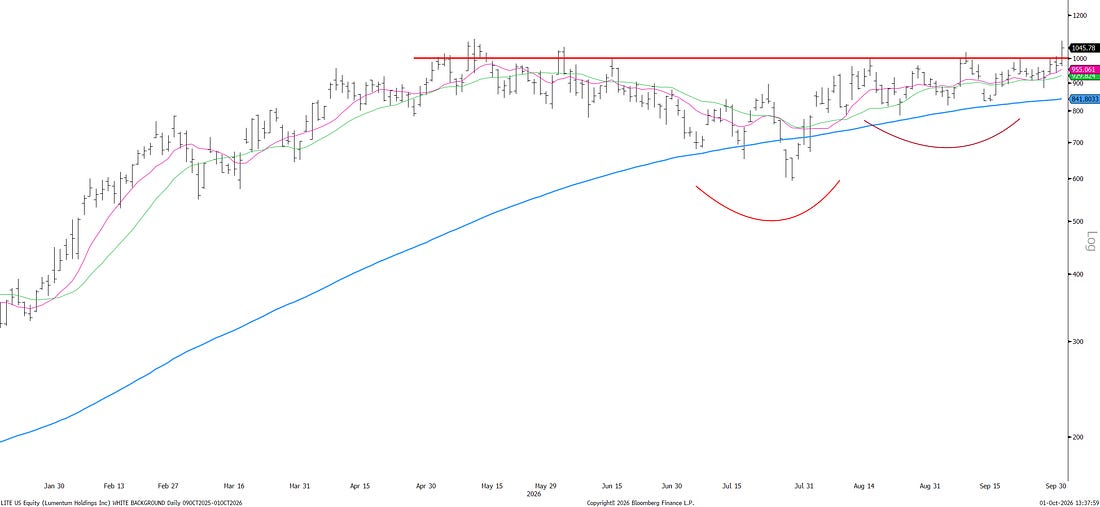
We agree with Arun and we have noticed stock had been acting extremely well as of late, and we flagged it in our weekly Sunday as our favorite chart in Semis (coupled with good narrative, checks, and positive sounding mgmt meetings throughout September). Now breaking through $1k resistance:
Source: Bloomberg
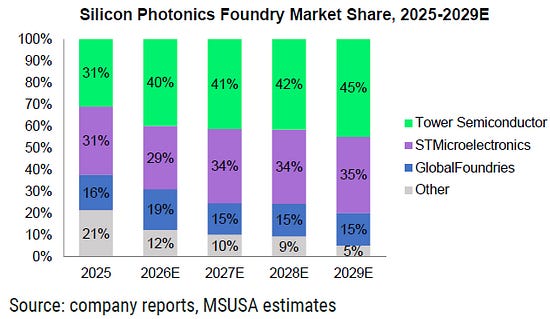
- TSEM +6.1% got a piece of the photonics bid, with a Mizuho exhibit passed around on X sizing its silicon-photonics foundry share rising to 45% by 2029E from 31% in 2025 (via @techfund1 on X):

Tech Fund
@techfund1
The Silicon Photonics Foundry market (Mizuho estimates) $TSEM $STM $GFS
11:57 AM · Oct 1, 2026 · 3.07K Views
1 Reply · 3 Reposts · 37 Likes
- SNPS +12.8%; CDNS +6.2% as the analyst-day notes rolled in, with SNPS adding to yesterday’s +4.8%. JPM sees a path to ~$35 of FY30 EPS (mid-teens revenue CAGR, ~50% OPM), with AI agents driving 5-10x more tool calls rather than cannibalizing EDA, and Stifel noted the FY27 guide ($11.15B/$19.08) sits well above its prior $10.80B/$17.34. KeyBanc’s noted that the day “addressed bear concerns” for EDA carried CDNS along.
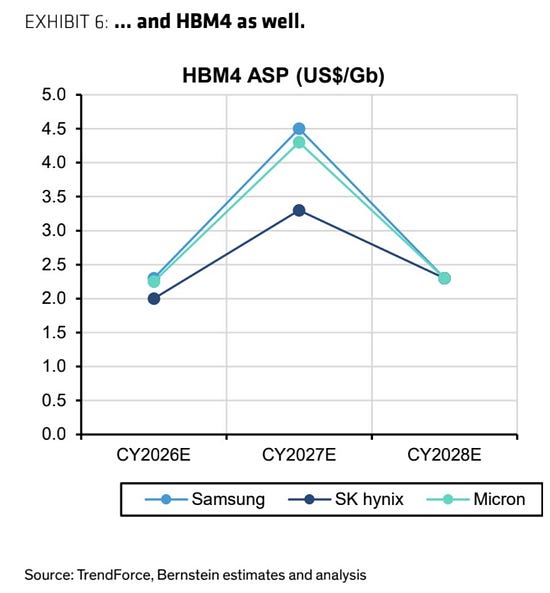
- MU +3% closed near the highs after trading -4% at the lows. MyNameIsJeff in Slack put it well: “a nothingburger move for a 3 beta stock” or as H-cap said “Memory now trades like a T-bill.” Overall, buyside #s not really moving much with better EPS but GMs weaker (bulls at $200+ for CY2027 EPS). Typical bull vs. bear debate on memory we’ve been hearing over last couple months today with bulls pointing to better visibility/LTAs/supply/demand dynamics with potential for big cash returns on a stock trading at ~5-6x while bears will point to uncertainty in ‘28 and beyond, where the pushback we’re hearing is that tools arrive, supply speeds up and open-market pricing falls from mid-2028. Overall, we think memory continues to be choppy & trending up over time but we’ve been hearing investors (both in US and Asia) getting incrementally positive on the space. On the SCA issue, we thought UBS put it well saying pricing would need to fall >70% before customers walk from SCAs, and MS sees the closing of HBM’s margin gap adding ~$9 to quarterly EPS. A Bernstein exhibit on X has HBM4 ASPs peaking in CY27 (~$4.3/Gb for MU) and dropping to ~$2.3/Gb in CY28 (via @pequityresearch on X):

P Equity Research 📰
@pequityresearch
Bernstein expects HBM4 ASP to peak in CY2027, with Micron and Samsung commanding the highest price ~$4.5/GB $MU $DRAM $EWY
3:03 PM · Oct 1, 2026 · 6.09K Views
7 Replies · 2 Reposts · 40 Likes
- Semicap caught a bid on MU’s capex numbers: FY27 net CapEx is implicitly above $50B: approximately $25B in the first half, with the second half higher. That is more than 80% above FY26’s approximately $27.3B, but mgmt did not provide a precise $55B full-year guide. AMAT +3.5%; TER +3.7%; LRCX +3.5%; KLAC +2.8%. Followed strength in Japan as SPE names ripped overnight (Advantest +9.8%; Lasertec +11.1%; TEL +6.5%). Also following through on the news this week that TSMC is weighing a new Texas campus that would add tens of billions of dollars to its US buildout.
- NVDA +1.1% on the NDR recaps: Cantor says mgmt sounded incrementally more bullish, with upside to 70%+ CY27 growth and NVDA’s share of hyperscaler IT capex potentially rising to the mid-40s% from ~40%, while Barclays’ read of the NDR deck implies $30B+ of upside to its CY26/27 hyperscaler revenue (~$237B/$401B vs. ~$206B/$370B).
- AMD +65bps: DigiTimes reports AMD’s 2027 Venice EPYC capacity is sold out with orders now being taken for 2028, as AI agents push server CPU lead times out to 25-30 weeks from 16-20.
- WOLF +10.8%; NVTS +4.4%; ON +4.2% as Taiwan’s power-device makers follow Infineon and ON with October price hikes of ~10-15% on non-contract MOSFETs, citing tighter 200mm capacity, higher packaging costs and AI-server orders (Commercial Times).
- CRDO +7.9% still riding Jefferies' NYC NDR (SPCX potentially adding another 660K GB300s; OmniConnect ramping in 2H27). Irrational Analysis also added the name to his portfolio and had some positive comments, saying CRDO’s SerDes portfolio is second only to AVGO/NVDA, that it’s better positioned than MRVL for slow-and-wide uVCSEL, and that the reported pivot from uLED to uVCSEL is the right move.
- JBL +4.5% got back some of yesterday’s -10.1% (CLS +3.2%; FLEX +2.5%) as Stifel walked through the FY28 setup: AI revenue +54% to ~$22.1B in FY27 and a second hyperscaler on track to top 10% of FY27 revenue, with a third as upside.
- · GEV +3.9% as Evercore raised 2027/28 estimates 3-4%, now seeing the $200B backlog milestone pulled into early 2027, and named it a primary beneficiary of behind-the-meter power (~72GW deliverable by 2030).
- BE +22bps didn’t do much with more bullish notes: Barclays sees its second Fremont facility giving line of sight to ~10-12GW of capacity vs. ~5-6GW today with an order book now >$9B, and MS says native 800V DC saves ~$3.7B/GW of non-compute capex.
- AVGO -2% continues to be everyone’s favorite funding short.
- CBRS -4.6% faded an early +2.4% to extend yesterday’s -8.9% with no fresh news outside the lack of Ultrafast exposure earlier this week; supply is still the overhang after ~19.4M shares came off lockup yesterday.
- SPCX -1.9% The Information reported its AI unit has turned itself into an AI cloud, already generating billions of dollars a month in commitments from labs including Anthropic and Google, and held talks with MSFT over the summer to lease it capacity.
- CRWV +1.7%: the Fully Connected sell-side notes had another ~10% GPU price increase on top of July’s ~25%, with demand still well above supply into 2027/28 (MS; Rosenblatt).
- INTC -20bps
Ara Kharazian
@arakharazian
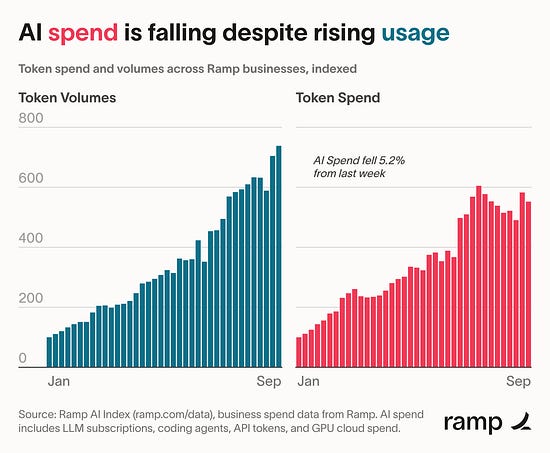
NEW: AI Spend FALLS in the latest Ramp AI Index. Price cuts at the frontier, in addition to cheaper and more efficient models at standard and lite levels, are pushing down the cost of using AI. Open source models remain <5% of business spend. This decline in spend is driven …
7:24 PM · Oct 1, 2026 · 36.7K Views
22 Replies · 34 Reposts · 264 Likes
INTERNET
- · GOOGL -1.7% sold the Gemini 4 Argon news from early on: +2.7% in the first minutes, flat within half an hour and -2.5% at the lows around 12:30pm, before a 1pm Bloomberg report that a NY judge will let publishers pursue more than $3.2B of ad-tech damages. Tae Kim in TMTB Slack voiced what some are saying amid Argon’s strong bechmark performance: “Market’s verdict on Gemini 4: likely bench-maxxed like all their prior models.” The rollout is gradual amid safety concerns, which makes true performance hard to gauge. As we wrote yesterday, with this catalyst out of the way, focus shifts back to search concerns amid perception (reality) that Google has so far dropped the ball on consumer agentic.
- META +10bps as MS ran the Muse math 23 days in: direct monetization stays minimal until late ‘27/’28 (transaction/acquisition auctions across a ~$30T consumer TAM), ‘26 CPU purchases alone could support ~1B DAUs, and just 100MW of dedicated API capacity could add ~4% (~$1) to ‘28 EPS. Similarweb has Muse approaching 2M DAUs.
- RDDT +5% on chatter that 3p data shop Oxford has a big call-out with revenue running "way above" Street numbers as of 9/30 (per @markflowchatter on X):

Marc Lehman
@markflowchatter
on $RDDT - Hearing 3pd Data shop OXFORD has a big call out that $RDDT Revenue is "way above" the street # 's as of September 30th
3:53 PM · Oct 1, 2026 · 11K Views
8 Replies · 5 Reposts · 43 Likes
This isn’t particularly new news since ODP models KPIs daily in a dashboard with just a 24hour lag (so anyone with access would have seen #s trending above street for a while) and RDDT has averaged 8-10% beats the past few quarters. If you want to check out the #s for yourself, we are friendly with the ODP team: e-mail makay.redd@oxford-dp.com and mention TMTB for a 1-month free trial. Early on in quarters (eg, early October) typically good for RDDT as stock usually rallies on strong checks into EPS as focus shifts to that before the quarter typically puts the spotlight back on DAUs, where debate is more muddied (everyone knows RDDT typically puts up a big top line #).
- NFLX -2.5% after Ted Sarandos told Bloomberg NFLX is growing more slowly than he wants, with engagement up just 2% despite double-digit revenue growth in every region. A check we heard has ad-tier CPMs down to the high-$20s/low-$30s from $65 at launch (YouTube is ~$10).
- SE -2.1% as DBS downgraded it, with good discussion in TMTB Slack here on why it’s been so weak: AquaCap pointed to oil/macro, mixed-to-negative 3p tracking and the chart, while Family Office Dude passed along HK chatter that Tencent could sell SE to fund capex (as TM did with GRAB ~2 weeks ago) and doubts Monee’s 1% 90-day NPL holds as it pushes into Brazil.
SOFTWARE
- ACN 16% led the way today after beating on the back of expectations which were about as low as they get. Co beat the high end of its F4Q guide (revenue $18.68B, +7% LC vs. $18.04B Street), bookings swung back to growth ($22.17B, +5% LC after -3% last quarter) and the FY27 guide of +3-6% LC bracketed the Street; the stock traded as high as +24%. JL in TMTB Slack here: "Numbers were better than expected but there's a LOT of short covering," and the IT services complex went with it. The incremental SI datapoint: FY26 bookings from emerging SI/data partners tripled and that revenue doubled, with >400 clients starting advanced SI work. That helps bulls who argue AI creates new work faster than it deflates the old (the long-term debate); bears will point out the FY27 guide includes 2-2.5pts of M&A, leaving ~2.25% organic growth at the midpoint and that CEO is assuming "more of the same" in 2027 IT budgets, with clarity only in January/February.
- U +6.5% continues to act better as third-party checks continue sound positive, setting up for another large beat and raise (some checks flagged by Windsurfing in TMTB Slack today) Helps bulls who think Vector’s Q2 step-up to ~23% growth from four straight quarters of ~15% wasn’t a one-off. Remember, this stock is a bit crowded on the HF long side (doesn’t mean it can’t work; we still like it), and buyside now expecting another significant acceleration vs. guide which implied a decel ~20%.
- APP -3.1% on the other side of that following through on the negative Wells Fargo note yesterday talking down e-comm: a check we heard has APP tracking low 20s in Q3 vs. a high 20s plan, with FY27 at HSD now that non-gaming onboarding is done. Judge denied AppLovin’s emergency request to block Unity’s Ad Quality SDK from collecting data on AppLovin ads, a win for U. AppLovin had sought to halt the data collection within five business days and force SDK changes within 30 days, but Unity can continue operating as usual for now. The broader legal fight continues. Tough stock right now and the L U/S APP pair back in full force among pods.
- GTLB +5.7% as BofA came away more constructive on Orbit/Flex: 90%+ gross retention supports the seat base and FQ2 bookings growth improved ~1pt to 15%, though the usage products’ monetization is unproven.
- DT +2.6%: UBS checks with four F500 Arize customers see AI observability reaching 20-25% of observability spend, worth ~3-4pts of growth.
- APPS +4% as RBC started it at Outperform.
- TTAN +2.4% as MS’s survey of 1,017 trades contractors found 61% already using AI but 58% with little or no trust in it, which it reads as favoring TTAN’s embedded, vertical approach and outcome-based pricing.
- MDB +89bps as RBC’s MongoDB.local checks found consumption improving with AI tooling and agentic workloads moving past RAG into live deployments; Postgres rarely came up.
- MSFT flat even as Wells sees FQ1 Azure at ~46% cc, >1pt above the 44-45% guide (early bogey probably closer to 47%), with Copilot checks improving.
- ORCL +58bps: FT reported Tencent signed a five-year, ~$7B lease across ORCL’s Southeast Asia data centers for ~100,000 chips, ~30% paid upfront; Mr. Alpha in TMTB Slack said it all: “lol ORCL can never catch a bid.”
- TEM -6.6%: no news, and it fell despite Guggenheim raising its target 42% to $92
- WDAY -1.9% reversed from +2.5% at the open, which came on its 8-K announcing ~2.5% job cuts (mostly Product and Technology) and $65-80M of charges.
ELSEWHERE
- TTWO -1.9%: Hearing Yipit was out with initial weekend sell-through tracking in the low 20Ms, in line with previous notes.
- AAPL -81bps with two notes out this morning: Needham argued META’s 0% Muse Connectors fee challenges AAPL’s 15-30% App Store take (20% of App Store revenue migrating = ~$10B of revenue/~$7.5B of EBITDA), and MS trimmed its target as lower new-iPhone pricing pressures ASP and GM. The memory squeeze is spreading in handsets too: Samsung is raising Galaxy S26 prices ~$110 in Korea seven months after launch (DIGITIMES).
- HPE +1.1% added to yesterday’s +4% as the Street raised numbers after Networking Day: MS took FY27/28 EPS up 3%/10% to $5.10/$5.76 (11-13% above the Street), while UBS flagged limited surprise with the buyside already at ~$5.00+. Bulls say 15-18x FY29’s $6.25+ = $100+
BULLISH AND BEARISH WEEKLY OPTION FLOW

Source: RunningoftheBulltards