2026.10.05 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
Good afternoon. QQQs +88bps in a steady grind higher and closing just off the highs even as the long end backed up again.
In Tech, Software +1.2% led as Schneider's $205/share cash takeout of PTC put a floor under vertical software (ADSK +4.5%; TTAN +7.6%) and the agent/e-com/cyber names kept chugging along (SHOP +5.8%; NET +3%; ZS +2.6%; OKTA +3%, etc.).
Semis +10bps lagged with megacap AI up and most everything else down: AVGO +2.1%; NVDA +2.1% worked after Morgan Stanley said both are shielded from the AI power crunch, the latter hitting new ATHs while the neocloud/BTM complex reversed early gains (NBIS -4.2%; WULF -4.5%; IREN -3.1%; CRDO -2.8%) and INTC -2.6% held most of its gap-down after Musk confirmed TSM talks on Terafab. HDDs bounced off Friday's Toshiba gap-down (WDC +6.3%; STX +4.5%) as sell-side was out in full force defending and CBRS +9.1% kept bouncing after Altman called it a close partner and sell-side defended.
In macro land, the long end kept leaking higher. The 10Y touched ~5.35%, the highest since 2002, after a roughly in-line ISM services print (54.9 vs. 55.4 in August) with prices paid up to 74 from 72.6, then gave back half as stocks ramped: 10Y +3bps to ~5.31%, 2Y flat at ~4.84%, another steepener. Fed pricing kept cooling after Friday’s soft payrolls (+29K vs. ~85-90K expected): odds of a hike at the 10/28 meeting are ~21%, down from ~30% Thursday and 70%+ early last week, though markets still lean toward one more hike by December (~75). Crude -2.3% to ~$89 WTI with no obvious headline and BTC +35bps to ~$85.7K. FOMC minutes and the 10Y auction Wednesday, 30Y Thursday.
Let’s get to the good stuff…

AI/SEMIS
- WDC +6.3%; STX +4.5% bounced off Friday's ~10% Toshiba gap-down with the Street out in force. Bulls had a whole long list of things to push back on. Take a deep breath: 1) $380M isn’t a huge investment for this industry, and some likely goes toward equipment upgrades, testing and next-gen technology, not just new supply; 2) Toshiba's datacenter drives are 1–2 generations behind STX/WDC, still on 26/28TB CMR, with 40TB+ HAMR not expected until CY28 at the earliest; 3) the headline is a 2x increase in exabyte output at the Philippines facility, which is only ~2/3 of Toshiba’s base. On a total-company basis that implies closer to ~70% EB growth, roughly in line with STX/WDC, while unchanged unit forecasts are only low teens in FY27 and mid teens in FY28. Higher-capacity drives also mean “doubling capacity” does not mean twice as many drives; 4) Toshiba relies on TDK for heads, Resonac for media and Hoya for substrates, creating supply gates. We’ve heard Resonac is supposedly sold out through late CY27/CY28; 5) Toshiba has already pushed out its LSD million drives/quarter target because of yield issues 6) even if Toshiba doubled from ~200EB versus ~1,000EB each for STX/WDC, it only adds roughly 10% to industry supply, similar in absolute EB terms to what STX/WDC themselves are adding; and 7) the ’28 supply gap likely remains wider than Toshiba’s incremental capacity. Bulls will therefore frame this as a gradual expansion/upgrade that isn’t unexpected, not a major change in industry supply, while the recent STX/WDC underperformance (despite very strong pricing checks) suggests some of the Toshiba news was already circulating among Asia investors.
- To us, this discussion feels similar to the Chinese supply debate for the memory guys: announced capacity isn’t the
same as bits hitting the market. Still, memory names have largely already digested the Chinese supply risks which is partly why stocks have pulled back and already trade at mid single digit multiples. Similarly, the headline here was much worse than the likely fundamental impact, but unlike memory, the bear pushback is HDD multiples haven’t already discounted the risk and still trade at double digit P/Es. Any new entrant trying to gain significant share into an oligopoly will likely use price as a negotiation tool, and this likely gives hyperscalers leverage as they negotiate ‘29-’31 contracts.
- Memory lagged: MU -1%; SNDK -92bps; SKHY flat
- TSM +2.8%; INTC -2.6% on Musk confirming TSM is in discussions to join Terafab (”Just discussions, but something may come of it”), with DIGITIMES, citing Culpium, reporting suppliers now see >80% odds of a TSM-Terafab deal in Texas here. Funda’s had some good thoughts saying INTC’s Terafab role is technical support and IP licensing, separate from its earlier report that INTC would foundry AI chips for TSLA.
Arun Dhar argued here in Slack that nobody close to INTC read April’s 14A news as more than licensing plus engineering support on a 2028/29 timeline, and the LBT-CC Wei cross-licensing gives Musk a free option on both; John countered that foundry orders may not come until mid-2027.
- Anthropic: The Information reported at 2:15pm that META and MSFT, two of its biggest corporate customers, are working to wean staff off Claude: MSFT cut its projected internal Claude spend to under $700M from at least $1B, steering employees to fewer Claude queries and its own tools. Stocks mostly shrugged (MSFT +1.5% off a +2.9% high; META +1.9%) and so did TMTB Slack here: MyNameIsJeff called it a “janky article,” noting it has MSFT moving some of that spend to OpenAI, while consensus was that it’s Anthropic-specific challenge rather than an AI-trade one.
- OpenAI: OPENAI IN TALKS WITH UAE FUNDS, BLACKROCK FOR $30 BILLION ROUND
- Big day tomorrow for MRVL -38bps with the investor day: JPM’s preview has FY29 custom silicon at ~$12.5B vs. the Street’s $10.3B (the GOOGL XPU attach isn’t in numbers) and FY29 revenue ~$30.3B vs. $26.4B. In TMTB Slack here, Ash noted Funda’s F27/F28 numbers sit well above consensus and hoped the stock not trading well into the event means positioning is cleaner, while trmn pointed out it still ran +25% in September.
- AVGO +2.1%; NVDA +2.1% worked after MS said both are shielded as the AI power crunch hits the chip supply chain. AVGO also had UBS’s TPU checks making the rounds, saying AVGO stays engaged beyond v8i, with a new 3nm multi-chip design driving most 2028 volume and a 2nm v10 that could take the lion's share of GOOGL TPU volume in 2029:
Dr Vinnie Boombatz
@halfblindmonkey
$AVGO strong positive read-through from UBS TPU checks: UBS says $AVGO remains deeply engaged beyond v8i, with a new 3nm multi-chip design expected to drive most 2028 volume, followed by a 2nm v10 that could take the lion’s share of Google TPU volume in 2029. v10 seen using up …

12:30 PM · Oct 5, 2026 · 71.5K Views
4 Replies · 15 Reposts · 106 Likes
That helps the AVGO bulls who see the GOOGL TPU franchise intact into 2029 (the long-term bull case), and pushes out the bear worry about MediaTek gains at GOOGL.
- CBRS +9.1% kept bouncing after Altman called CBRS a “close partner” with “deep engagement,” with Mizuho (fast inference a ~$550B TAM by 2030 at ~6-10x standard token pricing) and Barclays defending and Morgan Stanley calling it the clearest AI memory-bottleneck beneficiary. Gavin Baker’s post was getting a lot of play: the HFT and cyber wars of 2027 get fought with low-latency SRAM chips (Groq 3 LPX or CS-4) in disaggregated setups with Rubin, with Jane Street reportedly paying $200M per MW:
Gavin Baker
@GavinSBaker
More probable: The high frequency trading and cyber wars of 2027 fought via low latency SRAM chips, whether Groq 3 LPX or CS-4, in disaggregated setups with Rubin. Jane Street reportedly paying $200 million per mw - $200b per gigawatt - is likely the beginning, not the end.

Sholto Douglas @\_sholtodouglas
the high frequency personal agent wars of 2027, fought via low latency chips and rack placement next to the servers hosting Resy and SF tennis court systems
2:23 PM · Oct 5, 2026 · 129K Views
40 Replies · 55 Reposts · 1.03K Likes
The pushback we heard is some saying that the fast-token premium will continue to compress from ~10x early this year to 20-30%, heading toward zero as “every token will be a fast token.” Bears will say if buyers care more about token cost than speed, fast tokens won’t command much of a premium, shrinking the TAM.
- The neocloud/BTM complex reversed early gains: NBIS -4.2%; CRWV -2.5%; WULF -4.5%; IREN -3.1%. They opened green on Goldman raising its YE26 US data-center capacity forecast by 5GW to 64GW, and WULF even announced a Kentucky Power agreement doubling contracted power at Muskie to 1GW. K asked in TMTB Slack here whether it was regulatory news or rotation into the hyperscalers; AG415 floated the SPCX angle, “marginal compute seller getting whacked,” as SPCX +7.5% after Jukan posted that 60% of SPCX’s 10GW goes to its own demand and only 40% to external customers, citing a 3p check from Wukong:
Jukan
@jukan05
Apparently 60% of $SPCX's 10GW goes to its own demand, and only 40% is for external customers. Could it be because Grok Bot has been a hit?

12:42 AM · Oct 5, 2026 · 214K Views
49 Replies · 30 Reposts · 527 Likes
- CRDO -2.8% faded an early +1% to as much as -5.8% with no news (members were asking here). We heard Bluefin was out today saying CRDO working closely with NVDA to qualify 800G ZF module for neoclouds. Bulls say that the CPO-cannibalization worry is overdone: NPO ramps next year and XPU scale-up CPO looks like a 2028 story, and both come on top of pluggables. OCP is 10/12.
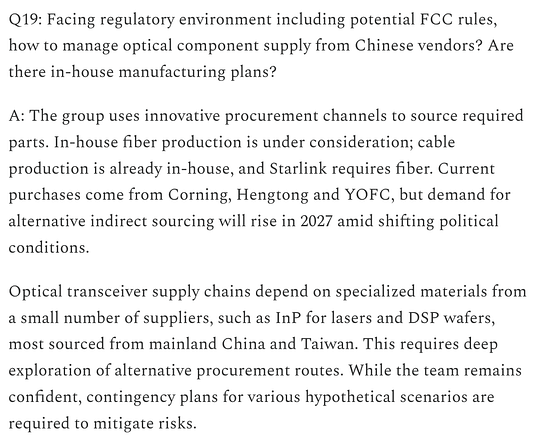
- GLW -2.9% with chatter that SPCX is weighing in-house optical fiber production (its cable is already made in-house; fiber is bought today from GLW, Hengtong and YOFC), flagged by Jukan Sunday night, referencing same 3p SPCX check from Wukong:

Jukan
@jukan05
WTF. SPCX is developing its own optical fiber too?
Jukan @jukan05
Apparently 60% of $SPCX's 10GW goes to its own demand, and only 40% is for external customers. Could it be because Grok Bot has been a hit?
12:48 AM · Oct 5, 2026 · 75.3K Views
43 Replies · 50 Reposts · 935 Likes
- VST +3.5% on a DOE conditional loan commitment of up to $4.2B for uprates at Beaver Valley and Davis-Besse/Perry: 433MW of new nuclear capacity, ~4GW of baseload preserved and 20-year life extensions. The debate we’ve been hearing is that the IPPs are de-rated on politics more than fundamentals and there has been no large developer-to-IPP data-center PPA since January, Texas permits paused until an ERCOT audit due 12/10, and FERC rules on PJM large loads 10/12.
- AMD -34bps with Lisa Su in Taiwan hunting packaging and substrate capacity. Good color on that bottleneck from Terminal Junkie's Kinsus meeting in TMTB Slack here: high-layer-count ABF is the tightest part of the market, equipment lead times are >12 months, and the base case is ~30% higher 2027 substrate pricing (materials +15-20% plus a ~15% capacity-driven hike in 2H27), with a 100% hike unlikely. The AMD angle: Kinsus sees NVDA's CPU as its key growth driver into 2026-27, with potential share gains vs. AMD/INTC.
- QCOM -2.2%; ARM -1.5% with their five-day Delaware jury trial underway: QCOM is seeking up to five years of royalty relief and the judge is weighing whether to strike that remedy.
- GFS -3.2% on BNP’s downgrade: the bull case increasingly rests on SiPho scaling from ~$400-500M this year to a ~$1B run-rate before 2028.
INTERNET
- SHOP +5.8% led today. We thought Piper had one of the most bullish notes we’ve heard re: SHOP and agentic, and accelerating migrations is an interesting side effect of agentic adoption:

TikTok launched a “Direct Checkout” to buy from brands inside the app plus an AI Shopping Assistant, built with SHOP, CRM, Shoplazza and Stripe (per Adweek). Cleveland was out saying agentic transactions ran 2x YTD volumes in Sept. And Tobi was out tweeting reminding investors of the potential share gains SHOP could get from agentic commerce while AMZN still figures things out:
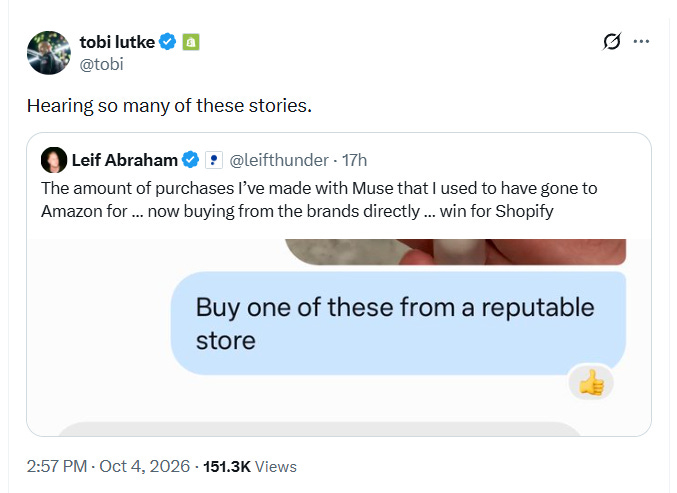
Good discussion in TMTB Slack here on the name today with Ummera framing it as “by far the cleanest internet winner” and we said something similar in our weekly yesterday. SHOP had a rough start with the consumer agentic narrative, but investors have come around to the view that is likely one of the best ways to play the theme, especially since stock has underperformed YTD (flat) and is flattish since the Instinct/Muse stuff took hold. We think SHOP wins in almost every agentic scenario, with multiple vectors of demand. Something like an eventual 30% agentic/70% non-agentic e-comm split would fall in SHOP’s sweet spot: they benefit from rising frictionless GMV spend on one side and on the other, brands face more pressure to make their own checkout as frictionless as buying through an agent. That makes Shop Pay’s conversion lift more valuable, not less, as merchants compete to keep customers buying direct.
We had Claude make us a handy graphic laying out the different Agentic outcomes:

Interestingly 3p data has accelerated on SHOP the past few weeks since the Muse release. We think it’s too early to attribute the latter to the former, but something to continue to watch. Numbers set up here decent as street expecting a decel into low 30s GMV the next couple quarters on easier comps but buyside expects have been moving up as of late. Overall, we think multiple ingredients here for a good long, but consumer agentic is early so we stay on our toes on shifting narratives.
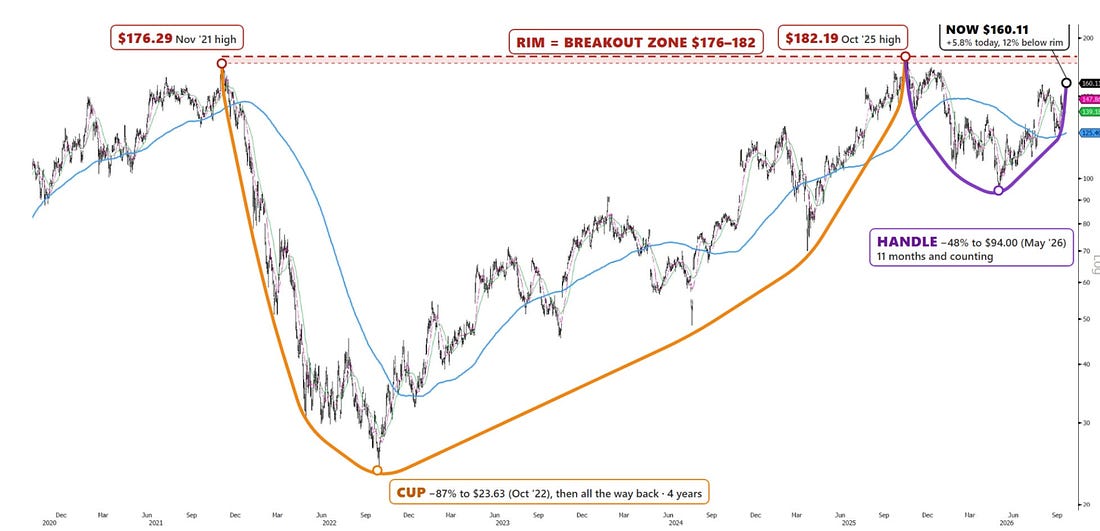
Finally, I really love the long-term chart here. These setups where a stock repeatedly fails at the old highs but keeps building a bigger base underneath have worked across numerous names. Once that ceiling finally breaks, there’s very little overhead supply. We had Claude annotate it for us, but it came out looking more like a kid’s drawing than a cup and handle. To be fair, that's how most technical analysis looks to the fundamentals crowd:
- MELI +9.7% led Internet, extending a +4.6% open after Flavio Bolsonaro beat Lula 47-45% in Sunday’s first round, sending Brazil to an Oct. 25 runoff (NU +13%). The market had converged on Lula winning round one by 2-3 points, with a Flavio first-place finish seen as a <10% scenario; every first-round winner since 1989 has gone on to win the runoff, 18 of 27 states went right (capping fiscal downside even if Lula wins). MELI has been used as a funding short so positioning not crowded at all.
- China ADRs bounced with the mainland shut for Golden Week (GDS +6.2%; VNET +6.1%; BABA +4.7%; BIDU +3.2%)
- META +1.9% with ad checks still improving: DB had META growth accelerating ~200bps this morning (its PINS +4.2% checks improved too). Other checks in general have been positive here too. Main pushback from investors right now is on on costs, with 2027 expenses seen MSD above the Street and capex $250B+ on the Muse ramp.
- Some good discussion in TMTB Slack here around OpenAI’s Dots vs. Muse, after Ash called Dots “very slow” and “not a serious product at this stage,” with META “king of the agents for now.”
- pricedin disagreed: uses Dots heavily for normie tasks, work and some Codex as a PM, but hasn’t been able to do
that with Muse, where engagement has been poor.
- bretzel landed on Dots as a chief of staff/PM (”I can’t keep all the threads in my head but it sure can”), and
Ash agreed, adding Muse is very good at synthesis but isn’t integrated with Codex.
- ACF made the case for Muse as the “superior normie product”: it logged into a utility website and pulled property
taxes through multiple browser steps on the first try where Gemini couldn’t log in, and it connects as many email accounts as you want.
- CART +3.2% as Wells sees the 4Q EBITDA guide ~140bps ahead of consensus with ads accelerating to +16.5% (vs. +15% consensus), and RJ argued the market is overlooking embedded agentic tailwinds (Clementine agent, Cart Assistant).
SOFTWARE
- Vertical software ripped on Schneider’s $205/share cash takeout of PTC (PTC +33.5%; ADSK +4.5%; TTAN +7.6%; PCOR +6.3%). Details: $23.7B, a 42% premium and Schneider’s largest deal ever, for a company guiding up to $2.75B of 2026 revenue (~8.6x sales). The math investors focused on: PTC went for ~22x EV/CY27 FCF, which puts a much-needed floor under vertical software since every name outside EDA trades below that, and ADSK sat at an ~8-turn discount at Friday’s close.
- Cyber caught a bid (what’s new?) into ZS’s investor day tomorrow (ZS +2.6%; NET +3%; OKTA +3.2%). JPM framed it as the first real AI-monetization sizing event, since the FY27 guide excludes Security for AI (six products, >$100M of LTM bookings) and Agentic SOC. The bar we’re hearing is pretty low but reiterating guide is a must.
- CRM -2.1% lagged even as a named partner on TikTok’s agentic checkout, while
- MSFT +1.5% had Melius upgrading on AI fears pushing enterprises toward a trusted layer. A check we heard lines up with that split: buyers are funding cyber (and hardware) by trimming big ERP, database and CRM renewals, with MSFT carved out.
- U +4.7%; APP +5.1% both worked despite being a popular pair. U checks continue to sound strong and buyside expects creeping up -- Piper’s checks this morning (SDK net adds passing APP for the first time in 2+ years).
- IOT +3.1% on Jefferies’ initiation: asset-based pricing limits seat-displacement risk, with ~22% revenue CAGR through FY29 on ~1% penetration of a ~$175B TAM.
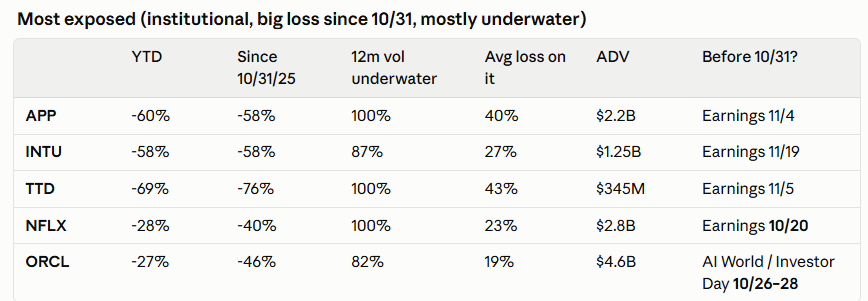
- Reminder: October usually brings heavy tax-loss selling in the internet/software losers. Our screens:
ELSEWHERE
- High-beta fintech strong: UPST +6.8%; AFRM +5.6%
- DKNG +5.4% on BofA’s upgrade to Buy after a ~47% one-year drawdown with estimates bottoming. Bulls will say prediction markets are a win-win from here, since if they stay DKNG is already #3, and if they go away the terminal-value overhang lifts.
- · P +2.7% after Evercore’s CTO meeting: enterprise AI should expand storage demand as on-prem inference and agents scale, hyperscaler wins have visibility into CY28, and management sees NAND pricing as manageable.
- · AAPL -24bps: JPM’s tracker has iPhone 18 Pro lead times down 6 days w/w to 17, already below the 17 Pro and 16 Pro at this stage (China Pro down to 18 from 26 days), with the 10/16 Duo pre-order the real test of mix.
BULLISH AND BEARISH WEEKLY OPTION FLOW

Source: RunningoftheBulltards