2026.10.06 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
Early one today as I need to head out shortly. QQQs +61bps as of 2pm ET, after the S&P and NDX both tagged fresh record highs late morning before fading as crude bounced off its lows; small caps lagged (IWM -62bps; ARKK -1.8%). Software +1.2% outpaced semis +67bps, with cyber leading again (ZS +3.6%; PANW +3%; FTNT +3%; CRWD +2.5%) on ZS’s investor day and more AI-enabled breach headlines. The quiet semis tape hid a big rotation inside AI infra: optical/networking and power ripped (CIEN +12.4%; GLW +6.8%; NOK +6.9%; ALAB +7.4% on MRVL’s investor day read-through; VST +11.2%; GEV +5.4%; BE +4.3% on GOOGL’s 3.6GW CEG deal), while storage, memory and semicap got hit (STX -9.4%; WDC -7.2% extending the TDK-heads selloff; SKHY -4.2%; LRCX -3.6%; TER -3.1%). MRVL +5.5% itself gave back some of an early +11.1% pop after some ambitious LT targets at their analyst day.
Lots of dispersion across all sectors right now. We think that' is leading to scarcity premium on good clean narratives (hello SHOP). Outside of the catalyst driven trades (CPUs, Optical in conferences, etc.) where we have gotten confidence to size up, we’re finding it helpful to use charts as a guide to see where to move our feet in semis…
Haven’t seen this level of dispersion in AI semis in a long time:
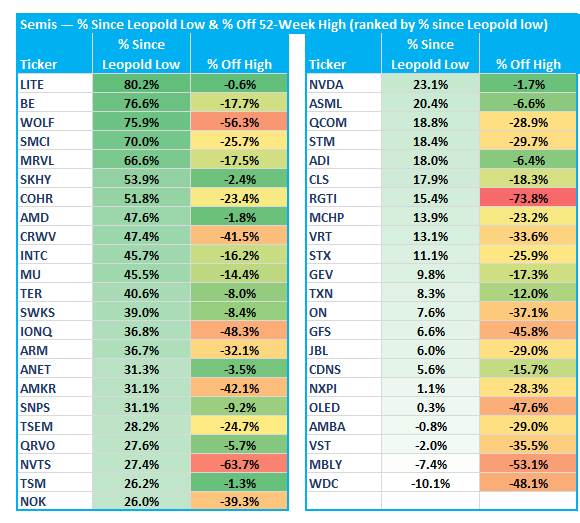
Despite dispersion, semis in generally getting healthier as a whole:

Our view from our weekly Sunday:
The reason we’ve stuck with our choppy but upwards trending call is that we’ve felt AI semis were still trading under several unresolved overhangs and debates that needed to clear: 1) Frontier ARR trajectory; 2) Gap between open source and frontier model capability; 3) Power supply gap in ‘28; 4) Next use-case beyond coding to drive compute; and 5) SI safety and public sentiment heading into midterms.
We think all 5 debates have improved in favor of the bulls over the last several weeks, significantly improving the near/medium-term narrative…(TMTB: more detail in the full weekly )
We still think dispersion is here to stay, and we’re not going back to the go-go days of April through June when a rising tide lifted almost every boat in a vertical line. But the setup feels healthier: leadership is broadening without becoming indiscriminate, and with the overhangs clearing, we think good idio names have a clearer path to working.
So far so good….
In macro land, the long end got a breather. Yields eased intraday (10Y -3bps to ~5.28%; 2Y -2bps to ~4.81%; 30Y -2bps to ~5.65%, a day after hitting the highest since 2002) as Le Pen’s deficit plan rallied European sovereigns and Bessent said the US can bend the debt curve “very quickly.” The 3Y auction stopped through by 0.2bp despite light indirects. Fed pricing barely moved: ~20% odds of a hike on 10/28, vs. ~21% yesterday and 70%+ early last week, with roughly one more hike priced this year and two in 2027. WTI ~flat near $89.5 after trading -2.9% at the 8:20am lows (SHEL’s CEO put Gulf flows at 80%+ of prewar levels). BTC flat at ~$85.6K.
Let’s get to the good stuff…
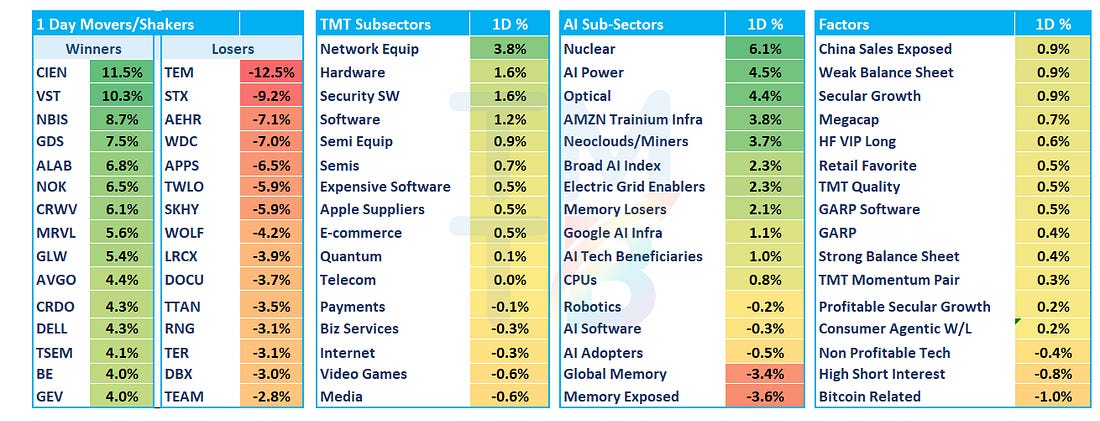
AI/SEMIS
TMTB Slack
- STX -9.4%; WDC -7.2% extended this morning’s -2-3% into a much bigger drop on Bloomberg’s report that STX and Toshiba are vying for TDK’s HDD-head business (Toshiba disputed it). One of the bullish pushbacks yesterday was that Toshiba depends on outside suppliers and therefore cannot ramp freedly; bears will take this news as Toshiba getting serious; Ardo in TMTB Slack here: on Friday the HDD defenders asked where Toshiba gets the components, “well, that’s how.” Bears will also say Toshiba ownership could therefore create concerns around supply allocation and component pricing, not just stronger competition in finished HDDs. Bulls will say Toshiba already buys most of TDK’s heads, WDC has locked up a material chunk of TDK’s 2027 capacity, HAMR also needs glass media, and some doubt the deal closes at all since Toshiba doesn’t need that volume of heads & potential regulatory issues might be a roadblock.
- Memory lagged again: SKHY -4.2%; SNDK -1.7%; MU +21bps. Korean chatter is similar to last quarter where mgmt making the sounds on the sell-side saying SKHY’s Q3 OP will land below the Street on an FX hit (MSD-HSD off ASPs) and that 2028’s wave of new clean rooms makes the out-years hard to underwrite; Korean money rotating to CCL, ABF substrates and MLCC instead. Bernstein had a positive note on pricing saying DRAM contract prices rose ~20% q/q in 3Q26 and could rise another 10–15% in 4Q while saying NAND wafer pricing remains softer, but enterprise SSD/mobile NAND rose ~20% q/q and TrendForce now sees 4Q NAND +15–20%, above Bernstein’s estimates. Nanya and Winbond printed record Q3s overnight with Nanya filling only 50-60% of demand and JPM’s MU IR call has CY27/28 bit deficits near 19%/15%. MU also settled the Netlist dispute for $600M. Overall, the debate here remains a push and pull between bulls and bears — we’ve covered it extensively. As Akh put it in TMTB Slack here re: memory: “Just not the flavor of the moment”
- MRVL +5.5% (up as much as +11% but fading) at its investor day: FY28 revenue is now ~$20B (from $18B, vs. a Street at ~$18.2B), with $70-90B by FY31 and a ~$400B AI TAM by 2030 (custom $235B, switching $85B, interconnect $65B), 4x+ its prior $94B 2028 estimate. The FY29 custom target went to >$12B from $10B+, custom silicon is now shipping to all four top US hyperscalers, and the FY31 model’s 56-59% GM and 44-46% OM get you to $30+ of EPS, <10x at ~$285. This helps bulls who wanted the investor day to bridge the GOOGL program and scale-up optics through FY29+ (the long-term case); bears will say $70-90B needs every milestone to land, the same back-end-loaded math behind the $120B GOOGL deal. With the stock fairly crowded into the event, most in Slack read the fade as sell-the-news.
- ALAB +7.4%; CRDO +4.4% traded as MRVL sympathy on the connectivity TAM.
- CIEN +12.4%; NOK +6.9%; GLW +6.8%; TSEM +5%; LITE +3.9%: optical strong on MRVL read-through. No CIEN-specific news, but MRVL sees its scale-across (coherent) revenue going from ~$500M in FY26 to "safely above $1B" in FY28 and >3M coherent pluggables by CY30, a big number for the inter-DC build where CIEN claims ~70% share of line systems. CIEN and NOK charts here looking a lot better here playing some catch up as LITE continues to rip to ATHs.
- AMD +3.6% kept going after Lisa Su told Reuters AMD plans to "substantially increase" supply in 2027, including securing memory, with Citi (CPU TAM to ~$300B by 2030) and Mizuho (~$209B) out with agentic-CPU math, and Susquehanna's Q3 laptop model-share tracker showing AMD +3.1pts to 29.3% at INTC's expense (INTC -1.2%).
- AVGO +4.7% outperformed as investors digested the FT’s details on the record $60B financing for Anthropic’s 2027 TPU orders (AVGO backs the $42B of senior loans; the $18B junior tranche carries no AVGO guarantee) alongside MRVL sizing the custom-silicon TAM at $235B by 2030. The pushback we’re hearing on the guarantee worry: it’s “a pretty small piece,” and positioning is still washed out (”everyone’s pretty negative”).
- NVDA +50bps more ATHs.
- NBIS +9.2%; CRWV +6.2% as GPU pricing keeps firming: SemiAnalysis’ B200 1-year contract index spiked to ~$6/hr/GPU this month from ~$5.5 in August and ~$4 a year ago

Jukan ✈️OCP 2026
@jukan05
B200 prices are skyrocketing 👀👀

1:33 PM · Oct 6, 2026 · 75.8K Views
28 Replies · 66 Reposts · 649 Likes
WSJ reported Lambda is raising $4B in a final pre-IPO round with backlog up to $50B from $15B in June. That helps NBIS bulls who deliberately left planned 2027 capacity unsold, betting on firmer pricing (the short/medium-term bull case as their contracts more exposed than CRWV’s)
- VST +11.2%; GEV +5.4%; BE +4.3%: power is back in favor. VST traded with CEG on GOOGL’s 3.6GW deal, on top of the DOE’s $4.2B conditional loan for 433MW of VST uprates announced yesterday. MS’s new BE primer sizes a 76.5GW US data-center power gap through 2029 and argues grid power effectively costs $323/MWh once you count stranded compute, vs. $131/MWh for BE’s fuel cells. BE chart looking juicy here if can break through $300 for what is one of few ways to play the BTM/power gap theme in semis

- AEHR -5.7% reversed from an early +3.4% after TER's 9am release added burn-in to its Titan HP tester for AI data-center chips, pitched against "dedicated ovens"; the pushback is that it overlaps with AEHR's package-level Sonoma rather than its wafer-level FOX-XP

Tweets:

ryanlstevens12
@ryanlstevens12
Firms are switching AI providers at the highest rate Ramp has seen. The monthly share of businesses switching their top model provider reached nearly 8% in September, measured as a three-month moving average. We last saw comparable switching when Anthropic launched Opus 4 and …

3:23 PM · Oct 6, 2026 · 37.3K Views
1 Reply · 2 Reposts · 15 Likes

Deirdre Bosa
@dee\_bosa
XNRGY founder and CEO Wais Jalali on data center jobs: Electrical engineer: $100k a few years ago → $500k now Plumber: $65–75k → $300k (& they’re getting poached by nearby sites) The other AI talent war. From @dottkhan Khanference
5:06 PM · Oct 6, 2026 · 2.03K Views
2 Replies · 3 Reposts · 25 Likes

Similarweb
@Similarweb
Top 10 websites by total visits in September 2026: → WhatsApp and TikTok both moved up a spot, while Bing dropped two spots. → ChatGPT recorded the largest growth and was the only website to grow by more than 1% for the second month in a row. similarweb.com/website/?utm\_m…

2:02 PM · Oct 6, 2026 · 3.47K Views
4 Replies · 6 Reposts · 41 Likes
INTERNET
- SHOP +3.1% continues to trade well on JPM's agentic-commerce note (bull case to ~30% '27 growth, with Shop Pay preserving payment economics as AI traffic converts better). UBS hosted a lunch in Canada talk around the table was +ve. From a friend who attended: Canadian community is sleepier generally and not fully aware yet of recent sentiment transition branding SHOP as a AI winner, which creates a tidal wave of demand as they move to overweight on canadian mandates
- META +12bps: the incremental datapoint was TD Cowen’s 3Q agency checks:

Kaushik
@WisemanCap
$META TD Cowen BUY, PT $865 - 3Q26 agency spend at Meta: +17% y/y (vs +11% in 2Q) on a tougher comp. - Impressions +2%, pricing +14% — strongest pricing since 1Q22. - Core Facebook: +16% (pricing +24%, impressions −6%). Instagram: +18% (impressions +17%, pricing +1%). - This…
1:06 AM · Oct 6, 2026 · 12.5K Views
3 Replies · 9 Reposts · 138 Likes
Checks have sounded good so far which helps bulls betting on a Q3 at the high end of the guide (the near-term #s bull case); bears’ bigger worry is still the 2027 opex/capex reset, with Wells now modeling FY27 opex at $210-215B vs. the Street’s $202B on Muse.
- ABNB -2.7%; EXPE -1.4%; BKNG -1.5% sold off into the afternoon while hotels rallied (MAR +1.1%; HLT +1.7%): the agentic-disintermediation trade again with no fresh headline although some pointed to the Steve Eisman podcast talking about OTA disruption. Our own n=1 check, shared in TMTB Slack here: we’ve been using Muse and Codex more for travel listings and getting a lot more direct exposure than ever before, where we’d have just gone to ABNB previously
- GOOGL +29bps: Guggenheim lifted GCP numbers (3Q $29.3B vs. the Street’s $28.6B), and GOOGL pulled Flash and Pro access for free Gemini users, more evidence for SemiAnalysis’ point that subscription limits are becoming a margin lever.
- AMZN +2%: hey it’s up!
SOFTWARE
- ZS +3.6%; PANW +3%; FTNT +3%; CRWD +2.5%: cyber’s run keeps going. ZS reaffirmed guidance at its investor day (FY27 ARR $4.40-4.43B, ~+17%; FCF margin 23-23.5%) and added a $10B long-term ARR target with no date, but faded from +6.8% as investos did the math: at ~17% growth, $10B doesn’t arrive until early FY33. Bears will say a dateless $10B target with no long-term margin framework doesn’t change their mid-teens-grower view (the long-term debate). Breach headlines kept coming too (Dimon told Bloomberg Mythos has driven cyber risk up 10-fold and Korea had their own hacking security issues overnight). Reseller checks we heard have Q2-to-Q3 growth accelerating at PANW (low 20s from high teens) and FTNT (high teens from mid teens) with ZS and CRWD steady, network-security list prices up MSD-HSD in 60 days, and AI SKUs at 10-15% of cyber revenue as new spend; the bear angle is tougher 2H27 comps. AB in TMTB Slack here pushed back on the multiples: cyber is “the few months rental area to be in right now and at 40x revenue, whenever the fall happens its going to be very ugly.”
- HUBS -2%: announced they are cutting ~7% of staff (~660), with $120-150M of gross annualized savings (~3pts of CY27 margin, per Canaccord) and a new 30% non-GAAP op margin target for 2030; mgmt framed it as a flatter org, not AI efficiencies, and reaffirmed guidance. Bears will say this is their long-term case playing out: margins and buybacks as downside protection for a structurally slower and secularly challenged biz.
- TWLO -5.6%: TWLO joined the S&P 500 before the open after heavy index buying into Monday's close, and CPaaS/CCaaS peers slipped with it (RNG -3.1%); HK in TMTB Slack here: "Arb selling after s&p500 add today,"
- TEM -11.6% reversed hard from +5.3% (after +9% Monday on an FDA clearance) as the whole genomics/AI-bio basket unwound (TWST -15.2%; ARKG -7.5%). M in TMTB Slack here called it a blow-off top after the names went parabolic, with China/HK hedge funds heavily involved recently, and Dave here: “If something gets referred to as a bottleneck, from now on that’s your signal to sell $TWST $TEM.”
- SNOW +35bps shrugged off the ASOS breach claim as KeyBanc’s Chicago checks had >40% of customers tracking above plan (vs. 30% last quarter) and CoCo adoption jumping to ~50% of active users from 6%. ADSK +2.3% as Citi’s bus tour found AI conviction strongest among its software names, with organic growth now driven by usage rather than pricing. FRSH +5.5% joins the S&P 600 before Thursday’s open.
ELSEWHERE
- CSCO +3.5% on JPM’s VAR check calling it the biggest networking winner in the strongest enterprise spend setup in years: bookings well above plan, the 2027 pipeline building months early, CSCO security sales up several hundred percent y/y, and AI, security and infra modernization now funded as three separate budget pools.
- AI hardware caught a bid with no fresh news: DELL +4.2%; HPE +3.6%; NTAP +2.5%; P +2.6%. JPM’s Hon Hai note took 2027 NVL72 rack shipments to 90-95K from 75-80K.
- · AI hardware caught a bid with no fresh news: DELL +4.2%; HPE +3.6%; NTAP +2.5%; P +2.6%. JPM’s Hon Hai note took 2027 NVL72 rack shipments to 90-95K from 75-80K
- TTWO -50bps: every day that passes, I get more embarrassed I still own this.
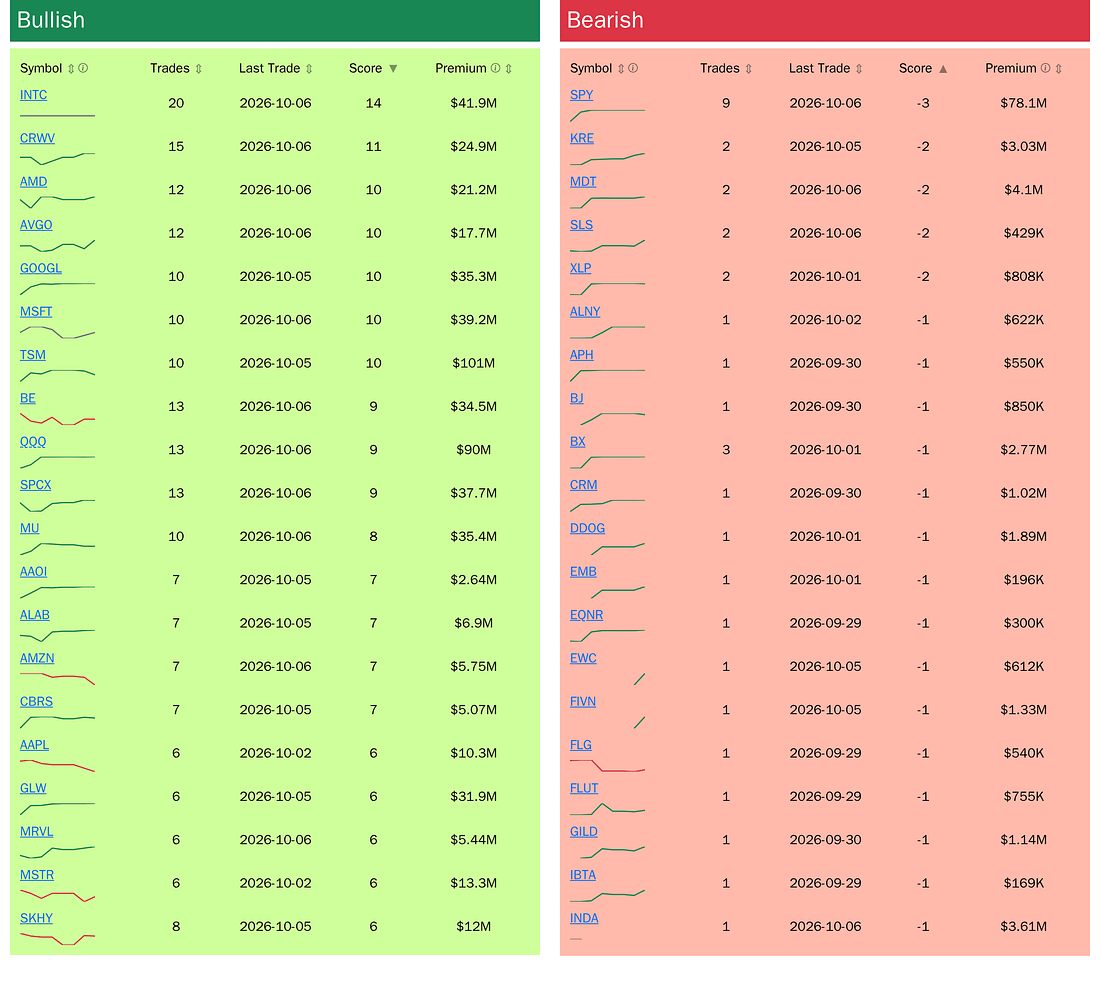
BULLISH AND BEARISH WEEKLY OPTION FLOW
Source: RunningoftheBulltards