2026.10.06 | Substack | Markets | TMTB Morning Wrap
原标题:TMTB Morning Wrap
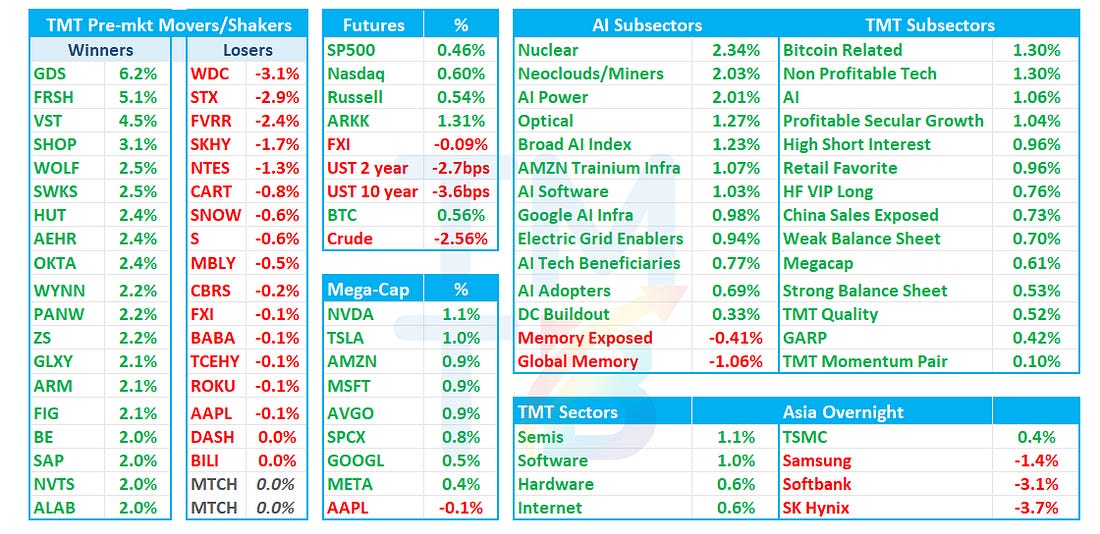
Good morning. QQQs +55bps hitting more fresh ATHs. as bull market vibes begin to creep in. In macro land, rates are getting some relief (yields down 3-6 bps across the curve) as France’s Marine Le Pen’s aggressive fiscal consolidation plan drives a rally in European sovereigns, while Bessent said the US can “very quickly” bend the debt curve. In the Middle East, Oil -2% as exports normalize, Yemen’s Saudi-backed government reportedly recaptured key territory from the Houthis near the Bab el-Mandeb Strait, and Saudi confirmed its East-West pipeline is flowing at 5.8mbd.
In Tech, both semis and software +1%. HDDs -2-3% on news Toshiba/Seagate competing over TDK; SHOP +3% on a positive JPM note; Cyber rallying on reports of hacks in Korea.
Asia mixed overnight: TPX +0.92%, NKY +1.05%, Hang Seng +1%, HSCEI +0.96%, Taiwan TAIEX +0.22%, Korea KOSPI -0.89%
MRVL AND ZS Investor Day today
Let’s get to it…
STX / WDC / TDK: Seagate and Toshiba vie for key HDD head supplier – Bloomberg
Bloomberg reports Seagate and Toshiba are competing for TDK’s HDD magnetic-head business in a deal potentially worth several billion dollars, with Seagate submitting a higher offer after Toshiba began talks. TDK is the only independent head supplier; Toshiba relies on it entirely, including for its HAMR roadmap, while Seagate and WDC use it to supplement in-house output. Toshiba disputed the report and denied a reported meeting.
STX/WDC: Evercore says HDD bottleneck shifts upstream, making vertical integration the key advantage in HDD Deepdive
Evercore argues higher areal density shifts the HDD bottleneck from final assembly to heads, HAMR photonics, media/glass and test, favoring vertically integrated STX/WDC over Toshiba’s merchant-supplier model. It expects 2027–28 shortages to be driven by components rather than drive assembly, while 32TB 10-disk HAMR drives carry ~$190–195 of BOM and 40TB drives should improve cost/TB by ~20%.
AMD: Su plans substantial supply increase in 2027 – Reuters
Reuters reports Lisa Su said AMD plans to substantially increase chip supply in 2027 after raising output this year, citing very high demand over the next several years. During her Taiwan visit, Su said AMD is working with partners to expand both CPU and GPU production and secure memory supply. She said the industry needs more advanced wafer capacity and AMD is now planning three to five years ahead.
AMD: Citi raises PT to $800 as agentic AI expands CPU TAM to ~$300B by 2030
Citi says always-on agents like Muse could drive orders-of-magnitude more compute than chatbots, expanding CPU TAM from ~$29B in 2025 to ~$300B by 2030 (~60% CAGR), with AMD the primary beneficiary and Intel secondary. Citi estimates 100M Muse DAUs could also require ~200–390K B200-class GPUs / 2.8–5.5K NVL72 racks, worth ~$7–19B to NVDA, while rising CPU density creates incremental DRAM/SSD and networking demand; reiterates NVDA Buy/$315.
SHOP: JPM sees agentic commerce driving share gains, outlines bull case to ~30% ’27 revenue growth
JPM says SHOP is well positioned across all three layers of agentic commerce, with Shop Pay preserving payment economics while AI traffic converts better and drives larger merchant sales. Its bull case gets to ~30% ’27 growth via core business, Europe/international, enterprise and offline expansion, with pricing adding ~$90M of annualized subscription revenue; JPM raises 2H26/’27 estimates ~1–3% and sees ~20% FCF margins sustained. Reiterates OW, raises PT to $200 from $185 and keeps SHOP on the Analyst Focus List.
We wrote a little about SHOP in our EOD Wrap yesterday in case you missed it
GOOGL / CEG: Google signs 3.6GW power deal with Constellation – Reuters
Reuters reports Google contracted 3,590MW of power from Constellation in the PJM market. A 20-year agreement covers 890MW of new nuclear output from upgrades to 11 existing units, enabling more than $4.3B of investment, with initial electricity expected in 2028. The remaining 2,700MW is long-term supply not tied to a specific generation source. Reuters notes the deal comes as PJM considers requiring large new users to bring their own power supply or accept shutdowns during periods of peak demand.
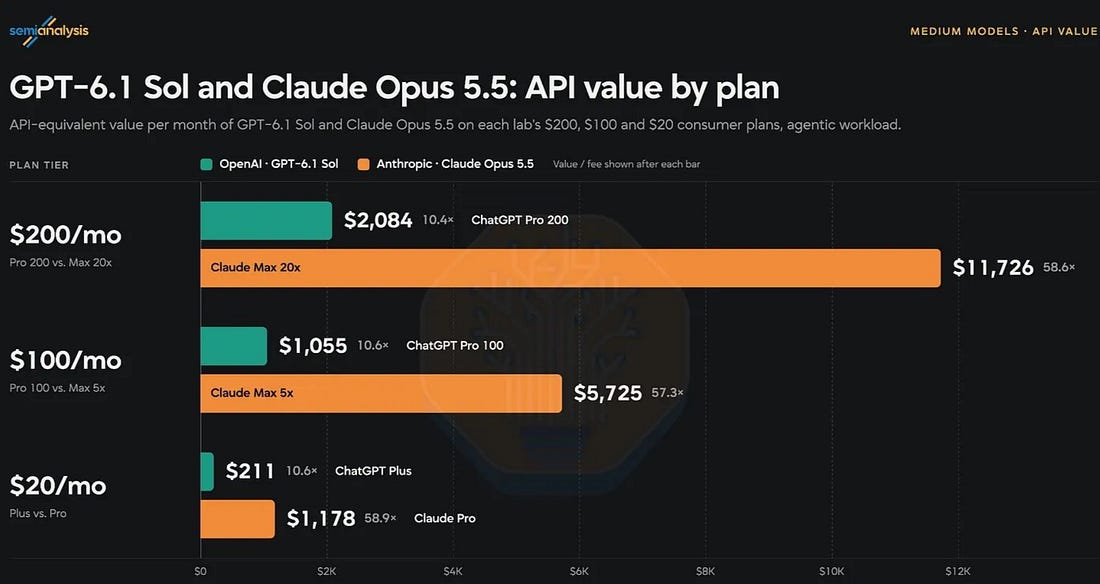
Anthropic/OpenAI: SemiAnalysis says subscription subsidies are a major compute/margin drag, with OpenAI sharply cutting limits
SemiAnalysis estimates subscriptions can consume >40% of inference compute despite being only ~10% of revenue, materially depressing revenue/MW; for Anthropic the hit is ~$36M/MW. OpenAI just halved token limits on its $200 plan and standardized tokens/$ across its $100/$200/$500 tiers, while Anthropic now offers ~4–5x better API-equivalent value on Opus-class usage. The broader implication is that subscription limits are becoming an important lever for labs to improve inference margins, with OpenAI taking the more aggressive path versus Anthropic’s gradual reduction in subsidies.
AVGO / Anthropic: Banks launch $60B chip financing; Broadcom backs $42B – FT
FT reports BofA, Citi and Morgan Stanley began syndicating $42B of senior loans backed by Broadcom as part of a record $60B financing for Anthropic to lease Google TPUs. Another $18B of junior debt carries no Broadcom guarantee; Blackstone has committed roughly $9B and is syndicating the balance. The financing covers Anthropic’s 2027 chip orders, with lease payments starting after delivery. FT also reports Anthropic could issue up to $42B of convertible notes to Broadcom to fund those payments. Junior lenders would bear Anthropic’s credit risk directly
GOOGL: Wells sees TPU sales at $99B/$169B in ’27/’28, but only ~13% GM
Wells raises external TPU deployments to 4GW/7GW in ’27/’28, implying ~$99B/$169B revenue, ~40% of GCP, but just ~6%/~8% EPS contribution given a ~15% licensing markup/~13% GM. The framework has GOOGL buying TPU systems from AVGO at ~$21B/GW and selling at ~$24B/GW, while AVGO ultimately sells to the financing SPV at ~$35B/GW and provides the financial backstop, helping reconcile its higher content/revenue per GW.
Cybersecurity: Korea and Japan breaches spur security-stock rally – FT / Xinhua
FT reports South Korea’s president flagged possible AI use in attacks exposing customer data at seven financial firms. Attackers targeted third-party systems, including a loan-broker portal that exposed about 25,000 Shinhan Bank customers. Xinhua reports separate breaches across Japan potentially affecting millions, including at least 130,000 students and teachers at Osaka Metropolitan University, where a suspected ransomware attack disabled about 500 servers.
SPCX: GS raises CY26–28 numbers, says AI estimates still conservative despite massive capex ramp
GS raises CY26/27/28 revenue to $51.6B/$127.5B/$205.6B from $47.6B/$107.4B/$180.6B and EPS to $1.30/$3.96/$7.01, citing new hosting deals, model improvements and tight compute supply. Terrestrial compute capacity ramps from 2.4GW in 2026 to 7.0GW/10.6GW in 2027/28, but capex of ~$72B/$222B/$193B drives deeply negative FCF, making funding and monetization the key debate. GS maintains Buy/$230 and views AI estimates as more floor than ceiling.
AI SEMIS: Mizuho sees agentic AI driving ~30% of 2030 server CPUs, pushing CPU TAM above $200B
Mizuho says always-on agents like Muse and Dots could drive a major CPU demand inflection as orchestration, tool calls and sandbox workloads increasingly run 24/7, with agentic CPU penetration rising from ~4% today to ~30% by 2030. It models total server CPU TAM growing from ~$68B in 2026 to ~$209B by 2030, including ~$80B of agentic CPUs; AMD is the preferred beneficiary, while NVDA standalone CPU revenue could grow >100% y/y in 2027 and ARM benefits from AGI CPU plus royalties across Vera/Graviton/Axion/Cobalt. Memory also benefits, with agentic AI potentially driving ~18% of NAND demand by 2030. Mizuho raises PTs on AMD to $705 from $580, DELL to $650 from $600, SNDK to $2,050 from $1,875, INTC to $114 from $92 and SMCI to $43 from $35.
MU: JPM management call reinforces much tighter CY27/28 supply, with Nov-Q GM floor + buyback pivot ahead
JPM says after a call with MU IR/Treasury, management expects CY27/28 to be materially tighter than CY26 as bit demand runs well above supply, with SCA demand exceeding what MU is willing to allocate and contracts already extending through
- CY27 HBM pricing is set significantly above CY26, while Nov-Q should mark the FY27 GM floor before pricing/mix
drive expansion; management also expects to seek a materially larger buyback authorization near term. JPM stays OW/$1,540.
TSM / Samsung: Report points to another 8% 2nm price increase in Q1 – EBN
EBN reports, citing Taiwanese media, that TSMC plans an additional 8% increase in 2nm wafer prices for Q1 2027 after previously incorporating increases of roughly 20%. The report says TSMC’s five 2nm fabs are operating at full capacity and production targets have risen 15–20%, yet customers including Google, Amazon, Qualcomm and AMD still face shortages. EBN says Samsung is seeking alternative-foundry business with its second-generation 2nm process, targeting yields above 70%.
TSM: GS raises PT to $660/NT$3,300, sees strong 2027 growth + higher CapEx on broader AI demand
GS expects 2026/27 revenue growth of +42%/+36.9% y/y, with 3Q/4Q revenue +15.3%/+11.0% q/q as AI demand broadens across GPUs, ASICs, networking and increasingly server CPUs. GS raises 2027/28 CapEx to $85B/$98B from $78B/$82B, arguing supply remains insufficient despite expansion; near-term GM edges down to ~67.5%/67.3% on N2 ramp dilution. Reiterates Buy.
META / MSFT: Cut internal Claude use as in-house tools gain share – The Information (out yesterday)
The Information reports Microsoft cut its projected annual internal spending on Claude by more than a third from at least $1B, shifting staff toward GitHub Copilot and OpenAI models.
NOK: CEO says supply constraints hold back twice the buildout pace – CNBC
CNBC reports Nokia CEO Justin Hotard said customers could build data centers twice as quickly without supply constraints, identifying memory chips and energy as major bottlenecks. Hotard said demand remains strong and the industry is still early in the buildout. He argued that existing AI capabilities alone could support another three years of deployment progress even without new frontier models, as businesses continue implementing technology already available.
AI VALUE CHAIN: Bernstein sizes next-gen AI racks at ~$35–40B/GW
Bernstein estimates Vera Rubin at ~$7.5M/rack, AMD MI455X ~$7.3M, OpenAI Jalapeno ~$5.0M/pod and TPU v7 Ironwood ~$2.7M. Jalapeno has more scale-up networking/local HBM-DRAM and less scale-out/NAND than expected, implying higher supplier content. Bernstein also sees global GW deployments running above U.S. build estimates, suggesting international capacity is offsetting U.S. power/permitting delays.
ASML: BofA raises CY28 EPS 13% on higher ASPs/EUV units, PT to €2,557
BofA lifts CY28 revenue/EPS to €76.5B/€85.2 from €70.4B/€75.4B, driven by ~5% higher tool ASPs and EUV units rising to 120 from 110, partly offset by higher input costs. Every 5% ASP increase adds ~8% EPS with 2.5% cost pass-through, and BofA now sees ~50% EPS CAGR through 2028; reiterates Buy/Top Pick and raises PT to €2,557 from €2,452.
SOFTWARE
APP: Citi says eCommerce store growth accelerated through 3Q, with U.S. growth fastest in 3 months
Citi says AppLovin reached ~15.7K eCommerce customers as of Oct. 2, +7.4% w/w, with 3Q weekly growth averaging ~3.1% and implying ~11.9K average stores for the quarter. U.S. stores rose +3.2% w/w, the fastest pace in three months, while international grew +15.3% led by Hong Kong/China, partly tied to dropshipping and ShopX. Store quality also improved modestly, with average rank moving to 404 from 414; Citi stays Buy.
S: FBN downgrades to SP/$24 as valuation + scale gap vs. CRWD offset improving fundamentals
FBN says execution has improved, with FQ2 RPO +45% y/y, AI security ARR nearly tripling and NG operating margin reaching 10.5%, but shares now trade above its $24 PT after more than doubling from April lows. FBN sees valuation as full at ~5.7x FY28 revenue/50x NG EPS, while SBC remains high at ~28–32% of revenue and CRWD/PANW’s much larger scale supports better margins, reinvestment and incremental ARR capture.
NOW: UBS checks show stable demand + rising security opportunity, raises PT to $150
UBS says partner checks show healthy ServiceNow demand with some improvement, supporting modest +50bps increases to 3Q cRPO/subscription growth and a normal beat. AI adoption is progressing but spend remains early, while security/governance is emerging as a larger 2H26/2027 opportunity, particularly around AI Control Tower. UBS stays Neutral but raises PT to $150 from $110.
NOW: Stifel checks point to ~22% cRPO vs. ~20% guide, raises PT to $160
Stifel’s SI checks imply reported 3Q cRPO around 22% y/y cc, ~200bps above guide, though organic growth is closer to 19–19.5% after ~275bps of M&A contribution. Advanced-SKU upsell is gaining traction despite uneven Now Assist ROI, while a nine-figure UK public-sector win offsets some U.S. federal noise; Stifel keeps Buy and raises PT to $160 from $120.
WDAY: RBC sees Rising as AI proof-point catalyst, with Sana/Flex monetization the key debate
RBC says Workday Rising/10/13 analyst session could validate the AI story, with AI ARR ~$600M (+>200% y/y), >5,500 customers using organic agents and AI attach rates >50% in 2Q. Key watchpoints are Flex Credit consumption/per-agent economics and Sana, where 12K internal users built ~22K custom agents in three weeks; RBC sees early traction as encouraging but wants proof AI spend can drive top-line acceleration without pressuring margins. Reiterates OP/$240.
PANW: BTIG checks strongest across cyber, with FY27 confidence improving
BTIG says 7 partner checks representing ~$1.5B of PANW sales were uniformly positive, with improving Q3 trends and several seeing 15%+ growth. Upside case is FQ1’27 revenue of ~$3.37B (+17.1%) vs. Street ~$3.31B and NGS ARR ~$9.60B (+33.9%) vs. ~$9.54B. Buy/$425.
NET: BTIG checks show broad acceleration, raises PT to $413
BTIG says NET checks were consistently strong across app security, Workers AI, Magic WAN/SASE and bot management, with one large partner seeing meaningful September acceleration and another tracking mid-20s growth. Upside case is FQ3 revenue ~$760M (+35.2%) vs. Street ~$737M (+31.1%); BTIG now assumes 30%+ revenue CAGR through 2030. Buy, PT to $413 from $382.
FTNT: BTIG sees demand improving beyond pricing/pull-forward
BTIG says underlying demand is accelerating on AI infrastructure, firewall/SD-WAN refresh, OT and SSE, with one partner raising growth expectations to ~17% from 15% and another seeing ~30% growth. Upside case is product revenue ~$780M (+39.5%) vs. Street ~$728M and billings ~$2.40B (+32.5%) vs. ~$2.31B. Buy/$203.
Cyber / SNOW / ASOS: ASOS drops 12.5% after app alert claims Snowflake breach – The Standard
The Standard reports ASOS shares fell about 12.5% after customers received an app notification claiming attackers had compromised the retailer’s Snowflake instance and threatening to leak data. ASOS had not confirmed the breach when the report was published, and its website and app remained operational. Security experts cited by the paper say the notification suggests access to connected systems, but does not establish the extent of any data breach; the notification system is separate from Snowflake.
INTERNET/OTHER
META: Wells raises PT to $1,000 from $796 despite FY27 EPS cut on Muse OpEx
Wells cuts FY27 EPS 2.1% to $31.18 as Muse pushes OpEx toward $210–215B vs. Street $202B and removes ~$5B of high-margin capacity resale, but frames 2027 as a trough investment year analogous to 2022 Reels with AI monetization layering in from 2028. 3Q still looks clean at $64.1B revenue/$3.72 EPS, while FY27 CapEx rises to ~$249B vs. Street ~$194B; stays OW and raises PT to $1,000.
VRSN: Baird keeps Fresh Pick as Informed adds another growth vector
Baird highlights Verisign Informed, a real-time credential trust service entering beta now with GA targeted for 1H27, plus VRSN’s application for the .pki TLD and potential additional gTLD bids. Alongside domain growth, .com pricing and .web, Baird sees five distinct growth vectors and views ~23.5x NTM FCF as inexpensive; VRSN remains a best idea/Fresh Pick.
CABLE: MoffettNathanson sees early signs broadband pricing is stabilizing after a brutal year
MoffettNathanson says U.S. broadband pricing may be stepping back from the brink after worsening ARPU pressure, aggressive FWA discounting and rising fiber competition. AT&T recently raised its 1-Gig promotional price by ~$20/month in two steps, while Comcast and Optimum have pulled back promotions and T-Mobile ended a recent offer, suggesting industry pricing discipline may be returning. The key debate is whether this marks a sustainable recovery or just post-quarter promotional normalization.
AAPL: Bernstein tracker shows strong August iPhone growth, but early iPhone 18 demand mixed
Bernstein says August global iPhone revenue grew +13% y/y on +7% units and +6% ASP, with iPhone 17 cumulative sales ~18% above the 16 series. However, initial iPhone 18 Pro/Max demand is mixed, including low-single-digit y/y declines in the U.S., and July/August FQ4 units are tracking modestly below expectations, partly offset by stronger premium mix/ASP. Bernstein sees limited incremental TSMC impact, while Sony looks better and QCOM/Largan face more pressure.
AMZN: Susquehanna unBoxed checks positive on full-funnel ads, with agentic commerce more gradual than feared
Susquehanna says after 24 partner checks at unBoxed, advertisers are increasingly spending across sponsored search, AI shopping and DSP, with new Ads Agent/agentic products seen as incremental positives. Most checks expect humans to remain involved in higher-value purchases, making agentic commerce a gradual shift rather than near-term disruption; AMZN’s data, merchant relationships and fulfillment network remain key advantages. Positive/$325.
PINS: New CFO announced - PR
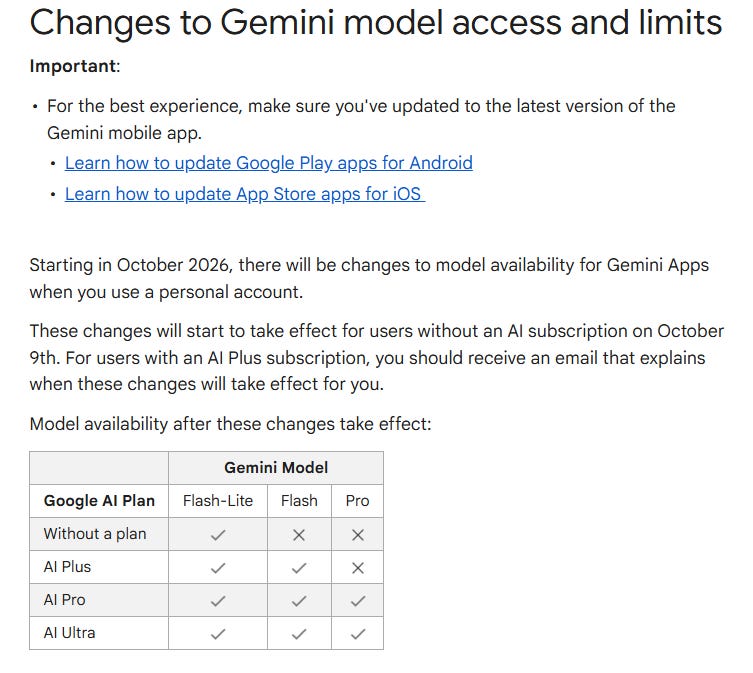
GOOGL: Makes changes to Gemini model access and limits (h/t Akh)
FRSH: Will join SP600 tomorrow night.
NEWS
TCEHY / DeepSeek: Funding expands to at least $12B ahead of 2027 IPO – Bloomberg
Bloomberg reports DeepSeek is close to raising at least RMB80B ($12B), exceeding its initial RMB50B target, with Tencent and CATL among the largest backers. Signed term sheets could take the final amount toward RMB100B as investor demand strengthened following its latest model release. The financing would precede restructuring for an IPO in early 2027. Bloomberg also reports DeepSeek plans to deploy at least 160,000 Huawei accelerators at its Inner Mongolia data center, potentially creating one of the largest known Huawei chip clusters.
Moonshot / BABA / TCEHY: Valuation reaches $50B ahead of Q1 IPO; ARR seen doubling – Bloomberg
Bloomberg reports Moonshot completed its final private funding round at roughly a $50B valuation, up from $31.5B this summer, and is targeting a Hong Kong IPO in Q1 2027 that could raise up to $5B. Early investor meetings may begin this month. Sources expect ARR to reach $2B by December from $1B currently and $300M in June. The Alibaba- and Tencent-backed company has filed confidentially; Bloomberg notes China’s data-security investigation into Moonshot and DeepSeek could affect the timetable or valuation.
Reflection / NVDA: Beam launches to compete with Chinese open models – Reuters
Reuters reports Nvidia-backed Reflection AI released Beam, its first open-weight model, targeting coding and agentic tasks served by Chinese competitors such as DeepSeek and Kimi. Reflection says Beam is competitive with Z.ai’s GLM-5.2 and approaching Qwen3.8-Max on those tasks. The model has 501B total parameters but activates 23B per task to reduce computing requirements. Reuters notes Reflection has secured additional compute from SpaceX’s Colossus 2 facility.
OpenAI: OpenAI launches visual ads that appear alongside image generation results - TechCrunch
OpenAI: UAE funds discuss up to $10B contribution to new round – Bloomberg
Bloomberg reports UAE investors including MGX are discussing a syndicate that could contribute as much as $10B to OpenAI’s planned funding round of at least $30B. BlackRock is also in talks, alongside existing investors including the University of California endowment, Thrive Capital and Andreessen Horowitz. OpenAI is presenting a $1.4T pre-money valuation as a fixed price despite not yet securing a lead investor. The financing follows its decision to defer an IPO until at least next year.
GOOGL / PCB / CCL: TPU upgrades drive higher board content and material prices – Commercial Times
Commercial Times reports high-end copper-clad laminate prices have risen 50–100% this year as TPU upgrades increase board complexity and materials remain scarce. It cites Aletheia forecasting Google TPU shipments of 3.6M in 2026, 8.5M in 2027 and 12M in 2028, with additional CCL price rounds of 10–15% through the first half of 2027. Aletheia estimates PCB content of $30,000–40,000 per TPU V8 rack and CCL content of $12,000–18,000, with the move to HDI in HumuFish potentially adding another 40–50% to those values.
Aspeed / AI Servers: Q3 beats guidance; analysts see roughly 40% Q4 growth – Commercial Times
Commercial Times reports Aspeed’s Q3 revenue reached NT$4.786B, up 23.6% sequentially and 105.4% YoY, above its NT$4.1–4.3B guidance as server-management chip demand stayed strong. Analysts cited by the paper forecast NT$6.6–6.8B in Q4 revenue, up 38–42% sequentially, and 67–68% gross margins. Chairman Chris Lin said supply bottlenecks began easing in Q3 and should improve more noticeably in Q1 2027; orders already on hand for next year exceed this year’s full-year revenue. The paper also reports expected Q4 price increases and further AST2700 volume growth.
Samsung Electro-Mechanics: Customers back $5B substrate expansion – DigiTimes / The Elec
DigiTimes reports customers are providing funding and long-term volume commitments for Samsung Electro-Mechanics’ KRW6.78T ($5B) FCBGA expansion in Korea and Vietnam. Its substrate utilization reached 89% in the first half, versus 70% last year; new Korean production is scheduled for September 2028 and Vietnam for June 2030. DigiTimes cites TrendForce putting September ABF-substrate lead times at 48–56 weeks, versus roughly 12 in a balanced market. Separately, The Elec reports a new KRW285.6B AI-server MLCC order for 2027, bringing Samsung Electro-Mechanics’ six disclosed component supply contracts this year to about KRW3.9T.
LG Electronics / Cooling: Signs 5GW North American data-center supply agreement – The Elec
The Elec reports LG Electronics signed a definitive long-term chiller supply agreement with Air Control Concepts covering a total 5GW of AI data-center cooling projects in the US and Canada. LG will supply chillers and related cooling systems progressively through the infrastructure platform, whose AMC subsidiary develops large data-center projects. The report says LG already began supplying cooling systems this year for a major North American AI data-center project won in 2025.
APP: San Diego alleges child tracking and explicit ad targeting – Bloomberg
Bloomberg reports San Diego County sued AppLovin, alleging it bypassed parental controls and tracking opt-outs to collect children’s sensitive data and serve ads for adult content, alcohol and vaping in games. The complaint alleges device fingerprinting circumvented Apple and Google protections without parental consent. Bloomberg notes the action follows the SEC’s closure of its separate advertising-practices investigation without recommending enforcement, according to AppLovin’s CFO in August.
TikTok / SHOP / CRM: Adds AI shopping assistant and one-click checkout – TechCrunch
TechCrunch reports TikTok launched a conversational shopping assistant and one-click checkout that lets users buy directly from brands within its For You feed. The assistant remembers preferences and provides product, sizing, availability and shipping information while helping complete purchases. Partners include Shopify, Salesforce, Shoplazza and Stripe. The rollout extends commerce beyond the TikTok Shop marketplace into the broader app, allowing users to research and purchase products without leaving the platform.
META: Ofcom opens first Online Safety Act probe – Reuters
Reuters reports Ofcom opened its first formal Online Safety Act investigation into Meta, examining whether it adequately assessed illegal-content and child-safety risks before launching Instagram Instants in May. The feature makes shared content disappear after viewing. Meta says it conducted a risk analysis, briefed Ofcom before launch and included automatic Teen Account protections.
UMC: September sales hit record as 22nm and 8-inch demand improve – Commercial Times
Commercial Times reports UMC’s September revenue reached a record NT$25.35B, up 27.2% YoY and 1.2% sequentially, supported by expanding 22nm business and recovering 8-inch wafer demand. Q3 revenue totaled NT$74.24B, rising roughly 8% sequentially and 25.6% YoY. The paper says monthly revenue has increased since March, with September exceeding the previous record set in August 2022. Revenue for the first nine months rose 16.1% to NT$204.01B.
###