2026.10.07 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
Good afternoon. QQQs -25bps, well off the -1% morning lows, but underneath was uglier than the index with a lot more red than green on my screen. Semis -1.1% and software -1.2% underperformed while internet +70bps was green. Overall didn’t hear any panic or shifting narratives from investors today — seemed more like a digestion/rotation day.
In semis, analog/auto was the worst of it on no news (MCHP -4%; STM -4.3%; ON -4.4%; NXPI -4%), semicap stayed soft (TER -4.3%; LRCX -1.3%; AMAT -1.8%) and neoclouds fell, led by IREN after SemiAnalysis aired customer complaints about its BC sites (IREN -6%; NBIS -5%; CRWV -3.6%); in software, cyber gave back some of its run (CRWD -4.8%; PANW -3.4%; NET -3.5%).
The green was in memory as rotation with AI semis continues, which ripped off the strike-headline lows (MU +4%; SNDK +2%), AI hardware/storage catching another bid on Evercore’s NTAP upgrade (DELL +1%; NTAP +3%; P +5%; HPE +2%) as on-prem remains one of the strongest sectors with AI, and beaten-up internet (SPOT +5.1%; CPNG +2.7%; RDDT +2.5%; DUOL +2.4%) got a bid. Among megacaps, META -2.4% lagged while AMZN +1.4% was green for a second straight day, which these days counts as news.
In macro land, investors continue to focus on the long-end. The 10Y pushed to ~5.35% this morning, a 24-year high, before a strong 10Y reopening at 1pm pulled it back to finish +1bp to 5.28%. The September FOMC minutes at 2pm had “most participants” seeing another hike as likely appropriate by year-end, also saying “some” worried the “AI buildout could cause aggregate demand to outpace aggregate supply.” Futures still put ~20% odds on a 10/28 hike, in line with Tuesday and down from 70%+ early last week. WTI traded around $90, up ~1% early as tanker attacks in Hormuz hit their highest weekly count of the war, and BTC -3% to ~$83K after a late-night flash selloff. HYG flat put in a nice green candle off the lows.
Let’s get to the good stuff…

AI/SEMIS
- MU +4.1%; SNDK +1.9% reversed hard from the opening lows (MU was -3.3%) as Reuters reported MU’s Taoyuan union won strike authorization with 99% of ballots, and Korean media reported Samsung’s 12-high HBM4E passed qualification at NVDA and other customers
Jukan ✈️OCP 2026
@jukan05
SOUTH KOREAN MEDIA: SAMSUNG’S 12-HIGH HBM4E PASSES QUALIFICATION TESTS AT NVIDIA AND OTHER CUSTOMERS
hankyung.com
단독] 삼성 'HBM4E', 엔비디아 문턱 넘었다…주요 고객사 품질테스트 통과
TMTB Slack
- IREN -6.3% after SemiAnalysis on X said IREN keeps coming up in its conversations with neocloud customers “usually for the wrong reasons,” citing multi-day power outages, storage failures and network problems at its Prince George and Mackenzie sites in BC (Childress and Sweetwater look much better), and recommended IREN “stop falsely claiming to offer managed clusters” in investment materials like its 10-K:

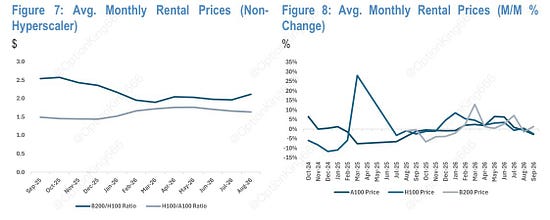
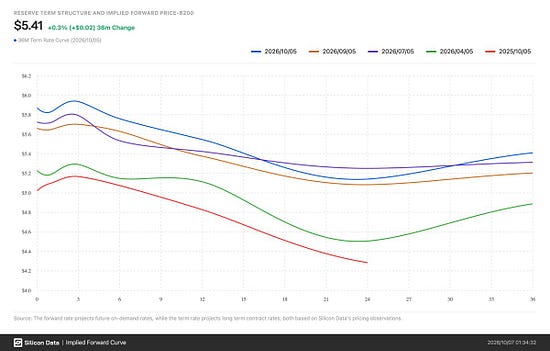
- NBIS -5.1%; CRWV -3.6%; WULF -3.8%; HUT -3.2% handed back part of Tuesday’s GPU-pricing pop with the long end near 24-year highs. NBIS initiated Buy after hours at Rosenblatt. Bulls love the GPU pricing data while bears point to the credit side: CRWV’s parent bonds are trading near 13% vs. ~9% for the HPC index. The new GPU pricing data continues to behave well: JPM’s September tracker had non-hyperscale B200 rents +1.3% m/m to $5.70/GPU-hour, widening their premium to H100s (-2.6% to $2.64) to 2.16x:
456X
@OptionKing666
Nvidia GPU rental prices diverged across hardware tiers in September 2026 as non-hyperscaler B200 rates rebounded 1.3% MoM to $5.70 per GPU-hour, according to J.P. Morgan. The recovery widened the B200-to-H100 pricing multiple to 2.16x from 2.08x in August, reflecting resilient …
2:10 PM · Oct 7, 2026 · 875 Views
1 Repost · 4 Likes
Carmen Li
@carmenli
Something interesting is happening in the B200 forward market 👀 B200 term rate curves have shifted meaningfully higher over the past several months — and it’s not just the front end. The latest @Silicon\_Data curve bottoms around 24 months and then turns higher, with the 36-month …
8:51 AM · Oct 7, 2026 · 7.43K Views
1 Reply · 9 Reposts · 56 Likes
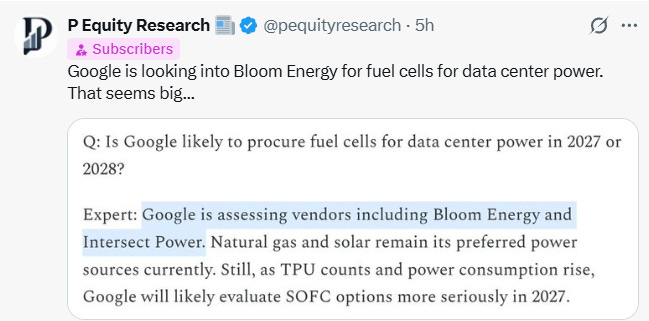
- VST +3.9% V’d off its -4% early low with no fresh news, holding most of Tuesday’s +11.2% on GOOGL’s CEG deal read-through, while GEV -3.1%; VRT -2.6%; BE -1.5% sold off with the rest of AI-infra. BE slipped despite UBS estimating ~900MW of GOOGL’s 2.7GW Cheyenne power stack could come from BE fuel cells. Another check from Wukong re: BE
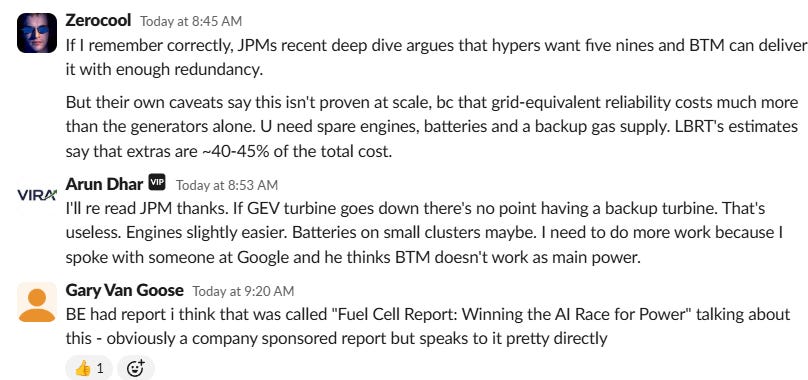
Some good discussion in TMTB Slack here around whether behind-the-meter power can ever be main power rather than bridge power, the question underneath the BE/GEV bull case:
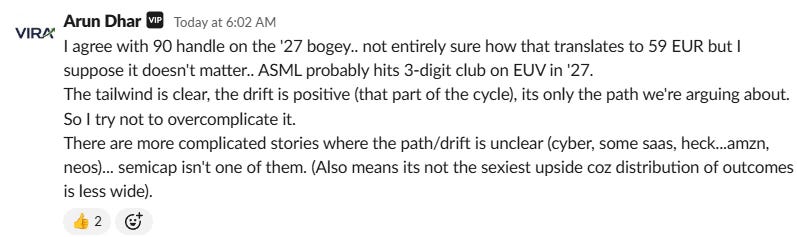
Arun Dhar framed it contractually: turbines, engines and fuel cells all count as back-up power, and he senses “reluctance across all the hypers” to go from bridge to main power because GCP needs four nines, heading to five, which off-grid doesn’t allow. More from the group:
TMTB Slack
- SPCX -2.5%

Elon Musk
@elonmusk
Important note regarding Grok @bot : Going forward, @SpaceX will use the best back end model for any given task, including Claude Opus 5.5, MidJourney, Suno and other leading APIs. Whatever is most likely to give you the best outcome.
6:46 AM · Oct 7, 2026 · 58.7M Views
5.97K Replies · 6.53K Reposts · 89.3K Likes
- AMD -55bps: CEO Su is in Taiwan this week, meeting Samsung’s chip head. A supply-chain check we heard today: ASE’s CoWoS capacity goes from 15-20k wafers/month at end-2026 to ~70k at end-2027, enough to underwrite ~5M Venice units, and Helios shows no thermal issue.
- Optical weaker giving back MRVL’s -81bps investor day pop from yesterday: TSEM -3.9%; GLW -3.4%; NOK -3.2%; CLS -4.3%. Some rotation likely at play here given memory strength, which had been a laggard vs optical’s strength.
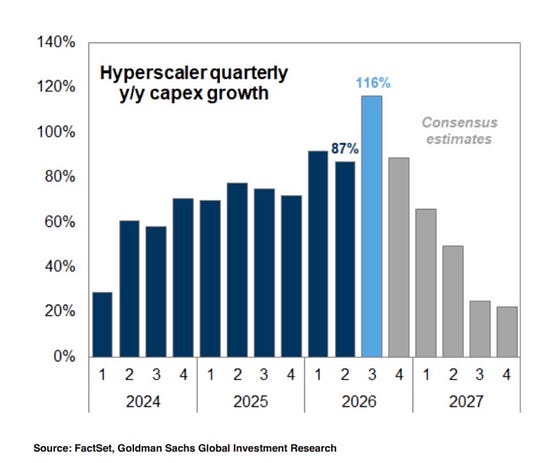
Carl Quintanilla
@carlquintanilla
You are here. ⬇️ (via GS)
2:31 PM · Oct 6, 2026 · 96.4K Views
27 Replies · 92 Reposts · 527 Likes
INTERNET
- META -2.4% lagged the other megacaps with no clear catalyst beyond Florida asking a court to force changes to FB/IG for teens as stock continues to digest recent strength after knocking up against $750 (<15% to 25x as we called out last week). Ad checks continue to sound good. Overall hearing MUSE downloads still strong (still #1 on app store charts), but have started to slow a bit given still not released internationally. Also hearing some more of the below. Still early.

Jessica Lessin
@Jessicalessin
So in the last two days about half of my Muse use cases have vanished because the browser won’t do it any more. Are websites changing their policies? Bot detection???
8:29 PM · Oct 4, 2026 · 584K Views
180 Replies · 20 Reposts · 1.22K Likes
I think the holiday shopping season will be a big test for usage and sustainability of these agents so far.
- Beaten-up internet bounced with little news (SPOT +5.1%; DUOL +2.4%; RDDT +2.5%; CPNG +2.7%; PINS +1.4%)
- SHOP +1% acted resilient despite the recent strength this past week
- RBLX +1.9% reversed from -3.4% at the open, shrugging off GOOGL’s new text-to-game creation platform (Playground), built with Unity.
- UBER -91bps agreed to buy ezCater for $2.3B in cash ($2.5B+ of TTM gross bookings growing high-teens, $400+ AOVs), its third delivery deal of the year after Getir and Delivery Hero. DASH -1.2% had a major US app outage on top of it (2,100+ Downdetector reports by ~2pm).
SOFTWARE
- MSFT +9bps raised Azure VM + Storage prices by ~17% starting Feb 1 in European regions, along with a ~25% hike on worldwide legacy v1/v2 VMs. · At its SF event with NVDA, MSFT launched Windows agents, the Surface Laptop Ultra on NVDA’s RTX Spark and MAI-Code-1.1 Flash, a 137B-parameter coding model that runs locally, and said META’s Muse app is coming to Windows….Also a couple positive sell side notes this morning as Evercore raised its PT to $635 from $528, modeling ~30.5GW of FY30 capacity and ~$389B Azure revenue (~40% CAGR), with an $880 bull case. JPM’s CSP checks pointed to ~7x Copilot penetration by FY-end, Fabric growing >200% y/y with 5x spending pull-through. We continue to think MSFT probably the cleanest hyper right now in terms of near-term narrative/upside.
- CRWD -4.8%; PANW -3.4%; NET -3.5%; S -1.9% gave back some of Tuesday’s run while ZS +61bps held up after its investor day. No catalyst I saw; the closest thing to group news was Bloomberg’s report that Anthropic is widening Mythos 5.1/Opus 5.5 access for organizations doing offensive security testing. H-Cap in TMTB Slack here flagged CRWD at ~40x forward EV/Sales, approaching its ‘20/’21 peak (”admittedly when 10yr Yields were ~1%, not approaching 5.5%”). If a lab ships a security product, the bulls we hear from see prevention beating detection, making PANW (~70% network security) “way more durable than CRWD.”
- TTAN +4.5% after its Pantheon customer event: Max is now GA for all residential in-home contractors, with Demand AI and Field AI as on-ramps at 20% and 40% discounts to full Max, plus Homh, a consumer demand-gen platform with a personal agent. The stock was -35% YTD into it (Truist); the nit from Needham is longer implementations and more back-end-weighted revenue recognition.
- ACN +1.7% after Truist hosted IR: the Anthropic engagement is revenue-generating paid work, the bigger long-term prize is enterprise AI safety/governance (management sees parallels to the cyber opportunity), and federal should be the main 4Q upside driver carrying into FY27.
- U +1% fading the initial 7% pop on the Google partnership to launching an integrated gaming platform
- GTLB +70bps after its Transcend conference: Ummera in TMTB Slack here noted new customers accelerated to >100% y/y last quarter with the current quarter “going even faster”; RBC counted agentic active users +200% y/y. S-Curve‘s pushback: “Hard to gain comfort in this space when you know this on all the AI natives roadmaps.” Surprised when I pulled this chart up today — has held up a lot better than the rest of the app sw space:

ELSEWHERE
- NTAP +3.2% after Evercore upgraded, arguing the ~17% FY27 growth guide bakes in an overly sharp 2H slowdown; normal seasonality gets you low-20s growth and ~$11 of EPS vs. the Street’s ~$10, which is the near-term bull case (the raised guide implies only ~9% 2H growth against 36% billings growth).
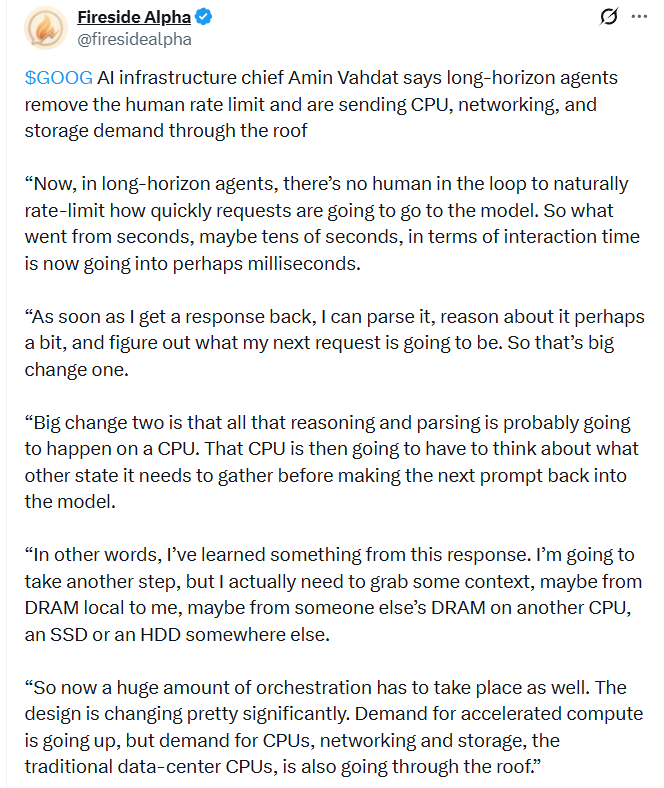
- AI hardware continues to act strong on up and down days: SMCI +3.4%; P +3.9%; HPE +2.3%; HPQ +1.6%. P traded with NTAP after JPM’s CFO meeting had storage TAM growth accelerating to ~12% CAGR from 8-9%, with a second hyperscaler deal confirmed. SMCI reversed from -2% at the open as GIGABYTE printed record September revenue (+125% y/y) on GB300 racks (Commercial Times). And GOOGL’s AI infra chief Amin Vahdat was on a pod saying long-horizon agents remove the human rate limit, sending CPU, networking and storage demand “through the roof.” Good quote below (h/t MyNameisJeff in Slack):
- CSCO -47bps; ANET +22bps: BofA’s 2Q channel survey had Ethernet switching +40% y/y (fastest since 2010) with AI back-end traffic +110%; CSCO’s DC revenue +78% y/y took ~530bps of cloud DC share from ANET, and Silicon One’s back-end share tripled to 9%.
- COIN -3.9%; CRCL -3.9%; HOOD -2.2% with BTC, which fell to ~$83K after a late-night flash selloff.
- DKNG -3% as Guggenheim now models ~$400M of prediction-market investment (vs. prior guidance of $200-300M), taking its FY EBITDA to $622M, below management’s $700-900M range.
- MBLY -4.3% as Der Spiegel’s Tuesday report that VW plans to drop it for Wayve kept making the rounds (all parties declined to comment).
- LCID -6.5%: still digesting Tuesday’s Q3 production of 2,954 and deliveries of 3,806, with production down after a shift cut.
- ENPH -1.2% after DB’s Sell catalyst call: if you strip out ~$255M of 2026 safe-harbor revenue and the Street’s ~$1.2B 2027 forecast implies an unrealistic ~33% core ramp; DB is 7%/21% below consensus on 2027 revenue/EPS.
- TTWO +73bps: green day. Mark the calendar.
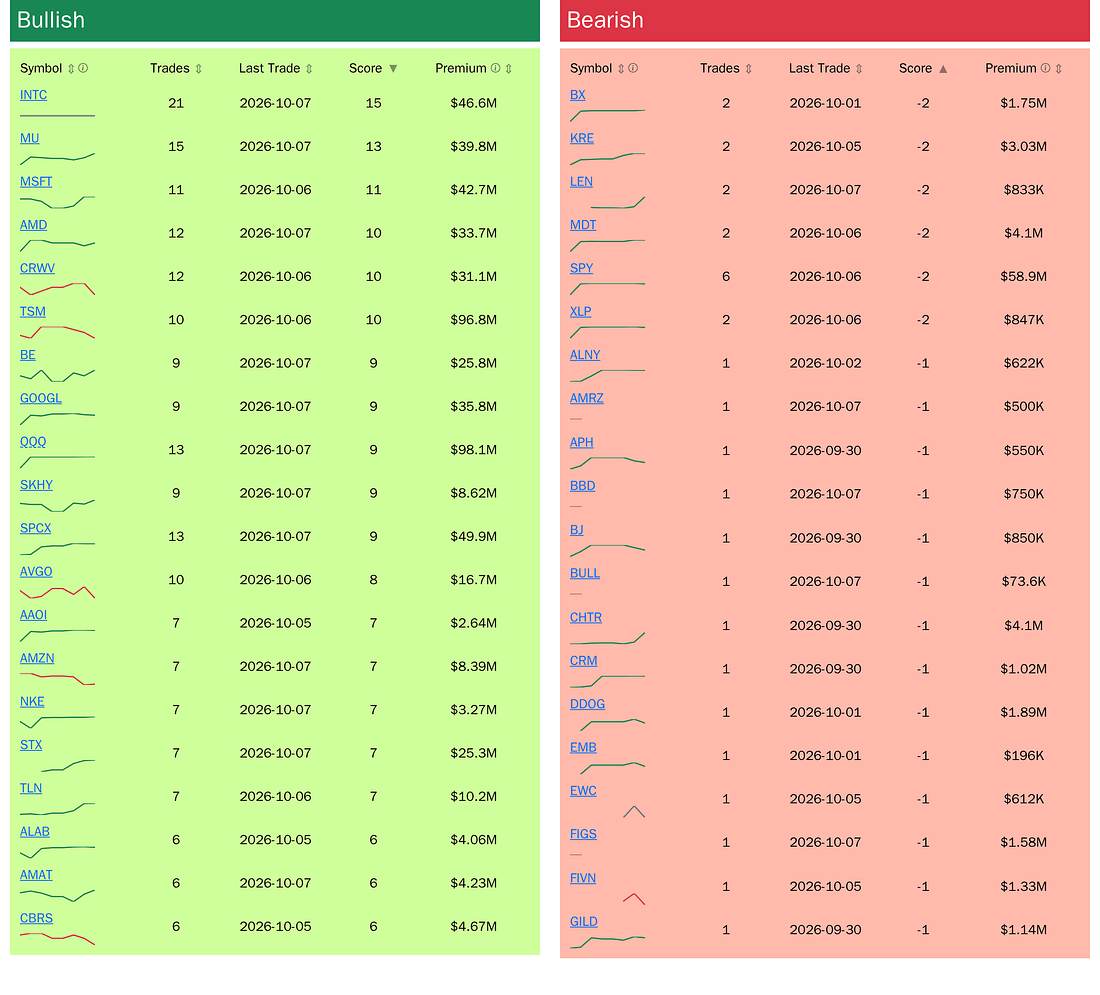
BULLISH AND BEARISH WEEKLY OPTION FLOW
Source: RunningoftheBulltards