2026.10.08 | Substack | Markets | TMTB EOD Wrap: Gross-to-Net Panic
原标题:TMTB EOD Wrap: The Great Gross-to-Net Panic of 2026
Good afternoon. QQQs -1.3% and Semis -3.4% were already soft on oil and yields when the FT’s 12:45pm headline that OpenAI’s annualized revenue is ~$20B below what had been signaled took SOX from about -1.7% to -3.4% in fifteen minutes; and it never really recovered (-4.6% at the lows). Turns out the biggest risk to the AI trade isn’t power, open source, financing or the Dems winning in November. It’s actually GAAP.
OpenAI’s ~$50B September ARR vs the previously reported ~$70B is the difference between gross and net so the headline was misleading (recall: OAI has to share 20% with MSFT and has the Bedrock deal as well).
Key quote from FT article: "According to a person with knowledge of the matter, the discrepancy arose from attempts by OpenAI’s own investors to produce a direct comparison with Anthropic’s annualised revenues. The pair calculate the figure in different ways, with Anthropic including the revenue from sales via cloud partners such as AWS and Google Cloud, while OpenAI does not.”
Last week we got a $70B figure from Axios which catalyzed enthusiasm among the AI bulls. But the actual progression from Q2 to Q3 seems to be ~$30B → ~$50B, not ~$40B → ~$70B, roughly the same 70% growth rate but off of different numbers.
Here’s my best attempt at how things look and what the numbers we have heard imply:
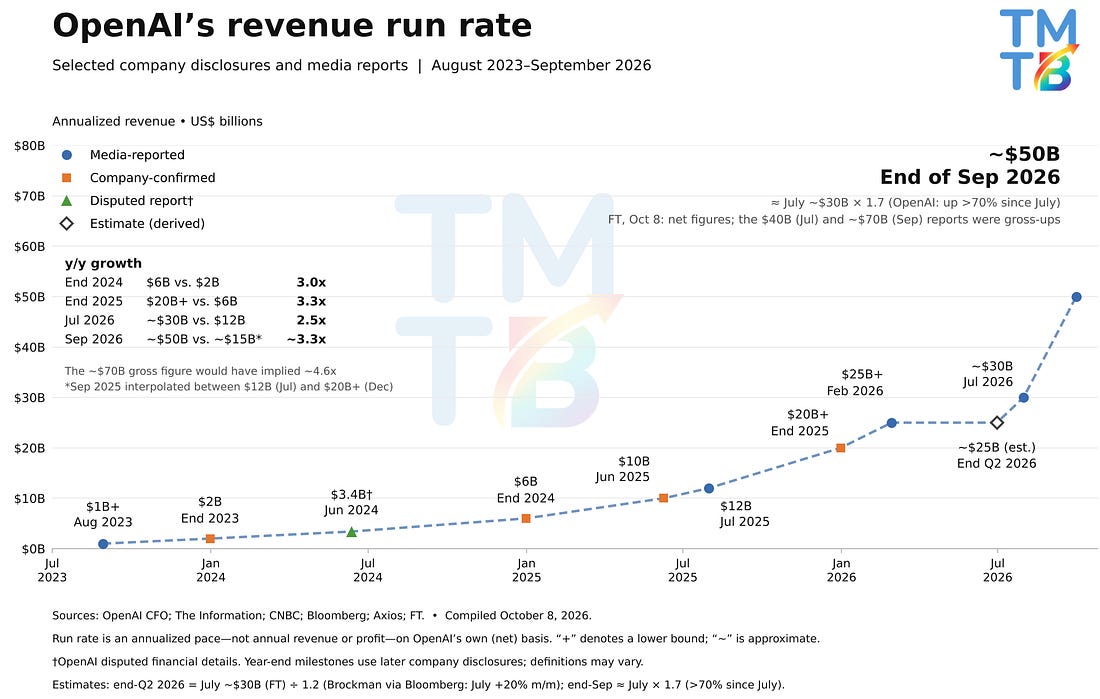

Glass half empty: People had thought $70B was net and the perceived dollar base just reset ~25–30% lower. OpenAI added ~$20B of ARR over August and September, not ~$30B. The first half was also weaker than people thought. The net run rate sat at ~$24–25B from February through June, and y/y growth slid to ~130% y/y by June, a bit decel from Dec 2025. That’s a lower starting point for YE26/YE27 net ARR targets & for valuation, and for the math on funding OAI’s compute commitments.
Glass half full: The growth rate hasn’t changed. $30B → $50B net is the same ~70% in two months as $40B → $70B gross, and the monthly additions picked up into September. The y/y line bottoms at +131% in June, then climbs to +150% in July, +182% in August and +229% (~3.3x) in September. Had July really been $40B, September’s $50B would have meant y/y growth flat at ~230%. On the net base, it’s actually sharp re-acceleration of ~100% y/y in 4 months. Against Anthropic nothing changes, because the ~$70B gross figure is still the like-for-like comparison.
We had a fun day in TMTB Slack and set a record for most comments in a thread here
Favorite comment in the thread:
Moving on…
Software -23bps held in and IWM flat finished well off its -1% morning lows as the long end rallied. Chart here looks interesting with IWM breaking its low but finishing above it, a false breakdown that can typically presage further strength

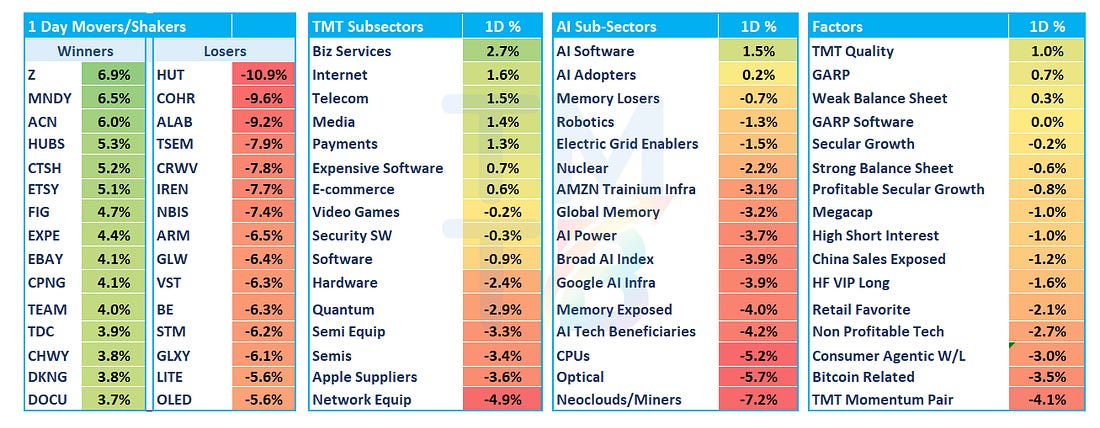
It was a rotation out of anything with AI-capex or AI-financing beta: neoclouds and miners, already sliding on Firmus’ IPO stumble (HUT -11%; CRWV -8%; NBIS -7.4%; IREN -7.7%), optics and AI networking (COHR -9.6%; ALAB -9%; GLW -6.4%; LITE -5.6%), AI power (BE -6.3%; VST -6.3%) and the OpenAI counterparties (ORCL -5.6%; AVGO -4.3%; NVDA -3%) led the way lower. The other side of the trade was another squeeze in the AI-loser baskets: IT services (ACN +6%; CTSH +5%), the Muse-disintermediation names (Z +7%; EXPE +4.4%; ETSY +5%; EBAY +4%) and seat-based software (HUBS +5.3%; MNDY +6.5%; FIG +4.7%). AAPL +1% was the only green megacap ahead of Tuesday’s smart-home event.
Couple charts worth flagging in semis…
NVDA with what could be a false breakout. Has typically led to some further weakness (see the red arrows)

The other semis that were hitting 52wk highs this week: LITE and TSM charts also look similar dipping below previous resistance after ATHs, but AMD still holding its breakout.
WDC breaking one of few stocks actually breaking below Leopold lows:
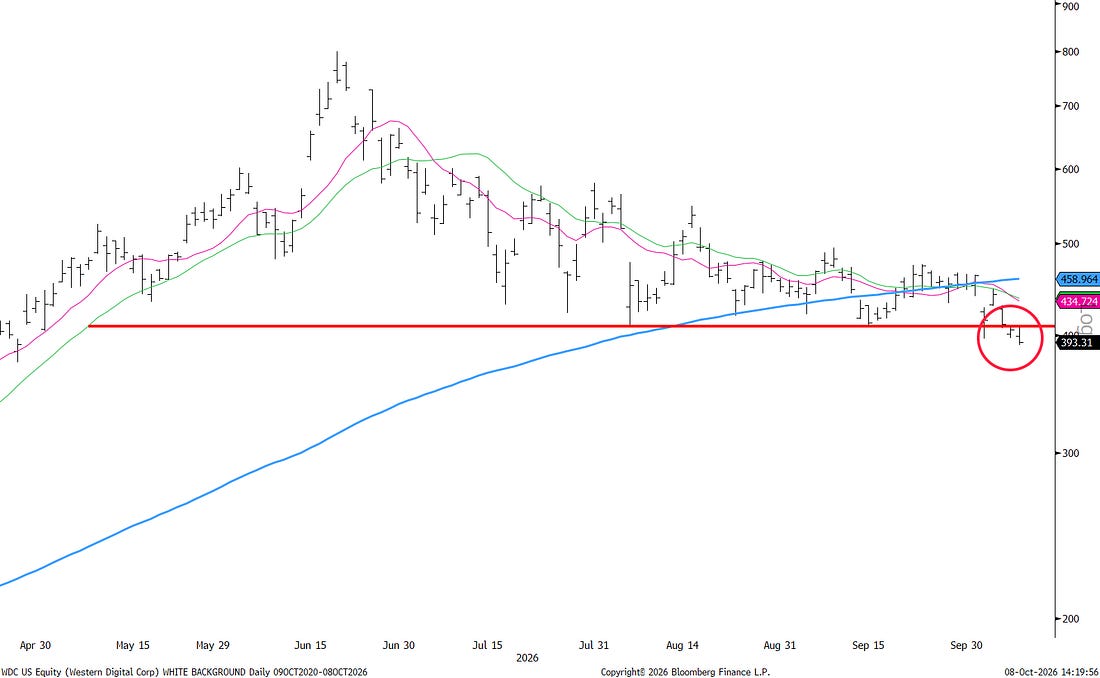
Overall, wouldn’t surprise us if a bit more digestion could be in the cards and we managed some semi risk today, but we’re not overreacting to what Arun in Slackaptly called a “storm in a teacup.”
In macro land, oil and Iran set the tone early before the long end turned. WTI +3.4% to ~$91 (it was +5% pre-market) on reports the military is readying Iran strike options, and only partly gave it back after Trump posted around 12:20pm that the US won’t attack Iran before the midterms. The 10Y -6bps to 5.22% (TLT +94bps) after touching ~5.35% this morning, with the long end leading (30Y -7bps to 5.60%; 2Y -2bps to 4.75%) after a decent 1pm 30Y auction (2.54x bid-to-cover vs. a 2.41x average). ~18% odds of a 10/28 hike, about where it was yesterday, and ~69% by December. BTC -2% to ~$81.7K, a three-week low.
Does anything else matter today? Who knows, but let’s get to it…
AI/SEMIS
- Neoclouds & Miners underperformers: HUT -10.9%; CRWV -7.8%; NBIS -7.4%; IREN -7.7%; WULF -5.2%; GLXY -6.1% were weak from the open, before the OpenAI headline, after Bloomberg reported NVDA-backed Firmus’ $5.5B Australian IPO is in doubt at the A$11 marketed price (a ~$30B valuation on $51M of FY26 revenue), “fresh cracks in the AI funding boom” said Bloomberg although MyNameisJeff gave us a reality check on Firmus:
JP in TMTB Slack here: “Powered shells are rates beta + mtum.” Pricing checks still sound strong - one check we heard this week called out 6-9 monthVera Rubin contracts clearing at ~$40B/GW annualized vs. $10-15B for long-term deals.
- AVGO -4.3% underperforming as an OpenAI chip supplier: WSJ had it discussing $50B+ of financing for OpenAI’s custom-chip program (starting with Jalapeño) with Apollo, Blackstone and others last night. That’s the medium-term bear case/overhang: ~15GW of the ~20GW behind AVGO’s $230B FY28 AI outlook is Anthropic/OpenAI, which isn’t self-funding, hence the residual-value guarantees and financing talks; bears will say bulls need the first OpenAI/Anthropic GWs to convert on time despite stock already trading at low-teens multiple of >$30 of FY28 EPS.
- Lots of questions on optical weakness: COHR -9.6%; LITE -5.6%; GLW -6.4%; TSEM -7.9%; CIEN -4.6%; NOK -4.5%. Mei in TMTB Slack here flagged that optical transceivers aren’t on the agenda the FCC released for its October meeting, the rule to keep new Chinese transceivers out of the US that Reuters first reported in August.
- Memory bulls enjoyed their day in the sun, but came back to earth today: MU -4.8%; SNDK -4.9%; SKHY -4.3% fell even though Samsung’s prelim beat the bogey: KRW107.4T of Q3 OP (a ~55% margin) vs. LSEG’s KRW106.1T and bogeys that had drifted down to KRW105-106T.
- ALAB -9.2%; CRDO -3.7%; MRVL -3.5%: AI networking weaker. ALAB was green for a little early after launching its PCIe 7 retimer this morning.
- ARM -6.5% traded as an OpenAI proxy through SoftBank and it’s in week one of its Delaware jury trial with QCOM -63bps, which wants to halt royalty payments for up to five years. JDorbal1989 on X has had great coverage of the trial. Based on his coverage, QCOM seems to be ahead on the testimony so far. He describes Day 2 as brutal for Arm after its chief architect admitted ACK verification tools are core to an architecture license, engineers detailed workarounds for roughly 29 withheld patches, and video depositions showed Arm’s leadership authorized leaking the October 2024 cancellation notice to Bloomberg during Snapdragon Summit. On Day 3 he writes that QCOM dismantled Arm’s most-favored-nation pricing story (Samsung rate quietly swapped for MediaTek, support stripped from the offer) and got Chief Legal Officer Spencer Collins to admit Arm fed the notice to Bloomberg because it expected Qualcomm to leak first, while then barring Qualcomm from reassuring customers. In the bench portion he highlights Judge Noreika pressing CEO Rene Haas on internal “enemy” emails versus public claims that Arm wants Qualcomm to succeed, Haas conceding lingering anger over Nuvia, and Haas stating that Arm alone should set the rates its competitors pay.
- INTC -5.3% reports that global sales head Greg Ernst is out a little more than a year after Lip-Bu Tan tapped him.

Semiconductor News by Dylan Martin
@DylanOnChips
COVER STORY: Intel's sales leadership shake-up Intel CEO Lip-Bu Tan last year tapped Greg Ernst, a 27-year veteran, to lead global sales. A little more than year later, he was out. Just a week earlier, he posted about feeling "energized" about the "opportunities ahead."

2:31 PM · Oct 8, 2026 · 2.51K Views
2 Replies · 1 Repost · 13 Likes
- TSM -3% couldn't hold a record quarter: Q3 revenue of NT$1.49T beat the top of its NT$1.43-1.47T guide
- GFS +2.7% was up as much as 7% after Reuters reported it will make a key AI chip component for TSM (silicon interposers, per the squawk), before giving back more than half with the rest of late afternoon semis drawdown.
- STM -6.2%; ON -3.8%; MCHP -3.2%; NXPI -1.8%: analog extended yesterday’s slide as Citi downgraded NXPI, arguing positive semi estimate revisions slowed in 2Q and should moderate further in 3Q, with NXPI lagging given limited data-center exposure.
- WOLF -1.1% round-tripped a gap up of as much as +15% (and +20% yesterday after horus) on the $1.5B DoW loan as investors looked at the fine print: the commitment is conditioned on raising at least $750M of equity and converting a large part of the converts, plus warrants for up to 7.5% of the company.
- OLED -5.6% as Citi downgraded it to Sell, citing valuation.
INTERNET
- The Muse-disintermediation shorts got squeezed: Z +6.9%; EXPE +4.4%; ETSY +5.1%; EBAY +4.1%; LYFT +3.4%; BKNG +2.6%; UBER +2.6%; ABNB +1.6% Jefferies was out this morning saying only ~1/3 of sites work seamlessly with Muse (~1/3 block it, ~1/3 restrict it), pushing out META’s agentic-commerce take-rate math. BKNG rallied even with Evercore’s tactical Underperform (weak long-haul, ~7% Middle East bookings). Some stats from Similar web also showed Muse DAUs slightly slowing in October:
Similarweb
@Similarweb
DAUs on @Muse keep climbing, peaking at 2.182 million on October 5th.

7:55 AM · Oct 8, 2026 · 27.1K Views
2 Replies · 19 Reposts · 81 Likes
The chart has four distinct phases of DAU growth (reminder no international launch yet):
- Launch week: Slow, averaging about +28K a day, and stalled around 220–240K from 9/12 to 9/15.
- Inflection (9/17–9/24): Adds jumped to about +145K a day, roughly 1.2M new DAUs in eight days.
- Dip and rebound: After one down day on 9/25, growth returned to about +145K a day from 9/27 to 9/30.
- Since 10/1: Growth has slowed to about +45K a day, or 0–4% daily, though 10/4–10/5 picked back up to +80–90K.
- META -6bps held in better than the megacaps, catching a bid once Gemini Agent turned out to be enterprise, not consumer. I guess some people were shorting yesterday into this into the Google event given stock was down 2% yesterday. 40% of advertisers in Jefferies’ survey expect Muse to increase their META spend over the next 12 months.
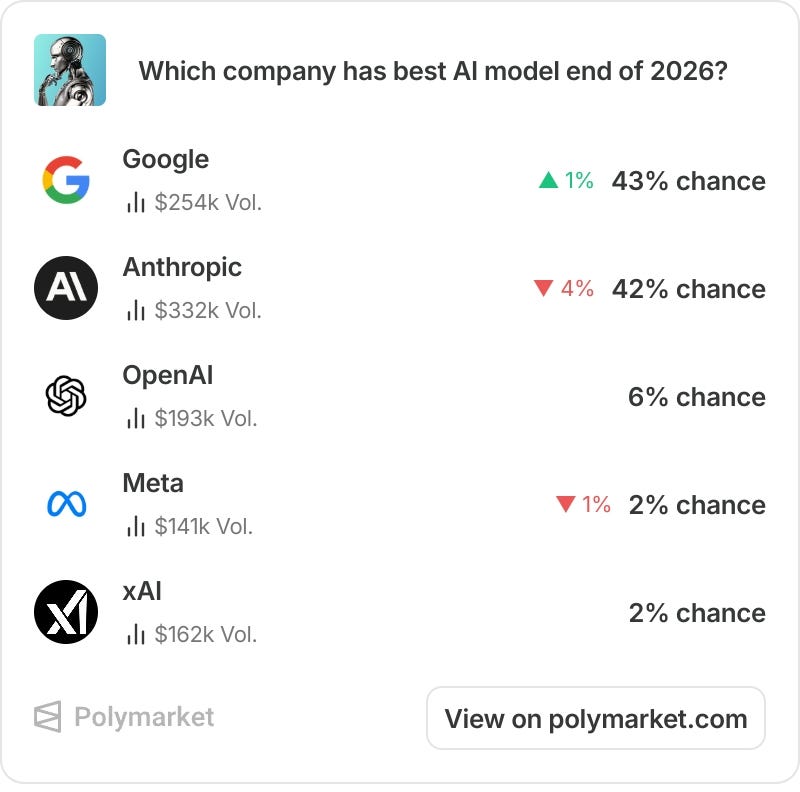
- GOOGL -63bps gave back a +1.8% morning high after launching Gemini Agent, its universal enterprise agent. Good discussion in TMTB Slack here on the detail that it can run on Gemini or Claude models: davy asked whether that’s GOOGL conceding it isn’t at the frontier, and if so whether capex reads lower (”quite positive for the name”); Anoncapital countered that Anthropic is GOOGL’s biggest TPU customer, so “GOOG needs Anth to continue crushing it.” Some flagging GOOGL now favorite to have best model end of the year although calvin on Slack caveated: think it’s more of a bet that GOOGL benchmark maxxes than a bet on GOOGL having best model
- AMZN -2.3% lagged despite MS sizing Bedrock at a ~$10B run-rate growing ~100% sequentially. AWS CEO Garman on a podcast: "We don't anticipate slowing (capex) anytime soon because the demand is just massive". Full podcast recap in our TMTB Podcast Intel this afternoon here.
SOFTWARE
- Big rally in “AI loser” related names with a lot more green on my screen than not
- ACN +6%; CTSH +5.2%; IBM +2.8% led the AI-loser squeeze, CTSH from -4% at the morning lows after Vance said the
US is suspending MSFT and other firms from the PERM green-card program. Rotation took over from there, extending ACN’s run since its 10/1 print when it was up mid teens.
- HUBS +5.3%; MNDY +6.5%; FIG +4.7%; TEAM +4%; ADBE +3.6%: seat-based software also squeezed higher helped by the
semis drawdown and short-covering, HUBS even after JPM downgraded it this morning (AI monetization taking longer, a medium-term growth headwind rather than a temporary one).
- ORCL -5.6% on OpenAI related weakness. The WSJ story last night had ORCL talking to Apollo and GS about a vehicle that would own chips and lease them back. That supports medium-term bear case that FY27 funding leans on others with correlated exposure to the biggest AI counterparties; bulls will say customer-owned hardware and supplier financing are exactly how capacity outgrows ORCL-funded capex.
- MSFT -1.3% with the OpenAI read-through on top of Vance’s green-card headline.
- PLTR +2.4% was up as much as 5% after GS upgraded to Buy, arguing sovereign AI, bespoke apps and verticalization drive another step-up in TAM and another estimate-revision cycle into 2027. Getting close to ATHs again.
- U +1% faded for a second day from +4% on RJ’s upgrade; several sell-side notes out saying how GOOGL’s AI and distribution close the non-coder gap in the creator funnel and Jefferies’ buyer survey saying U the biggest expected ‘27 share gainer.
- APP -42bps: Jefferies cut ‘27 EBITDA 7% as its survey has APP’s gaming share flattening at ~30% after years of gains, putting the burden on take rate.
- Cyber weaker: PANW -2%; CRWD -1% although OKTA +1% continues to act well
- TEAM +4%
In Practise
@\_inpractise
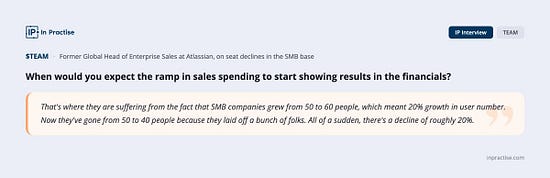
Former Global Head of Enterprise Sales at Atlassian on SMB seat declines at $TEAM
2:30 PM · Oct 8, 2026 · 1.11K Views
1 Reply · 1 Like
"That's where they are suffering from the fact that SMB companies grew from 50 to 60 people, which meant 20% growth in user number. Now they've gone from 50 to 40 people because they laid off a bunch of folks. All of a sudden, there's a decline of roughly 20%."
ELSEWHERE
- TTWO +2.6%: a second straight green day. M-sci says pre-orders are strong and still point to ~50M units of sell-through through December. Benefitted from the rotation into sw today. The Verge corrected its report that MSFT secured exclusive GTA VI cloud streaming rights after Xbox CSO Matthew Ball clarified the deal is not exclusive and will not enable PC streaming. The Verge still reports Xbox Cloud Gaming will carry GTA VI at its Nov. 19 launch, potentially limited to Xbox consoles, eliminating the previously implied PC distribution opportunity.
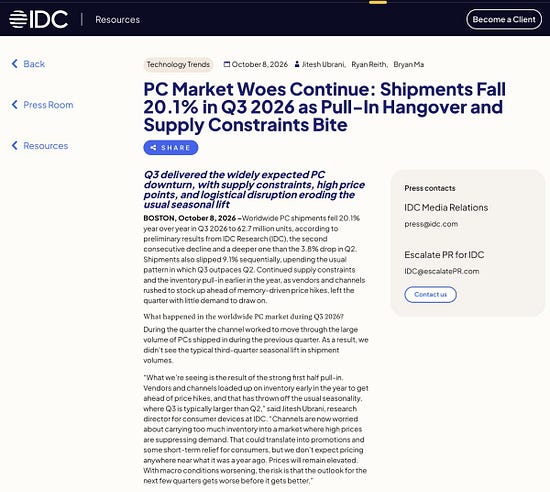
- HPQ +62bps; DELL -73bps; LOGI -67bps shrugged off IDC’s prelim Q3: PC shipments -20.1% y/y to 62.7M units, a second straight decline and much deeper than Q2’s -3.8% as the 1H pull-in ahead of memory-driven price hikes left little demand to draw on. IDC: “the risk is that the outlook for the next few quarters gets worse before it gets better”

tae kim
@firstadopter
IDC: "Worldwide PC shipments fell 20.1% year over year in Q3 2026 to 62.7 million units, according to preliminary results from IDC Research (IDC)" idc.com/resource-cente…
6:33 PM · Oct 8, 2026 · 3.51K Views
2 Reposts · 6 Likes
DELL continues to act well on both up and down days
- DIS +2.2%: Disney+ will stream the 2027 Super Bowl to all US subscribers (WSJ), and Bloomberg reports DIS is pitching Paramount and Universal on a premium big-screen format to rival IMAX.
- AAPL +1.1% confirmed an Oct. 13 smart-home launch event in New York, and Bloomberg reported a new M&A chief (Steve Smith, with Adrian Perica moving to Services).
- GRMN -2.8% as JPM’s Sensor Tower tracker had Garmin Connect downloads -7.8% m/m in September vs. -5.8% seasonal and MAUs -2.8% vs. -0.1%.
- XYZ -1.1% after Bloomberg reported the FTC is probing whether XYZ’s staff cuts left it unable to handle complaints over frozen and deactivated accounts.
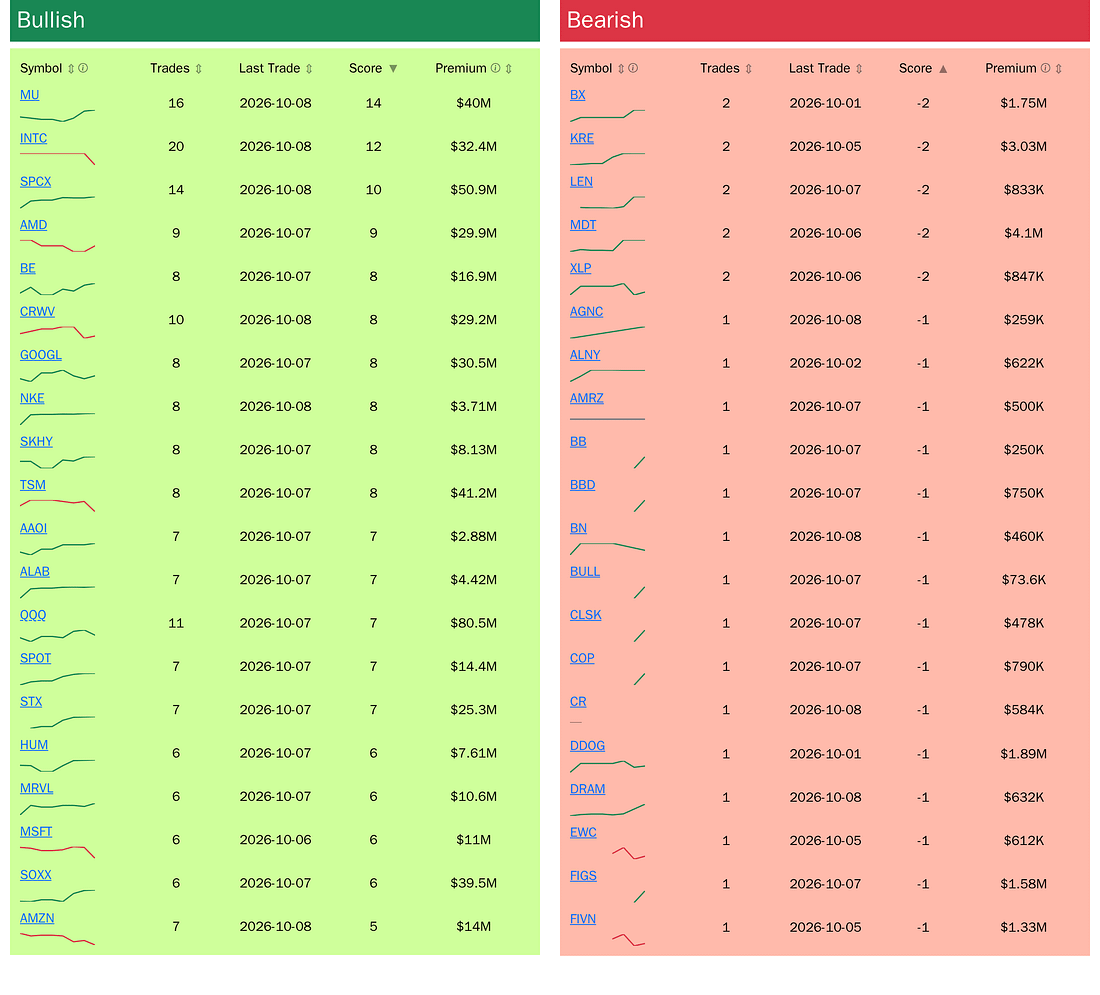
BULLISH AND BEARISH WEEKLY OPTION FLOW
Source: RunningoftheBulltards