2026.10.08 | Substack | Markets | TMTB Morning Wrap
原标题:TMTB Morning Wrap
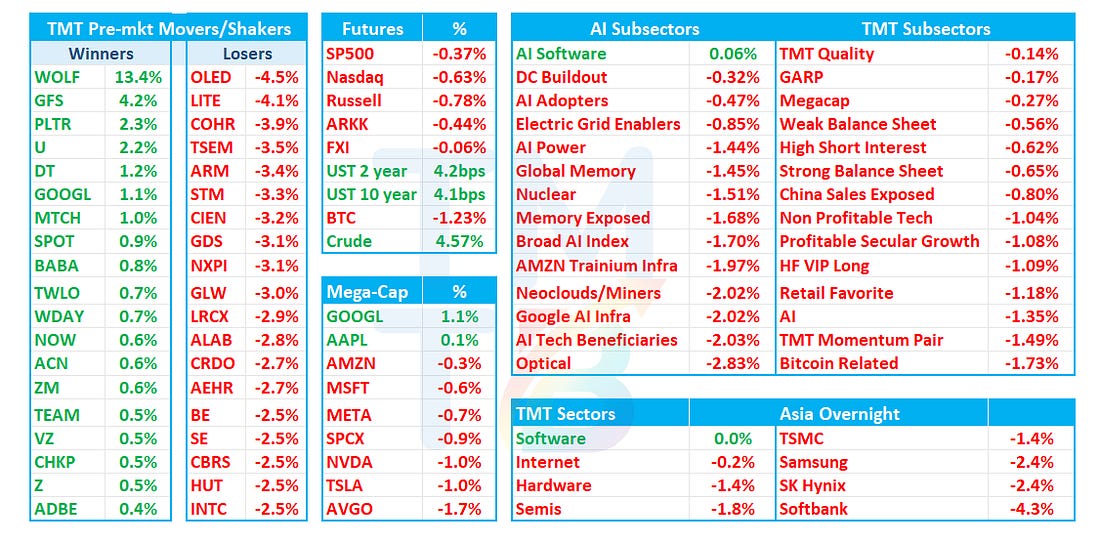
Good morning. QQQs -60bps lower as yields +4bps across the curve and Oil +5% following several Trump is considering air strikes headlines and an uptick in Hormuz commercial ship attacks.:
“Military ordered to be ready for possible Iran strikes as Trump weighs timing” (Axios), “U.S. military prepares new Iran war options ahead of midterm elections” (NBC News), and “Trump Is Considering a Plan to Strike Iran Before the Midterms” (The Atlantic) (h/t VK)
In Tech, focus on Samsung which finished -2% overnight after results that looked light of street, but a bit better than bogeys that had moved lower over the past couple of weeks. GOOGL +1% after announcing Gemini enterprise agents. TSM -1% after solid Sept numbers. U +2% after an RJ upgrade a few other positive sell-side notes.
Overnight, Asia generally weaker: TPX -1.51%, NKY -1.42%, Hang Seng -1.43%, HSCEI -0.89%, SHCOMP -0.79%, Shenzhen -1.63%, Taiwan TAIEX -0.99%, Korea KOSPI -2.62%. Softbank -4%. Samsung/Hynix -2.5%
Let’s get to it…
PLTR: GS upgrades to Buy/$230, sees another estimate-revision cycle as AI TAM expands
GS says PLTR is set for another phase of outperformance into 2027, with sovereign AI, bespoke apps and verticalization potentially driving another step-function increase in TAM. It also sees the FDE model as a durable moat, built on tight field/product feedback loops and increasingly automated via AI FDEs. With shares +16% YTD vs. NDX +24% and at a discount to growth comps on EV/FCF, GS upgrades Neutral to Buy with a $230 PT.
U: Raymond James upgrades to Outperform/$54 as Google partnership strengthens Create/Vector flywheel
Raymond James says Google’s AI + distribution closes a key gap in Unity’s creator ecosystem, bringing the engine to non-coders and potentially driving more content, runtime data and engagement into Vector. Vector has already materially outperformed, growing 23% q/q in 2Q vs. initial 12–13% expectations, with Strategic Grow +63% y/y and 3Q growth guided to 68–70%; RJ sees this supporting durable share gains and margin expansion. It upgrades U to Outperform/$54, valuing shares at 9x 2027E revenue of $2.55B vs. ~7.5x currently and APP at ~8.9x.
NBIS: Rosenblatt initiates Buy/$304, sees ~98% revenue CAGR through 2030 as #2 neocloud scales
Rosenblatt sees NBIS just behind CRWV among neoclouds, with ~250MW active power today and 3.5GW contracted, ~75% expected from fully owned sites. Revenue grew 5.5x y/y in 2Q26 and is expected to grow 6.5x in 2026, supporting a ~98% FY26–30 CAGR. Rosenblatt expects additional debt/equity funding despite customer prepayments, following August’s $5.75B convert, and initiates Buy/$304.
GOOGL: Google Cloud introduces Gemini Agent, a universal enterprise AI agent that autonomously plans and executes tasks across research, content creation, coding and business workflows using organizational context and integrated tools.
Automatically selects models, connects to enterprise systems and includes cost controls, security and centralized governance. Strengthens Google's push into enterprise AI automation, potentially driving Cloud adoption, customer retention and revenue growth.
Reminder GOOGL CLoud CEO Thomas Kurian Keynote at 1:30pm ET.
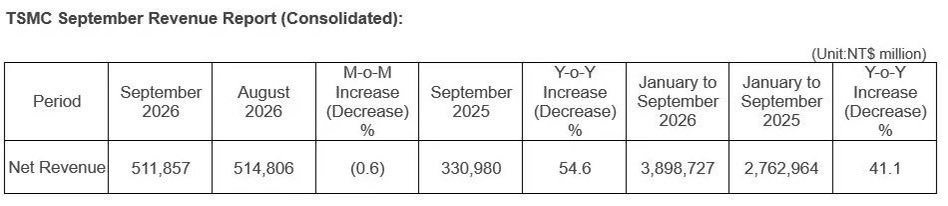
TSM: Sept Revenue -0.6% MoM, +54.6% YoY
Avg Sept seasonality roughly flat m/m (so roughly in inline ex currency). Q3 came in at about US$46.7B, roughly 2% above the top of the guide and 3.3% above the midpoint.
Samsung / Memory: Samsung’s preliminary Q3 operating profit reached KRW107.4T ($80.2B), versus LSEG’s KRW106.1T estimate. This was above buyside bogeys which had moved down to KRW105-106T. Implies 55% OM vs street at 53.8%
AVGO / ORCL / SPCX: AI chip financing expands with $50B-plus OpenAI deal – WSJ
WSJ reports Broadcom is discussing more than $50B of financing for OpenAI’s custom-chip program, starting with Jalapeño, with Apollo, Blackstone and other lenders. The deal could cover several gigawatts and close by year-end. Oracle is separately talking to Apollo and Goldman Sachs about financing chip purchases through a vehicle that would own the hardware and lease it back. WSJ also reports SpaceX’s $40B Nvidia-chip financing talks, first reported by FT on Tuesday.
META
Similarweb
@Similarweb
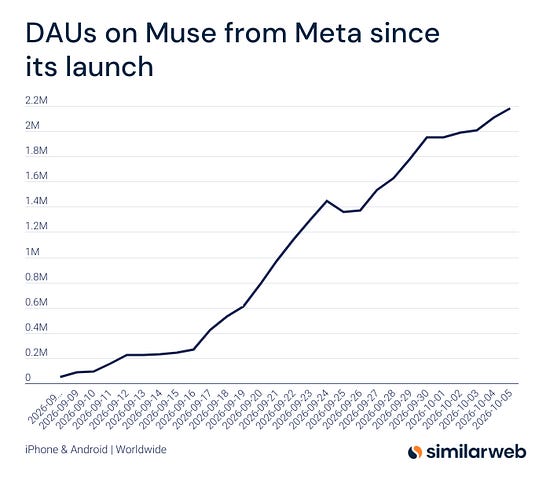
DAUs on @Muse keep climbing, peaking at 2.182 million on October 5th.
7:55 AM · Oct 8, 2026 · 27.1K Views
2 Replies · 19 Reposts · 81 Likes
The chart has four distinct phases of DAU growth (reminder no international launch yet):
- Launch week: Slow, averaging about +28K a day, and stalled around 220–240K from 9/12 to 9/15.
- Inflection (9/17–9/24): Adds jumped to about +145K a day, roughly 1.2M new DAUs in eight days.
- Dip and rebound: After one down day on 9/25, growth returned to about +145K a day from 9/27 to 9/30.
- Since 10/1: Growth has slowed to about +45K a day, or 0–4% daily, though 10/4–10/5 picked back up to +80–90K.
META: Jefferies says Muse demand is strong, but agent access bottleneck could delay commerce monetization and benefit GOOGL
Jefferies finds only ~1/3 of sites work seamlessly with Muse, with ~1/3 blocking access and ~1/3 challenging/restricting it, potentially delaying META’s agentic-commerce take-rate opportunity while reinforcing GOOGL’s distribution/access moat. Still, 40% of advertisers expect Muse to increase META spend over the next 12 months. Buy/$875.
WOLF: TD Cowen says $1.5B DoW loan largely removes financing/dilution risk
TD Cowen says WOLF’s conditional $1.5B DoW loan commitment should put post-bankruptcy financing concerns largely to rest and ease customer worries around liquidity, with PIK structure adding only ~$100M/year of cash burn. The 30-year facility includes $600M initially and $900M across later tranches, supporting SiC/GaN capacity and domestic GaN development. Cowen remains Hold/$25 as SiC demand is still challenged and GaN execution/scaling will take time.
China AI: 24GW operating, with another 50GW planned or under construction – FT
FT reports China has 24GW of operating data-center capacity and another 50GW under construction or announced, citing SemiAnalysis. Ulanqab has 89 facilities built or planned and about 15GW committed, supported by cheap power and 12–18-month construction schedules. FT saw Vertiv cooling equipment at several sites. Facilities using domestic chips receive additional tax and utility incentives, while access to advanced processors remains a key constraint on the buildout.
MRVL: Jefferies NDR reinforces broader DC opportunity beyond XPUs
Jefferies says scale-out drives most of MRVL’s $37.5B C30 interconnect target, while scale-up is a separate $20–30B TAM and scale-across units rise from <1M in C25 to ~3M in C30. Custom is broadening beyond XPUs into attach products, Smart NICs could reach $10B+, inference accelerators ramp from C29+, and Ethernet switching is tracking >$1B next year vs. ~$600M with 100T/UALink upside. Buy/$450.
NVDA / Firmus: $5.5B IPO falters at proposed $30B valuation – Bloomberg
Bloomberg reports Nvidia-backed Firmus’s planned $5.5B IPO is uncertain after demand fell short at A$11 a share, implying a roughly $30B valuation versus $10.5B in August. The company generated $51M of FY2026 revenue and has built 46MW of its 912MW pipeline. Investors flagged further financing needs and an overhang from 58% of shares being tradable at listing; pricing remained unresolved after books closed.
NXPI: Citi downgrades to Neutral/$260 as estimate-revision momentum slows
Citi cuts NXPI to Neutral from Buy and PT to $260 from $370, arguing positive semi estimate revisions slowed in 2Q and should moderate further in 3Q. Citi is becoming more selective and expects NXPI revisions to lag peers given limited data-center exposure.
HUBS: JPM downgrades to Neutral/$240 on delayed AI monetization and uncertain growth recovery
JPM cuts HUBS to Neutral from OW and PT to $240 from $268, citing an uncertain timeline for revenue growth to recover. AI monetization is taking longer than expected, which JPM sees as a medium-term growth headwind rather than a temporary issue.
ANET: Evercore ISI says new rack-scale architecture meaningfully expands AI networking opportunity
Evercore says ANET’s new Etherlink architecture extends Ethernet into scale-up, supporting 144 XPUs single-hop and 1,024 cross-rack, while next-gen optics lift capacity ~4x to 6.5 Pb/s/rack and cut DC footprint ~50%. Flexible designs spanning AMD/Arm/Broadcom/Marvell/Meta/MSFT and NVLink/PCIe strengthen ANET’s ability to serve multiple accelerator ecosystems across scale-up/scale-out. OP/$250.
MSFT: MS says multi-model AI strengthens full-stack moat, enabling monetization across the stack
MS says a multi-model world increasingly favors MSFT’s integrated Azure/Fabric/Foundry/Copilot stack: Azure runs the models, Fabric provides enterprise context, Foundry orchestrates/model-routes and Copilot distributes AI to users, with Maia/Cobalt adding further differentiation. Fabric is already >$2B annualized revenue, >17K customers use both Fabric + Foundry (+60% y/y) and M365 Copilot has ~30M paid seats. This lets MSFT monetize the same AI workflow across infrastructure, data, orchestration and apps while remaining relatively model-agnostic, strengthening the consumption flywheel.
U: DB says Google Spark partnership could open a new creator monetization vector
DB says Unity’s Google partnership could expand revenue across Create/Grow by letting non-coders build games through Spark, widening the funnel from ~1M professional developers toward the ~3B people who play Made with Unity games monthly. Monetization could come from paid Spark tiers, more runtime data improving Vector, greater discovery/UA demand across Unity’s ad network and potential ad/IAP participation within Spark. More creation also strengthens the broader data/ad flywheel, notes DB.
U: Jefferies survey sees U as biggest ’27 share gainer, raises PT to $54 from $50
Jefferies’ 30-buyer survey shows U again as the biggest expected share gainer into ’27, with Q3 customer spend +9% q/q vs. ~20% Vector growth implying continued take-rate improvement. U remains just 10–15% of wallet, leaving room to gain share; Jefferies raises ’27 Vector to $1.69B (+45% y/y), revenue 5% to $2.6B and EBITDA 11% to $951M, lifting PT to $54 from $50.
APP: Jefferies cuts ’27 EBITDA 7%/PT to $375 as gaming share flattens, but reiterates Buy
Jefferies sees APP gaming share roughly flat at ~30% into ’27 after years of gains, making further share expansion harder and putting more emphasis on take-rate improvement. It cuts ’27 revenue 5% to $10.1B and EBITDA 7% to $8.4B, lowering PT to $375 from $550, but keeps Buy as industry spend still grows ~7% in ’27 and APP remains the top ROAS network for 4 of the 9 largest studios surveyed.
TTWO: Hearing M-sci saying pre-orders strong and continue to point to ~50M sell-through through Dec…The Verge reporting Xbox has secured GTA 6 streaming rights
WDAY: Jefferies cuts PT to $210, says growth/margins still lag peers as AI monetization remains early
Jefferies keeps Hold as WDAY’s rev/backlog growth decelerates, with CY27 Rule of 43, low-30s OPM and ~14% backlog growth lagging large-cap peers despite a ~20% valuation discount. AI ARR is only ~$600M/~6% of revenue, while core HCM/FINS growth has slowed and WDAY has gained <2pts of share vs. SAP/ORCL over 4 years. Jefferies likes the AI setup and sticky 80M-user platform but wants subscription growth to reaccelerate beyond ~11%; cuts PT to $210 from $220.
NOW: DB sees solid 3Q + resilient federal demand, with AI upside building into 2027
DB expects a solid 3Q with stable federal trends, modest FY26 subscription guidance upside and ~19.5% y/y cc 4Q cRPO growth, supporting stable organic growth into FY27. A leading federal partner says business is roughly flat despite budget pressure, with core products highly defensible and shelfware now <5% vs. 10–20% ~18 months ago. AI adoption remains early, but outcome-based deployments and expansion from limited initial use cases support more meaningful contribution in 2027; Buy/$155.
Cyber: Barclays VAR call positive on NET/OKTA/CRWD/PANW; mixed elsewhere
Barclays’ security VAR call was most positive on NET, OKTA, CRWD and PANW: NET saw healthy 3Q growth as AI-driven traffic pushed customers into higher tiers; OKTA saw healthy Aug/Sept growth with identity the VAR’s #1 CIO/CISO priority; CRWD posted strong y/y growth and is taking share beyond endpoint; and PANW saw healthy growth with Prisma AIRS traction and neocloud AI-infrastructure demand. FTNT also outperformed, while ZS was more mixed and CHKP/VRNS/RBRK/TENB were softer.
P: Needham raises PT to $185 from $150 after CFO meeting, conviction increases on growth durability
Needham comes away more constructive on P’s growth breadth, with Hyperscale still the main near-term driver and Data Primacy expanding the opportunity beyond traditional infrastructure budgets into CIO/CDO/CISO/AI spend. Evergreen//One should support recurring revenue, retention and cross-sell into Modern Data Software, reinforcing P’s evolution into a broader multi-engine infrastructure platform. Buy/$185.
ESTC: Citi meeting raises conviction on 20%+ sales-led growth, with AI/Metrics upside unmodeled
Citi says FY25/26 execution issues were driven by territory changes and insufficient sales capacity rather than demand, with bookings improvement already showing in cRPO/revenue. New Metrics could reaccelerate Observability, while self-managed AI, Security AI/Attack Discovery and agentic SOC are not reflected in current guidance or FY29 Rule of 45 framework. Buy/$128.
Internet: Evercore reshuffles top longs to AMZN/META/SPOT; TAP Outperform RDDT, Underperform BKNG
Evercore moves AMZN to #1 Large Cap Long on AWS accelerating to +37% y/y, ~39% margins and ~$500B backlog, with PT $355/>40% upside; META falls to #2 but remains favored as Muse/Business Agents expand AI monetization, PT $860; and SPOT replaces DASH at #3 as AI disintermediation fears look overdone and audiobooks/add-ons plus an expected AI tier support ARPU, PT $700/~43% upside. Tactically, Evercore is Outperform RDDT after a -34% YTD pullback with improving ad checks/DAUs and licensing upside, while Underperform BKNG on greater Q4 risk from weak long-haul travel and ~7% Middle East bookings exposure.
SPOT: Citi sees global audiobook rollout as meaningful 2027 gross-margin tailwind
Citi says SPOT is expanding Premium audiobooks to 10+ new markets covering ~20–25% of subs, alongside global Audiobooks+ and direct sales. Based on prior launches, Citi expects ~10% price hikes around mid-2027 with ~90% flow-through to gross profit, driving ARPU and margin expansion. Rollout costs could modestly pressure 4Q26 GM before becoming a meaningful FY27 tailwind.
BABA: MS raises F27/28 EBITA 7–10%, sees cloud accelerating +55% y/y with margin inflection
MS reiterates OW/Top Pick/$180 as external cloud accelerates to ~55% y/y, with EBIT margin expanding to 13.5% and MaaS ARR reaching RMB20B in late Aug vs. RMB16B mid-month; cloud EBIT should exceed RMB10B/~15% margin in Dec Q, fully offsetting AI Labs losses. E-commerce is holding with CMR -5% y/y but +1% LFL and EBIT +LSD, while F27/28 capex stays RMB250B/RMB260B with no further equity funding planned for F27.
GPN/FISV: Oppenheimer upgrades GPN, downgrades FISV; TOST/XYZ estimates above Street
Oppenheimer upgrades GPN to Outperform/$115 as <6x NTM P/E discounts 2026 risk, with lower one-time costs/opex leverage driving 2027 EPS ~4% above Street. FISV falls to Perform on continued execution risk and dependence on delayed implementations for a 4Q ramp, while TOST/XYZ are ~1%/~1.5% above Street on gross profit and both ~4% above on EBITDA. FOUR likely trims guidance on Middle East exposure, while WU Street estimates look too high.
GRMN: JPM tracker shows softer-than-seasonal September downloads, creating mild 3Q setup risk
JPM says Garmin Connect downloads fell -7.8% m/m in September vs. -5.8% seasonal and MAUs -2.8% vs. -0.1% seasonal, though YTD downloads remain +20.6% y/y. JPM’s 3Q Fitness/Outdoor revenue forecast of $1.289B remains above Street’s $1.259B, making the softness a mild setup risk rather than a fundamental break.
NEWS
OpenAI / Anthropic: Price cuts bring OpenAI level in OpenRouter spending sample – WSJ
WSJ reports OpenAI and Anthropic split spending roughly evenly in September among 120,000 companies tracked by OpenRouter, versus Anthropic’s 75% share at the start of the year. The sample is weighted toward AI-native businesses. OpenAI cut GPT-5.6 Luna pricing 80% and Terra 20% after launch, while Retool says using OpenAI now costs it about 20% less than Anthropic.
Anthropic: Haiku 5.5 launches at 75% lower cost – Reuters
Reuters reports Anthropic launched Claude Haiku 5.5, its third Claude 5.5 model in a month, with a stated cost 75% below Haiku 4.5. Pricing starts at $0.10 per million input tokens and $0.50 per million output tokens for prompts below 100,000 tokens. The model targets support, voice assistants and other high-volume tasks, and adds safeguards for selected high-risk cybersecurity requests.
Claude
@claudeai
Haiku 5.5 is our first Haiku model with an adjustable effort setting, so you can decide whether to optimize for cost or intelligence on each task.

6:01 PM · Oct 7, 2026 · 245K Views
34 Replies · 60 Reposts · 2.27K Likes
Data Centers: San Francisco adopts immediate 45-day development moratorium – Bloomberg
Bloomberg reports San Francisco unanimously approved an immediate 45-day ban on new data centers while considering longer-term restrictions. The moratorium can be extended for roughly two years. Officials cited electricity, water and environmental concerns, with the ordinance’s sponsors specifically targeting a proposed development in Bayview-Hunters Point.
CRWD / Cybersecurity: CrowdStrike links Korean bank breaches to AI-assisted attacker – Reuters
Reuters reports CrowdStrike suspects a China-based attacker used the ARTEX penetration-testing agent and Anthropic’s Claude Code in breaches targeting South Korean banks. At least nine banks have disclosed or been reported as targets since late September; Shinhan exposed data on about 25,000 customers. CrowdStrike says the case shows how one attacker can use AI agents to target many organizations quickly.
MU / Samsung / SK Hynix: Counterpoint pushes back on reports of lower HBM content – EBN
EBN reports Counterpoint’s checks indicate most Nvidia Rubin products are converging on 12-layer HBM, countering speculation that the platform would move to eight layers. The research firm also found no evidence of the four-layer HBM configurations rumored for custom AI chips. Counterpoint says HBM requires more than three times the production capacity of conventional DRAM, keeping pressure on broader memory supply.
BESI / HBM: Hybrid-bonding delays weigh on shares as memory shortages persist – Bloomberg
Bloomberg reports Besi shares fell 14% this week after UBS cut its rating to sell and BofA moved to neutral. Investors worry memory shortages and the cost of hybrid bonding will delay adoption. SemiAnalysis says Nvidia’s Rubin Ultra will use fewer memory layers, reducing the immediate need for Besi’s tools; Bernstein still expects adoption longer term as memory supply catches up.
NVDA / MSFT: RTX Spark Windows PCs open for orders; shipments start October 16 – DigiTimes
DigiTimes reports Nvidia-powered Windows laptops are available for preorder across Microsoft, Dell, HP, Lenovo, ASUS and MSI, with shipments beginning October 16. Microsoft’s Surface Laptop Ultra starts at $2,599, while its $5,999 RTX Spark Dev Box ships in November. The platform combines Nvidia’s Grace CPU and Blackwell GPU with up to 128GB of unified memory; MediaTek helped design the CPU
TSM / ASX / AMKR: Analysts see CoWoS capacity rising 57% in 2027 – China Times
China Times reports analysts expect TSMC’s monthly CoWoS capacity to increase from 140,000 wafers at end-2026 to 220,000 at end-2027. They estimate related outsourced packaging capacity at ASE, SPIL and Amkor will rise from 40,000 to 65,000 wafers. The report also cites forecasts for TSMC capex of $80B in 2027 and $100B in 2028; these are analyst estimates.
SK Hynix / Solidigm: Banks selected for potential $10B US IPO in 2027 – Bloomberg
Bloomberg reports Solidigm has selected Goldman Sachs and Morgan Stanley to lead a US IPO next year that could raise roughly $10B. SK Hynix’s SSD subsidiary is also pursuing a pre-IPO funding round and has discussed a valuation of as much as $100B. The planned listing comes as AI infrastructure spending boosts demand for enterprise storage.
TCEHY: Considers up to $5B offshore bond offering – Bloomberg
Bloomberg reports Tencent is considering raising as much as $5B through dollar and offshore-yuan bonds, potentially as soon as October, after a $4.7B sale in June. The financing discussions come as the company accelerates AI investment: capex in the June quarter rose 176% to RMB52.8B ($7.9B).
META: Florida seeks teen ad ban and two-hour daily usage cap – Reuters
Reuters reports Florida asked a court to impose immediate restrictions on Facebook and Instagram, including removing accounts held by children under 14, limiting teens to two hours of daily use across Meta apps, and disabling advertising, autoplay and infinite scroll for minors. Florida declined to join the separate settlement with 48 states and Washington, DC, which could cost Meta up to $18B.
DIS: Disney+ will stream the 2027 Super Bowl – WSJ
WSJ reports Disney+ will carry the 2027 Super Bowl for all US subscribers, alongside ESPN and ABC coverage, and in more than 55 international markets. Disney+ will also stream two Monday Night Football games this season, beginning with Cowboys–Eagles on October 26.
Blue Origin: Bezos sees IPO within several years after $10B outside raise – Bloomberg
Bloomberg reports Jeff Bezos said an IPO would likely make sense for Blue Origin within several years. The company recently raised $10B from outside investors and may raise more, following $28B of funding from Bezos. He expects New Glenn to return to flight in December after the May launchpad explosion.