2026.10.08 | Substack | TSM | TSM 26Q3 Preview: Capacity Pace
原标题:Preview|TSM 26Q3: Revenue Growth Depends on the Pace of Capacity Expansion
26Q4 Revenue Growth Forecast at 11% QoQ
TSMC reported 26Q3 revenue of NT$1,494b, up 17.6% QoQ (+16.2% in USD terms) and about 2% above the high end of guidance. We estimate 26Q3 gross margin at 67.6%. With N3 capacity fully utilized and end products using N2 entering volume production, we project 26Q4 NT-dollar revenue growth of 11% QoQ (+11.7% in USD terms). AI GPUs continue to support wafer demand in 2H. The shift toward Agentic AI in edge and cloud inference is also prompting CSPs to increase wafer starts for high-core-count server CPUs and proprietary ASICs, keeping overall 3nm capacity utilization consistently above 100%. For TSMC and its customers, demand remains strong, with insufficient capacity the main constraint.
Advanced-Node Price Increases Likely in Early 2027
 Subscribed
Despite ongoing capacity expansion in Taiwan and overseas, we expect N3 capacity to remain tight into 2027 as AI demand for advanced nodes continues to grow rapidly. We expect advanced-node prices to rise about 10% in early 2027 and prices for the remaining mature nodes to rise about 5%, lifting overall ASP. Previous media reports put the price increase in July 2026. Our channel checks indicate that TSMC began notifying customers at that time; the new prices had not yet taken effect.
2027 Capital Expenditure Could Reach $85–87b
Advanced-node expansion, rising semiconductor equipment prices, and construction across multiple overseas locations underpin our forecast for 2027 capital expenditure of $85–87b. We expect TSMC to continue working with equipment vendors to expand capacity. We estimate that 3nm capacity could reach 200,000 wafers per month by the end of 2027 to meet demand as AI ASIC shipments more than double that year.
Financial Forecasts
TSMC announced its September revenue on October 8, bringing 26Q3 revenue to NT$1,494b, about 2% above the high end of guidance. We expect 2027 NT-dollar revenue growth of 38.5% and EPS of NT$151.6. Near-term revenue growth is constrained by supply. We believe many major AI customers have already begun discussing capacity expansion with TSMC to meet demand beyond 2030.
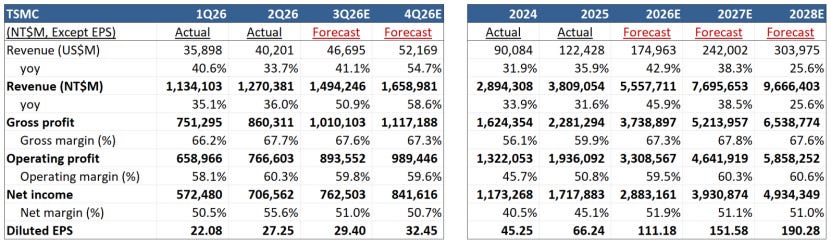
Source: Company documents, FUNDA estimates