2026.10.12 | Substack | Markets | TMTB EOD Wrap
原标题:TMTB EOD Wrap
TMTB EOD Wrap
TMT Breakout
Oct 12
READ IN APP
Good afternoon. QQQs -70bps never saw green on a low volume holiday , hiding another degross out of anything with AI-capex or AI-financing beta while megacaps held in (META +3.4%; AAPL +1.3%; MSFT +1%).
Let’s start with the good news first before talking about the sea of red that was semis today. The day’s big launch landed at 12:55pm when META released Muse Wonder (aka Watermelon), reaching the frontier and only behind Claude Opus 5.5 on AA’s Intelligence Index.
 Alexandr Wang@alexandr_wangMUSE WONDER this is the culmination of over a year of research and infrastructure work in msl since we originally shipped muse spark in april, we have continued to scale our models across pre-training and RL, now reaching the frontier 🏆 see our model's improvements on the …
 5:01 PM · Oct 12, 2026 · 211K Views165 Replies · 225 Reposts · 3.26K Likes
Muse Wonder claims 57.5% on SWE-Marathon vs 46.3% for Opus 5.5, and it’s priced at $4/$20 per million input/output tokens, similar to Opus 5.5. Zuck told the FT META is “already working on the next step up” and will sell the best versions of Wonder directly to businesses while also signaling more spending and rejecting slowdown calls. Wang and Zuck were on the podcast circuit today. We covered them in TMTB Podcast Intel brief from today - the cheeky pint pod with Wang and Zuck worth a full listen if you have the time. FT also had an interview with Zuck. Some key quotes from both:
Part of our philosophy on this is that you can kind of measure the compute strength of a lab by how big its largest single computer is, supercomputer, for being able to do these large training runs… So, I mean, we built this Prometheus cluster, we call it, in Ohio…That's scaling to larger than a gigawatt. And now we're building this Hyperion cluster in Louisiana that's going to scale to 5 gigawatts. Well, I guess the Louisiana one will come online over a couple years.
One is if AI works overall, plenty of other people want all our compute. Right? So they're willing to pay, like, I mean, if like the cost is whatever, $15 billion a gigawatt, we could get like a lot more for that. So I think that you, in order for it not to work out, it's not just that we have to fail, AI overall has to fail. And then even if that happens, we still have all these other uses to productively use compute. So in the grand scheme of things, we were definitely building out this compute for inference ahead of knowing that the product was going to be ready.
And that's also a financial advantage for us building out the data centers as opposed to a bunch of the other companies that are paying clouds, whereas they're paying the annual rate, but then at some point the GPUs will be fully depreciated, but we're probably still going to be using them for a while […] the value of even like an H100 at this point is higher than it was last year, right? Just because if compute continues being constrained.
We'll also have the API that'll be profitable. A big part of why we want to start the Meta Enterprise Platform and have CJ Desai join us to build this is we have this view, which is like, all right, yeah, sure. So traditionally Meta hasn't been an enterprise company, but we believe that a huge part of the challenge is building the leading models in the first place. And they're very general. And once we do that, if we make a significant investment in building an enterprise group that can provide that in the way that enterprises need to consume it, then I mean, I think a lot of enterprises are going to want to use Muse Wonder. It's going to be an excellent model and affordable.
And we hope to, you know, at some point not too far from now, have a model that is as good as Wonder, but in the Spark form factor. And that will be a great thing to be able to serve hundreds of millions of people around the world.
Muse Wonder will also be “closed”, with its best versions sold directly to businesses.
“I’m much closer to the belief that AI is a technology that can be engineered with normal guardrails and built responsibly than the anthropomorphic vision of AI, which is that it is just going to go do its own thing,”
Believes Meta needed to be at AI’s frontier to deliver this vision, noting a “dichotomy” where models are rapidly advancing in certain academic fields but “still don’t have enough common sense to be the ideal personal assistant”
“A company like Meta is going to do way more things than it does today, but each thing may potentially be able to be done with somewhat fewer people,” Zuckerberg said. “I would guess that in the future, way more people are going to have the job of working with technology to make things than [they] do today.”
Interesting take in TMTB Slack about why being at the Frontier is important for META:
Which dovetails with Zuck’s comments on Cheekypint:
The other thing is that we use the models to accelerate our core business, right? So I mean, you have this core business that’s hundreds of billions of dollars and still growing extremely quickly. And now, like, if you can grow it a few percent faster by using these models to accelerate these things, then that ends up funding a huge amount of this too as you’re scaling it out.
This is kind of Meta’s whole playbook, right? Is we build something, we get it to a billion people, then we scale the revenue while growing our revenue primarily in the meantime by continuing to scale the things that are already kind of at scale and growing.
Ok, back to semis -2.7% (many names down 3%+), which took the brunt of the beating today as we saw more follow-through on the rotation out of semis that started mid-week last year and was turbo-charged by the Thursday’s “Great OpenAI Gross-to-Net Panic of 2026.” While we don’t think the $70B → $50B gross-to-net realization materially changed the narrative (see our Thursday EOD wrap for the glass-half-full vs. glass-half-empty takes), it did add doubt at the margin and reminded investors how much of the AI trade currently rests on the ARR trajectories of two private labs whose financials remain largely opaque. This has become more evident today as investors struggle to figure out what expectations are for Anthropic’s ARR amid worries we might get another sell-everything in reaction to a headline miss, especially when the market is placing so much weight on numbers for which it has so little underlying visibility.
While Zuck said they weren’t slowing spending, BTJ explained the bearish readthrough from Muse Wonder in TMTB Slack here: the frontier was “an effective duopoly that required infinite external capital raising”; if it’s now an oligopoly with META (and potentially GOOGL and xAI), “what is the revised value proposition for investors of investing in the frontier labs?” And VK highlighted another point: “As the hyperscalers launch increasingly capable models, they have less need to pay OpenAI and Anthropic. Therefore, models like Muse Wonder are a double-whammy negative for Anthropic: more competition and less revenue from a huge customer.”
On top of the already tee’d up rotation (not surprising to see more follow through on that front), several other things being passed around further hitting AI sentiment. Just one of those days where every piece of news flow is seemingly negative and attributed to the weakness, with most highlighting Hock Tan’s comments saying capital, not memory is AI’s biggest hurdle and likening some AI investors to “casino gamblers” w/o understanding the tech although he also had bullish comments in same interview saying compute demand exceeds supply into 2030. Steve Eisman comments were also being passed around flagging weak chatbot loyalty/pricing power and investors’ limited diversification, estimating >65% of the S&P is AI-linked.
Other reasons for the sell-off we heard today: NVDA’s reported Reflection AI acquisition talks raising more competition concerns. Nadella’s call for an AI “emergency brake” although investors seem increasingly desensitized to safety headlines. Elsewhere: Memory/HDD pressure following density comments from CXMT’s CEO, with Hynix/Samsung down ~4.5% overnight.
Positioning still skews long semis which has made this a frustrating market for many. Here’s how we framed investor sentiment in our weekly yesterday:
The trade was about as easy as it gets back in May/June. Since then, it’s felt like a knife fight despite many names being up significantly from the Leopold lows: false starts and failed breakouts, mixed reactions to positive news, and lots of chop. As we wrote last week: some debates have shifted in the bulls’ favor, but they haven’t been resolved. That’s been evident in our conversations this week. Our conversations late in the week remained broadly positive on fundamentals, but we heard more frustration about the lack of sustained breakouts & price action. We still feel fine about the fundamentals driving the semi trade, but we’re less convinced about when, or what, will drive a more durable inflection in the vibe/debate.
With semis charts needing repair and sentiment mixed to put it lightly, we're not in the mood to take any ST/MT swings unless charts improve, something changes the prevailing narratives, or we get juicy r/r entries.
 Hiroo Onoda@OnodaCapitalGS sentiment indicator is sneaking into 2022 and tariff levels
 6:08 PM · Oct 12, 2026 · 1.88K Views2 Replies · 9 Likes
Weak retail sentiment highlighted by Paradis in TMTB Slack:
In macro land, rates took the day off with the cash Treasury market shut, leaving the 10Y at 5.24% into Wednesday’s CPI. Futures have ~17-19% odds of a 10/28 hike, a touch below ~20% last week and way down from 70%+ in late September. Crude caught a bid (USO +1.9%), reversing an early dip on Trump’s Russia-Ukraine “energy ceasefire” as doubts grew, with Houthi missiles hitting Riyadh’s airport over the weekend. BTC -97bps to ~$82.8K.
Let’s get to the good stuff…
AI/SEMIS
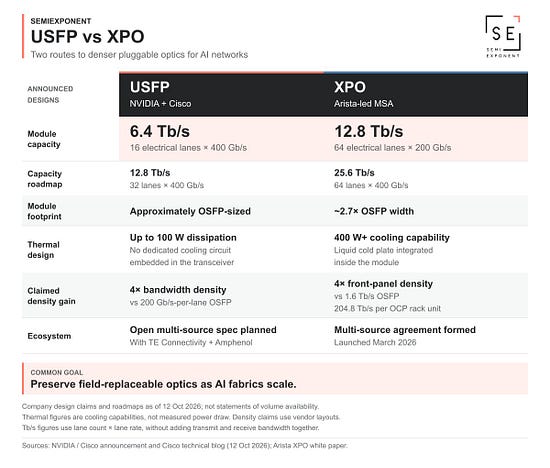
- Optical weaker on some sell the news ahead of OCP: CIEN -10%; LITE -9.8%; COHR -7.9%; CRDO -7.3%; GLW -6%. Stocks were weak in two legs: an opening degross with the rest of AI infra, then another leg at 11am when NVDA and CSCO announced USFP at OCP, an open pluggable form factor of 16 lanes at 400G (up to 12.8Tb/s, 4x the bandwidth density and 1.3x the power efficiency of 200G-per-lane modules), with TEL and APH building the ecosystem (good comparison with ANET’s XPO here:
 Vikram Sekar ✈️ OCP@vikramskrNVIDIA and Cisco’s USFP and Arista’s XPO are taking different routes to higher-density pluggable optics. USFP puts 16 electrical lanes at 400G into an OSFP-sized footprint using a new connector. That gets you 6.4T, with a path to 12.8T. XPO starts with 64 lanes at 200G for …
 4:24 PM · Oct 12, 2026 · 3.5K Views4 Replies · 1 Repost · 28 Likes
FZ in TMTB Slack explained the newer bear case: LITE’s driver is scale-up, not scale-out, so if the power constraint bites, scale-out optics revenue suffers “because rev get booked at shell level not rack level,” and if USFP/XPO use low-power CW lasers, “this is a bear case for LITE/COHR.”…More from Claude (just passing along - still digging into this):
Evercore’s morning tactical add on LITE dell on deaf ears. Bulls will push back pointing to continued positive checks across the space (see LITE’s InP laser capacity sold out into early 2029); bears will add the medium-term risk is 1.6T and new pluggables shifting to cheaper CW lasers as InP capacity comes on, normalizing EML pricing. And into prints, investors remember that last quarter’s networking beat-and-raises “in many cases were sold.”- SNDK -6%; MU -3.9%; SKHY -4% followed Korea lower (KOSPI -3.65%) after SCMP reported CXMT will launch DDR5 server modules on its denser 4F² DRAM architecture by year-end, the cell structure Samsung and SKHY are also chasing (CXMT’s own A-shares fell 5%). Lip-Bu Tan flagging memory as the first segment likely to lose momentum didn’t help, and DIGITIMES reporting Samsung locked 75-80% of its 2027 output into long-term deals with NVDA, GOOGL and MSFT got ignored. Asian Investors are focused on a Korean “buyer strike”: Samsung’s buyback is done, SKHY’s ~85% done. Daishin out saying talks on mass-producing lower-stack (4/6-high) HBM have effectively been called off and the 12-high-to-8-high shift scaled back, but the de-spec debate rages on.  Jukan ✈️OCP 2026@jukan05Daishin Securities (Korea): Discussions on mass-producing lower-stack HBM (4-high/6-high) have effectively been called off. The shift from 12-high to 8-high has also been scaled back.4:40 AM · Oct 11, 2026 · 114K Views31 Replies · 29 Reposts · 391 Likes
Narrative continues to be muddied here with lots of push and pull between bears and bulls.
- STX -3.8%; WDC -2.6% stayed heavy on the Toshiba HDD capacity overhang, even as Evercore added WDC to its tactical list. Good pushback in TMTB Slack here: MK said 2028 is already locked in with 2029 pricing talks ongoing and Toshiba won’t dent a ~400EB shortage, while Ted argued “pods have decided that memory and HDDs deserve derate on LT multiple and supply risk.” to note WDC moved its print up to report before STX.- BE -6.5%; OKLO -7.2%; SMR -6.9%; NBIS -5%; IREN -1.1%: AI power and neoclouds took the financing worries hardest, IREN reversing a +3.2% open on The Information’s report of an Anthropic cloud deal (”Deals don’t matter anymore…not sure what does,” as K put it in TMTB Slack here). BofA’s chart making the rounds - CBRS -10.7% made new post-IPO lows with no news, back below its $185 IPO price since the 10/1 lockup expiry.- INTC -3.2%; AMD -2.3%; QCOM -61bps got no help from Commercial Times reporting CPU price hikes spreading: INTC +15-20% on high-end Panther Lake, QCOM ~10% on Snapdragon X, AMD preparing its own.- WOLF -8.4%; NVTS -7.3%; AEHR -7.6%; SITM -6.9%; TSEM -5.3%: the high-beta semis got hit hardest on no company news.- NVDA -1.3% held in better than the group despite MSFT’s Maia 300 (”same type of news from a Hyperscaler that pops up 2-3x a year,” per Akh in TMTB Slack here). Reminder, NVDA says its share of top-5 hyperscaler IT capex rose to 38% in 2Q26 from 11% at the start of 2023 and should reach 44% by end-2027.- TER -4.7%; KLAC -2.8%; LRCX -2.9%; AMAT -1.9%; ASML -1.7% sold off into ASML’s print Wednesday, even as Jefferies’ preview for TSM -2% (reports Thursday) took TSM capex to $85B in FY27 and $100B in FY28 from $62B this year on 10%+ blended wafer price hikes.- AVGO -1.9%: JPM named it a top pick heading into 3Q earnings season, seeing custom XPUs going from ~32% of accelerator units in CY25 to ~43% in CY26 and ~56% in CY27.- ADI flat held in after UBS’s bus tour, where management sized its incremental data-center analog SAM at ~$1.0-1.5B per GW, a potential ~$6-7B annual revenue opportunity over three years on top of a ~$2B DC run-rate.- ON -2%: Bloomberg reported Friday night that CRUS made an unsolicited bid for SYNA last month, after ON’s agreed deal to buy it.- SPCX +52bps: Elon put Starship Flight 15 about 4-6 weeks out with “at least 50 or 60%” odds of a catch.- ASML -1.7% as The Elec reported ASML will raise prices 10% across replacement parts for EUV and DUV systems supplied to Korea from January 2027
 Peter Walker@PeterJ_WalkerNew from OpenRouter: Anthropic's Opus 5.5 has propelled them back above OpenAI in recent weeks. It's the top model in share of spend (right-hand bars) but it is also seeing major token demand (left-hand bars). Impact of Sonnet 5.5 and Haiku 5.5 growing as well
 6:39 PM · Oct 12, 2026 · 14.1K Views10 Replies · 16 Reposts · 155 Likes
INTERNET
- META +3.4% hit +4.7% after the release before fading (trmn in Slack pointed to “fears of significant capex raise given ‘no slowdown’ comments”), and the launch was well flagged: prediction-market odds of Watermelon by 10/15 had jumped 41pts to 88% this morning on Wang’s and Zuck’s teasers. The release helps bulls who argue the street carries little from new revenue like a model API or selling Wonder to businesses (the medium-term bull case); bears will say “the next step up” is the open-ended spend they worry about, with 2027 expenses already seen MSD above the Street. While largely expected, we think the release continues to put a higher floor on META’s stock, but we likely need to see a solid print to get this above $800.
On the Muse app, Sensor Tower had some good retention stats DeedyDas posted
 Deedy@deedydasMeta Muse's retention is out, and it's almost as good as ChatGPT! It's higher than ChatGPT at D7 (>30%) and just lower at D14 (22%). Not quite in the elite D14 tier of WA (67%) YT (59%) Insta (54%) or TikTok/Snap (37%), though. Muse is one of the highest retaining AI products!
 2:41 AM · Oct 12, 2026 · 400K Views166 Replies · 126 Reposts · 1.34K Likes
- SHOP +5% continues to act well and now +40% since the post-Muse lows. Hitting up against resistance so we’ll probably use the opportunity to lighten up a bit ahead of EPS but chart continues to look juicy:
- CART +15bps. Interesting quotes from Zuck on Cheeky Pint
I didn’t really use Instacart that much before. You know, it’s like every once in a while, maybe twice a year, I would like like, use Priscilla’s account or something. […] I went and got an Instacart account to give Muse, and now I use it like once or twice a week because like I’m talking with Aurelia with Muse, and we’re coming up with these recipes, and it’s delivering them, and now it’s like a core part of my workflow. So I actually think that the opportunity here isn’t just, okay, it’s going to be 20% more efficient on the conversion rate. Like, I am a new Instacart like subscriber, and I just wouldn’t have done this before.
Is that Instacart account really for me, or is it for the Muse? Because I think, like, over time, I think that the question is, is the total addressable market for all of commerce just increasing dramatically?Because it’s not just the people anymore. Like, now agents are effectively going to have accounts. And I think that’s where this starts to, like, become a really very exciting opportunity where anyone who sits this out, I think, is going to end up feeling sad over time.
I guess he’s talking about this guy:
Speaking of: AMZN -1% on the day after a nice run last week. WSJ reported AMZN is in talks to buy Decart for ~$7B; its software moves AI workloads between chips, and EBN says it could help customers migrate from NVDA to Trainium.
- EBAY +2.2% as MS made it a Top Pick on live commerce: Western live commerce has grown 5x to $27B and drives ~40% of eBay’s FY26 GMV growth, with MS at ~6.5% GMV CAGR for ‘26-30 vs the Street’s ~4.9%. That helps bulls who argue Live and C2C make GMV growth durable (the medium-term case); bears like Wells will say the Live/C2C investment and Vinted competition cost ~210bps of margin in ‘27, with its ‘27 EPS 8% below the Street.- · SNAP +5% ripped on very little: a Wells preview making the rounds on X
 BoxLongs@BoxLongs$SNAP WF RAISING ESTIMATES IN PREVIEW, DRIVEN BY SNAP+ Estimate revisions, price target, and valuation. 3Q revenue / EBITDA unchanged, but 4Q:26 / 2027 revenue moves 1% / 2% higher on +HSD Snap+ revenue revision, partially offset by F/X. As a function of higher revenue and …
 11:06 AM · Oct 12, 2026 · 5.25K Views9 Likes
nudged 4Q26/2027 revenue up 1%/2% on higher Snap+ revenue while staying at Hold, and the stock ground higher most of the day (as much as +6.5%).- RBLX +3.1% as data continues to get less worse- RDDT -6bps was -5.3% at the lows: Wells raised 3Q revenue/EBITDA estimates 7%/13% on strong ad checks but says AI Overviews (>80% of US desktop queries) leave DAUs 2%/7% below the Street in 3Q/4Q…stock -2.5% after hours but don’t see anything- NFLX +45bps as Yipit said net adds tracking 150k above street in UCAN- CPNG -3.4% fell as the Korea Herald reported lawmakers renewing criticism of its standoff with the government; TMTB Slack debated here whether that or last week’s gains is the driver.- SE +70bps: Anon User gave the bull case in the new TMTB Slack #idea-dinner channel:
SOFTWARE
- CRM +2.1% faded most of a +5.1% pop on BofA’s double upgrade to Buy, reversing its AI-disintermediation call: enterprises won’t replace platforms that hold their business logic, data, workflows and compliance (now 16x CY27 EV/FCF vs 9x before, peers 15x). The same morning, Wells’ 100-CIO survey had some CIOs migrating off Salesforce toward MSFT’s Dynamics. Bulls will say BofA is coming around to their long-term case that AI still needs CRM’s data and workflows; bears will say management’s “organic, normalized” double-digit growth for next year excludes big deals and license.- NOW -38bps round-tripped a +5.2% opening pop on RBC and Wells target raises. A check we heard: at one NOW partner every renewal has moved to the AI tiers at a 10-25% bill uplift, though bundled credits are barely used and seat cuts are “really a 27 thing.- · MSFT +1.1% outperformed after Nadella posted
 Satya Nadella@satyanadellaToday we are announcing our biggest bet yet on our own silicon. Starting next calendar year, we will scale our Maia family to multi-gigawatt deployments, making it the primary inference system for our own product and services. And we’re introducing Maia 300, which delivers 40% …
 1:03 PM · Oct 12, 2026 · 336K Views278 Replies · 528 Reposts · 4.97K Likes
that Maia goes to multi-gigawatt deployments starting next year as MSFT’s primary inference system, with Maia 300 delivering 40% more tokens per megawatt than leading GPU systems. Wells’ 100-CIO survey also had 52% picking MSFT as a top-3 AI budget gainer (AWS 34%, GCP 16%).- ADBE -1.7% as Wells downgraded to Underweight: its CIO survey flags ADBE as a clear AI-budget share loser, and with no price increase and a CEO/CFO transition it has FY27 ARR growth at ~7% vs the Street’s >8%.- MNDY -4.7%; HUBS -2.2% as Barclays downgraded both: MNDY’s AI ARR is only ~1% of total as growth slows to a 16-17% Q3 guide; at HUBS, customers are cautious and April’s GTM disruption weighs on pipeline through 2H26.- PANW -3.6%; CRWD -4.4%; ZS -3.4%; gave back Friday’s rally from the open despite bullish notes: Jefferies’ reseller survey shows the cleanest cyber pipeline breadth in 11 quarters, and ZS’s investor day set FY31 ARR targets of >$8B base and $10B with faster AI adoption. - AKAM -5% sank as Evercore ISI’s math put its $11.6B Anthropic deal at a ~10.9% IRR vs a 10% WACC, only ~$1.04/share of NPV. FSLY gave back ~60% of Friday’s +15.9% upgrade pop- ORCL -2.8% traded with the AI-financing names, its 5-year CDS at a record 261bp into the weekend.- DT +2.8% outperformed DDOG -2% as Jefferies prefers DT: renewals set up a F2H27 ARR inflection (DPS ARR up for renewal +50% y/y), while DDOG’s largest customer is expected to cut usage from 3Q.- U -43bps; APP -2.2%: Wells has U’s 3Q Vector growth at +27% q/q vs a +19-21% guide with CPMs +20-30% y/y; BTIG’s checks have APP’s gaming take rate stable at ~35-38% but show share loss to META and TikTok as inventory costs rise.- · ACN +2.8%; CTSH +81bps: the AI-loser squeeze kept going in IT services, with HCLTech signing a pact with Anthropic to set up a dedicated business unit, Reuters reported.
ELSEWHERE
- VZ +2.7%; TMUS +2.2%; T +1.4% bounced after Friday’s crash on SpaceX buying Grain’s 800MHz spectrum for ~$8B (TMUS -13% to a 33-month low). Raymond James upgraded TMUS, arguing SpaceX is 3+ years from being a meaningful wireless competitor, and TMUS’s CTO pushed back on LinkedIn that spectrum alone doesn’t make a network.- TTWO -2.2%: red day, as is tradition. Wells trimmed NBA 2K (units -10% y/y on mixed feedback to the new shooting mechanics) and sees the 3Q bookings guide at $3.35-3.4B vs the Street’s $3.446B.- AAPL +1.3% made new all-time highs, “unch’d from the reporting of iPhone 18 slowdown,” as Ted noted in TMTB Slack here. JPM called the supplier cuts “timing, not demand,” with iPhone units -18% offset by ASP +20% in F1Q27.- HPE -4.3%; SMCI -4.5%; DELL -1.7% got hit with the rest of AI hardware on no company news, though SMCI had a contractor plead guilty in the NVDA chip-smuggling case, DCD reported.- IONQ -9.1% as it agreed to buy zero-trust security company Elisity for up to $1.3B in stock (up to $150M of it earnout); RGTI -5.6% in sympathy.- LCID -9.4% extended last week’s slide as RBC cut its target to $4 from $7 ahead of 11/9 results; RIVN -3% with CFO Claire McDonough leaving 10/30, the day after the 10/29 print.- SOFI -3.6% near its 52-week low as KBW cut its target, citing a >$1.0B gross 3Q rate headwind before hedging, capital pressure and a worse revenue mix.- SKYD flat: Variety now has Digger losing ~$245M theatrically after a 60% second-weekend drop.
BULLISH AND BEARISH WEEKLY OPTION FLOW
 Source: RunningoftheBulltards
Disclaimer:
This newsletter is published for informational and educational purposes only. Nothing here is individualized investment advice, a recommendation tailored to any person’s circumstances, an offer, or a solicitation to buy or sell any security or financial instrument. This newsletter is not an investment advisory service, and no advisory or fiduciary relationship is created between me and any reader.
*I actively trade the securities discussed here, often short-term. My positioning may be inconsistent with the views expressed, and I may buy or sell — including immediately before or after publication — without notice or updates. Price targets, upside/downside scenarios and time frames are illustrative opinions, not commitments to hold. *
This publication is for the subscriber’s personal use only and may not be redistributed, republished, forwarded, or quoted without prior written permission.
Copyright © 2026 TMT Breakout. All rights reserved.
Full disclosures here